
Boeing and Icelease Sign Agreement for up to Three 767-300 Boeing Converted Freighters
Source: PR Newswire
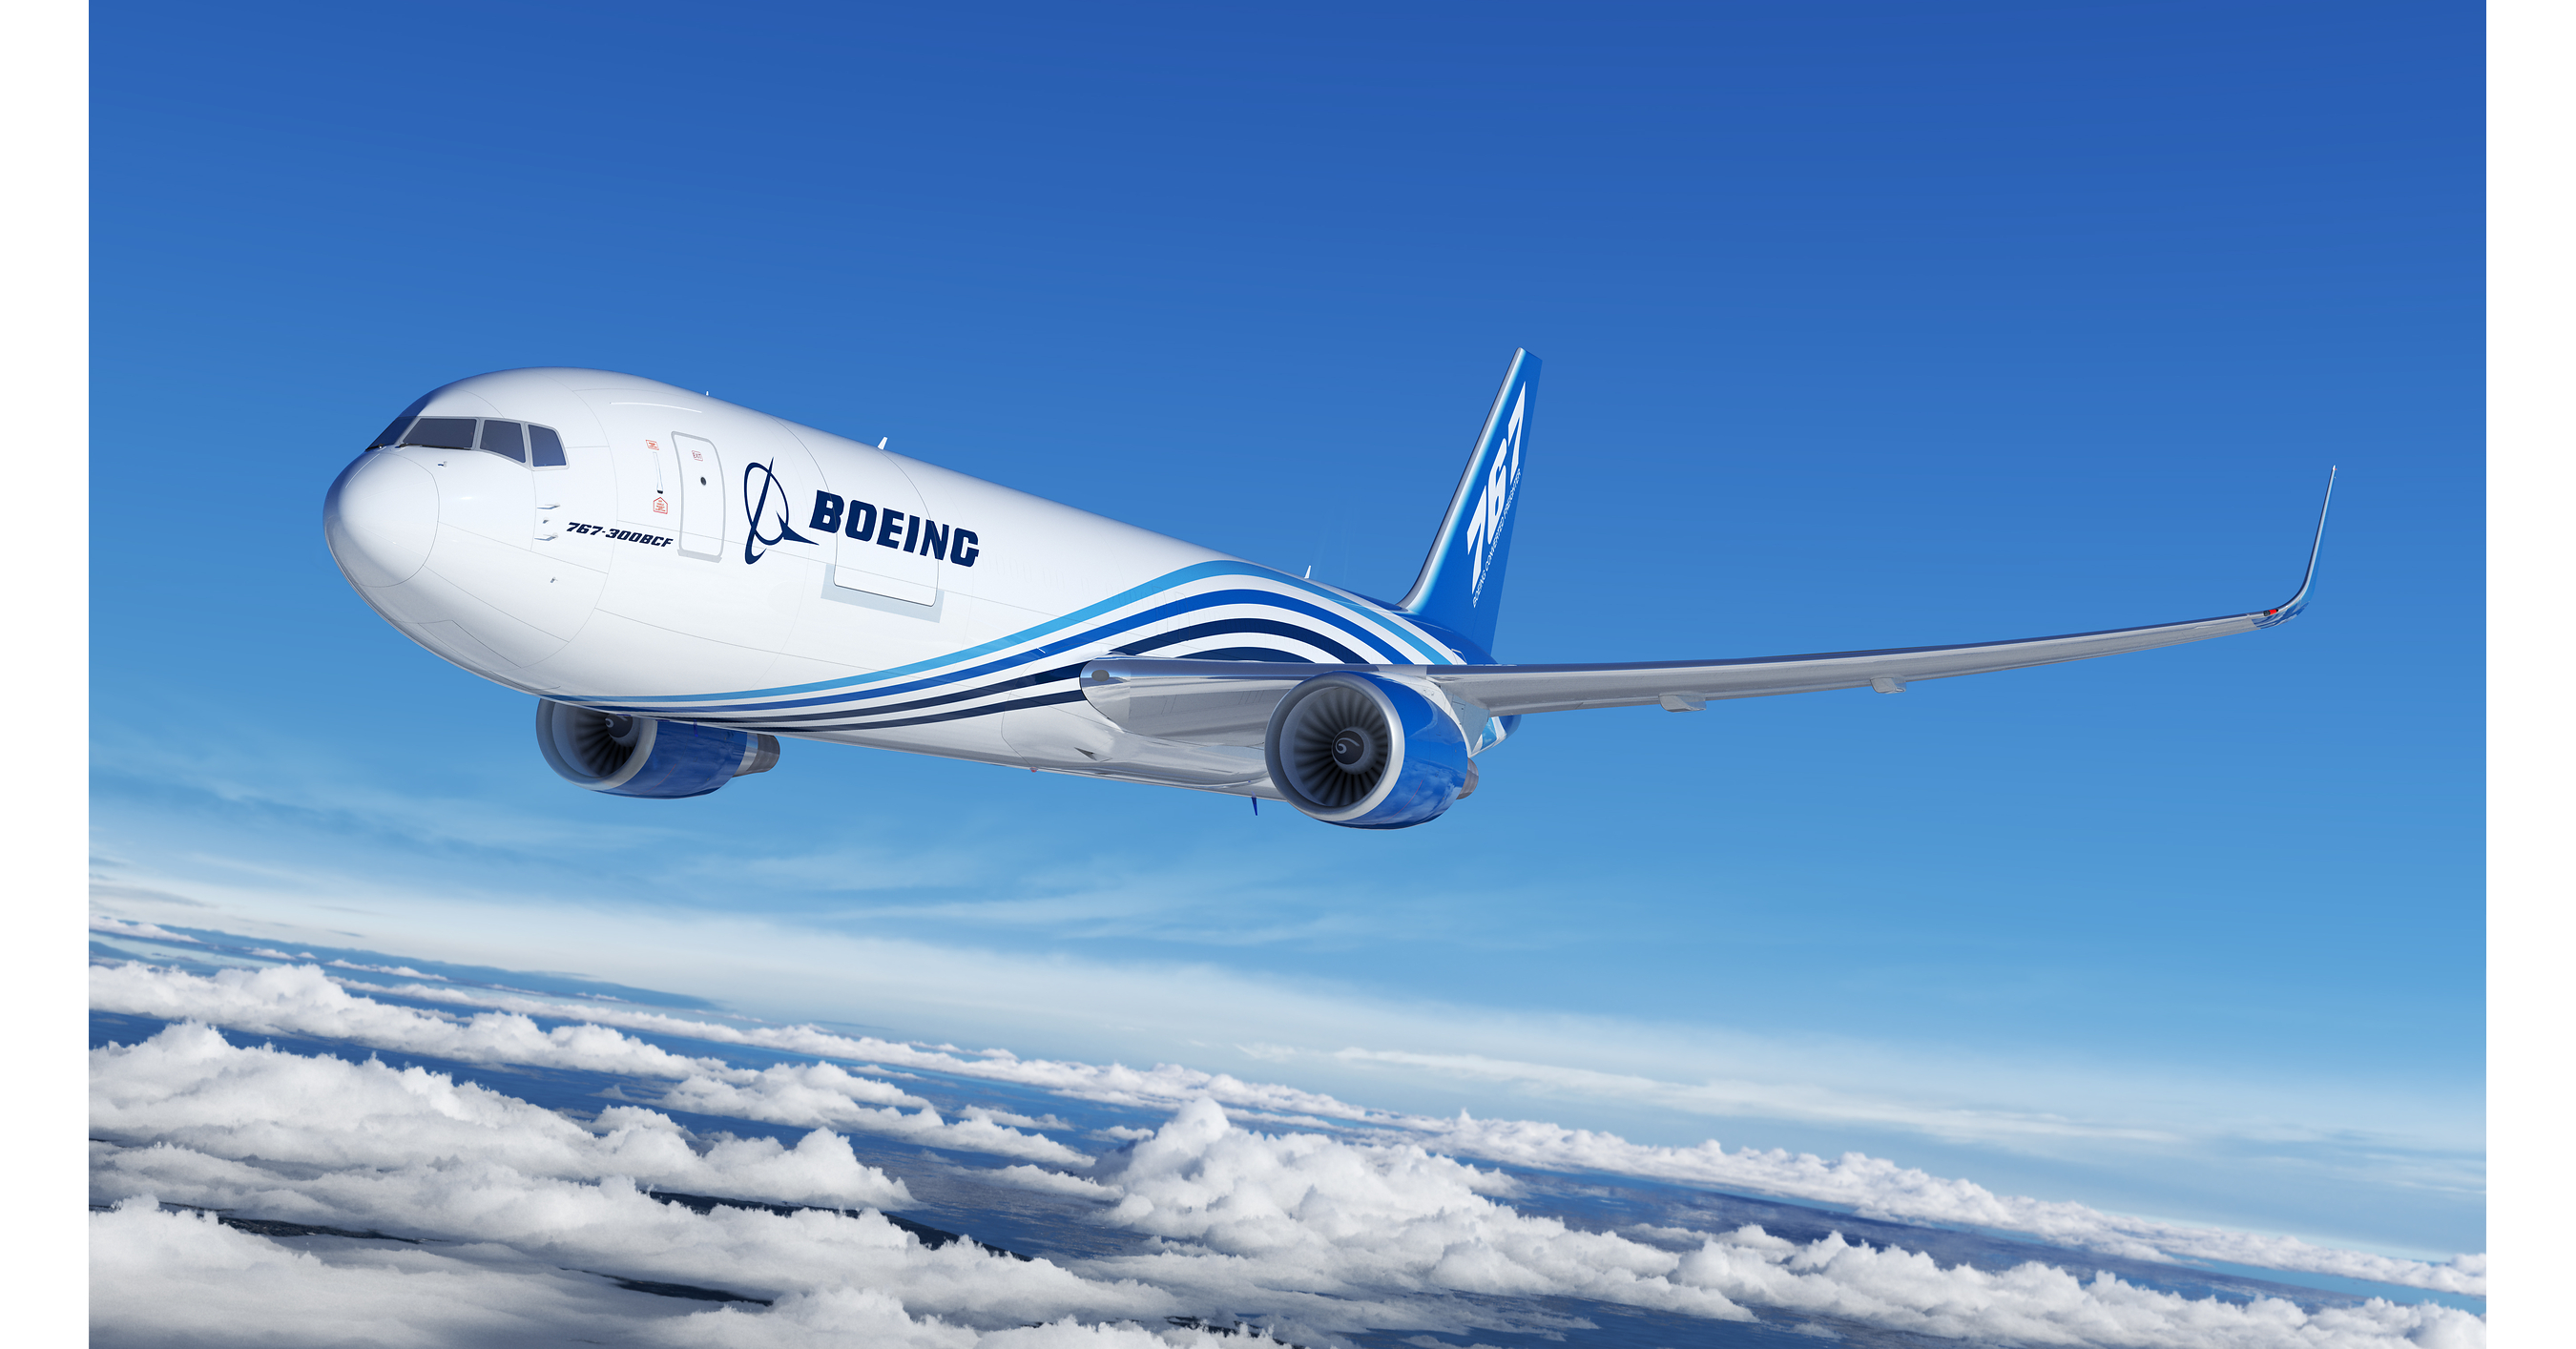
Boeing and Icelease agreed to convert one 767-300 into a Boeing Converted Freighter, with options for two additional aircraft. Induction is scheduled for Q1 2027 and delivery for Q2 2027; conversion will take place at ST Engineering facilities in Singapore. The freighter has a stated 3,300-nmi range and 57-tonne payload.
Analysis
The investable read-through is operational, not a material change to Boeing’s earnings trajectory: a single firm conversion plus two options is too small to support a company-level estimate revision without contract value, conversion economics, or evidence of a broader order cadence. The more useful signal is that lessors are still willing to commit capital to midlife freighter conversions, which supports utilization of Boeing’s conversion program and ST Engineering’s conversion capacity. If orders broaden, conversion slots and qualified labor—not aircraft demand alone—could become the bottleneck, shifting bargaining power toward conversion providers and extending lead times.
For the wider cargo market, a handful of converted 767s is unlikely to move freight rates or capacity materially. Over 6–18 months, however, sustained conversion activity could keep older widebody freighters competitive and weigh on residual values or utilization for less efficient aircraft. Near-term market impact should be negligible; the more relevant 1–3 month catalysts are additional firm conversions, option exercises, and evidence of slot utilization. The contrarian point is that an upbeat company announcement can be mistaken for a demand inflection: options are not firm orders, and a customer-specific commitment does not establish industry-wide economics. Reassess if Boeing reports a meaningful increase in conversion orders/backlog or demonstrates improved services economics; falsify the positive read-through if options lapse or conversion activity and delivery schedules weaken. Verify contract value, feedstock availability, and slot-level margins before assigning financial materiality.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No standalone BA trade: treat this as a small positive signal for the commercial-services franchise, not a basis for changing consolidated earnings or valuation assumptions.
- Add Boeing conversion orders, firm-versus-option mix, backlog, and delivery timing to the next 1–3 month monitoring list; look for repeated commitments rather than extrapolating from this customer agreement.
- Track ST Engineering’s conversion workload and capacity commentary as a potential second-order beneficiary; do not infer margin upside without evidence on utilization, pricing, and contract economics.
- Watch for incremental converted widebody supply over 6–18 months as a modest headwind to older freighter residual values and utilization; this single agreement is not sufficient to express that view through a sector position.
More News
- Ryanair warns that high fuel costs will likely mean more expensive flights and frozen staff pay
- We're buying the dip in a stock after an expectations reset
- How Trump’s trade policy is handing Asia to Beijing
- CrowdStrike lands an upgrade, and Jim Cramer's advice on Apple ahead of earnings
- Explosions hit Iran’s Qeshm Island as US media report US strikes in Hormuz
- Marvell to buy Lumentum in $115 billion deal in AI data-center bet