
The Final Countdown: More Value for G1X Series Backers
Source: PR Newswire
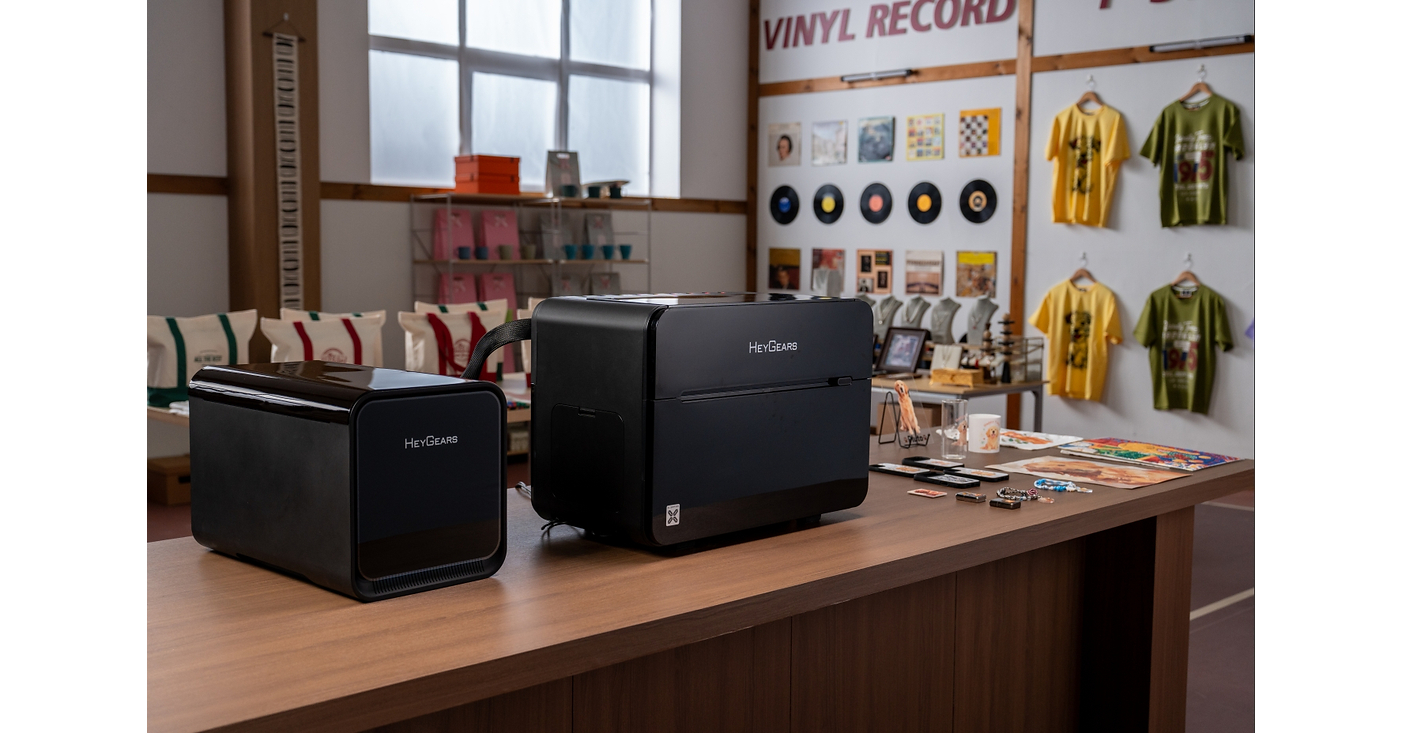
HeyGears’ G1X Series 3D/UV printer campaign has surpassed $15M on Kickstarter, offering backers limited-time $500+ cashback. Pricing after cashback is $2,799 (UV), $2,849 (Fabric), and $3,099 (Full-Color 3D), with super early-bird savings of up to 44% (as much as $1,700 off MSRP). The company cites multi-material capability and anti-clogging printhead design, alongside $10M and $15M stretch-goal rewards for eligible backers.
Analysis
This reads more like a validation event for a niche creator economy than a true incremental earnings catalyst. Crowdfunding traction can support sentiment, but it does not answer the harder questions that matter for public-market valuation: gross margin after warranty/service, refund rates after shipment, and whether consumables actually become recurring revenue or just one-time attach. In hardware like this, the financial outcome is usually determined by failure rates and support intensity, not launch-day enthusiasm.
The real second-order effect is competitive, not company-specific. By bundling UV, DTG/DTF, and desktop 3D into one box, the product compresses multiple low-end workflows into a single platform, which can pressure smaller niche vendors and channel resellers that depend on selling separate point solutions. But the same bundling also raises operational complexity; if clogging, calibration, or support issues emerge, the business can quickly shift from scalable software-like economics to a cash-consuming service model.
Near term, I would expect little durable read-through to public equities unless there is evidence of meaningful order conversion beyond backers. Over 1-3 months, the key catalyst is fulfillment quality: shipment delays, return volumes, and post-delivery reviews will matter far more than headline dollars raised. Over 6-18 months, the thesis only becomes investable if the consumables ecosystem proves sticky; otherwise this is a one-cycle launch, not a platform annuity.
Contrarian view: the market may be overestimating how much this changes the competitive landscape. Crowdfunding success often front-loads demand from enthusiasts who are price-insensitive and highly forgiving; that is a weak proxy for broad enterprise adoption. If anything, the most valuable signal may be that the attached printhead and consumables model remains fragile under real-world use, which would cap long-term margin quality.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate position in WWRL: treat this as a watch item until post-fulfillment data confirms low return rates, stable gross margin, and repeat consumables demand over the next 1-3 months.
- Fade any sympathy rally in legacy desktop 3D-printing names such as DDD or SSYS over the next 1-2 weeks; this is niche creator demand, not evidence of broad sector reacceleration. Use small size or call spreads if shorting is crowded; thesis breaks if either company posts a material order-book inflection.
- Monitor Epson supply-chain exposure over 1-3 months; if printhead volumes and pricing power appear to benefit from higher desktop OEM adoption, look for a small long in 6724.T only on verified channel checks, not on crowdfunding headlines alone.
- Set an alert on campaign-to-shipment conversion metrics and refund/cancellation rates; if cancellations exceed ~10%-15% of backers or support complaints spike after initial deliveries, the stock/sector read-through turns negative and any bullish thesis should be abandoned.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance