
Chemring shares jump 4% after Roke lands $170 million US defence deal
Source: proactiveinvestors.com
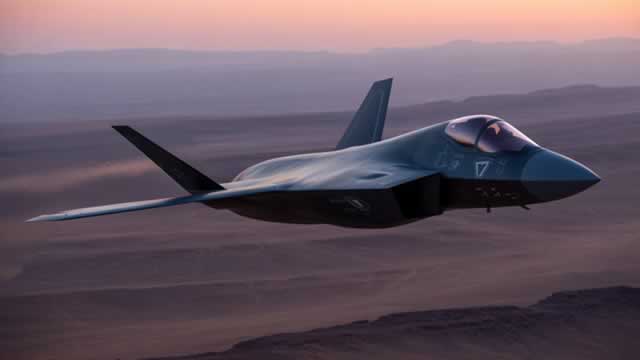
Chemring shares rose as much as 4% to 521p after subsidiary Roke signed a five-year strategic supply agreement with a major US defence contractor worth at least $170 million. The agreement covers Roke's Nav-Sync Miniature Radar Altimeter, with the relationship expected to continue beyond the initial term to at least 2035.
Analysis
The agreement improves visibility for Roke’s niche sensor business, but the investment case turns on conversion into profitable deliveries—not the headline contract value. The five-year total should not be treated as evenly timed revenue: delivery phasing, pricing, production capacity and Roke’s share of program economics are not disclosed. Nor can we judge group-level materiality without comparing expected revenue and contribution with Chemring’s existing base.
Near term, the share-price reaction may have captured much of the readily observable news. Over the next 1–3 months, the key catalysts are evidence of production ramp, order phasing and any update to group guidance. Over 6–18 months, repeat orders and successful integration into the customer’s platform could make the relationship strategically stickier; conversely, a single-program dependency or delayed platform deployment would concentrate execution risk. The stated expectation of a relationship beyond the initial term is not equivalent to contracted revenue through 2035.
Contrarian read: the market may be treating a long-duration award as near-term earnings, while underappreciating the potential value of qualification and follow-on demand if the sensor becomes embedded in a US defense program. Without margin, delivery and valuation data, the balance does not support chasing the initial move.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Do not chase the post-announcement gap. Consider CHG on a pullback only if subsequent disclosures confirm delivery phasing and incremental earnings potential; the current facts alone do not establish an attractive entry valuation.
- Set an alert for Chemring’s next results or guidance update: verify expected annual revenue contribution, gross-profit or operating-profit impact, production capacity requirements, and whether the award is included in order intake.
- Falsify the positive thesis if delivery milestones slip, the customer delays its platform program, or Chemring’s guidance/order conversion fails to reflect the award. Treat continued relationship expectations beyond the initial term as upside optionality, not base-case contracted sales.
- Monitor whether follow-on awards or customer/program concentration disclosures emerge. Until then, avoid sizing the contract as diversified, recurring group revenue.
More News
- Chemring rises on $170 million U.S. radar altimeter supply deal
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- Elon Musk says Trump is 'ultimately' responsible for any curbs on Ukraine's Starshield systems
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
- Why is Rocket Lab stock tumbling today?