
Un sur trois : Alors que l'Europe s'électrifie, VinFast construit pour l'avenir
Source: PR Newswire
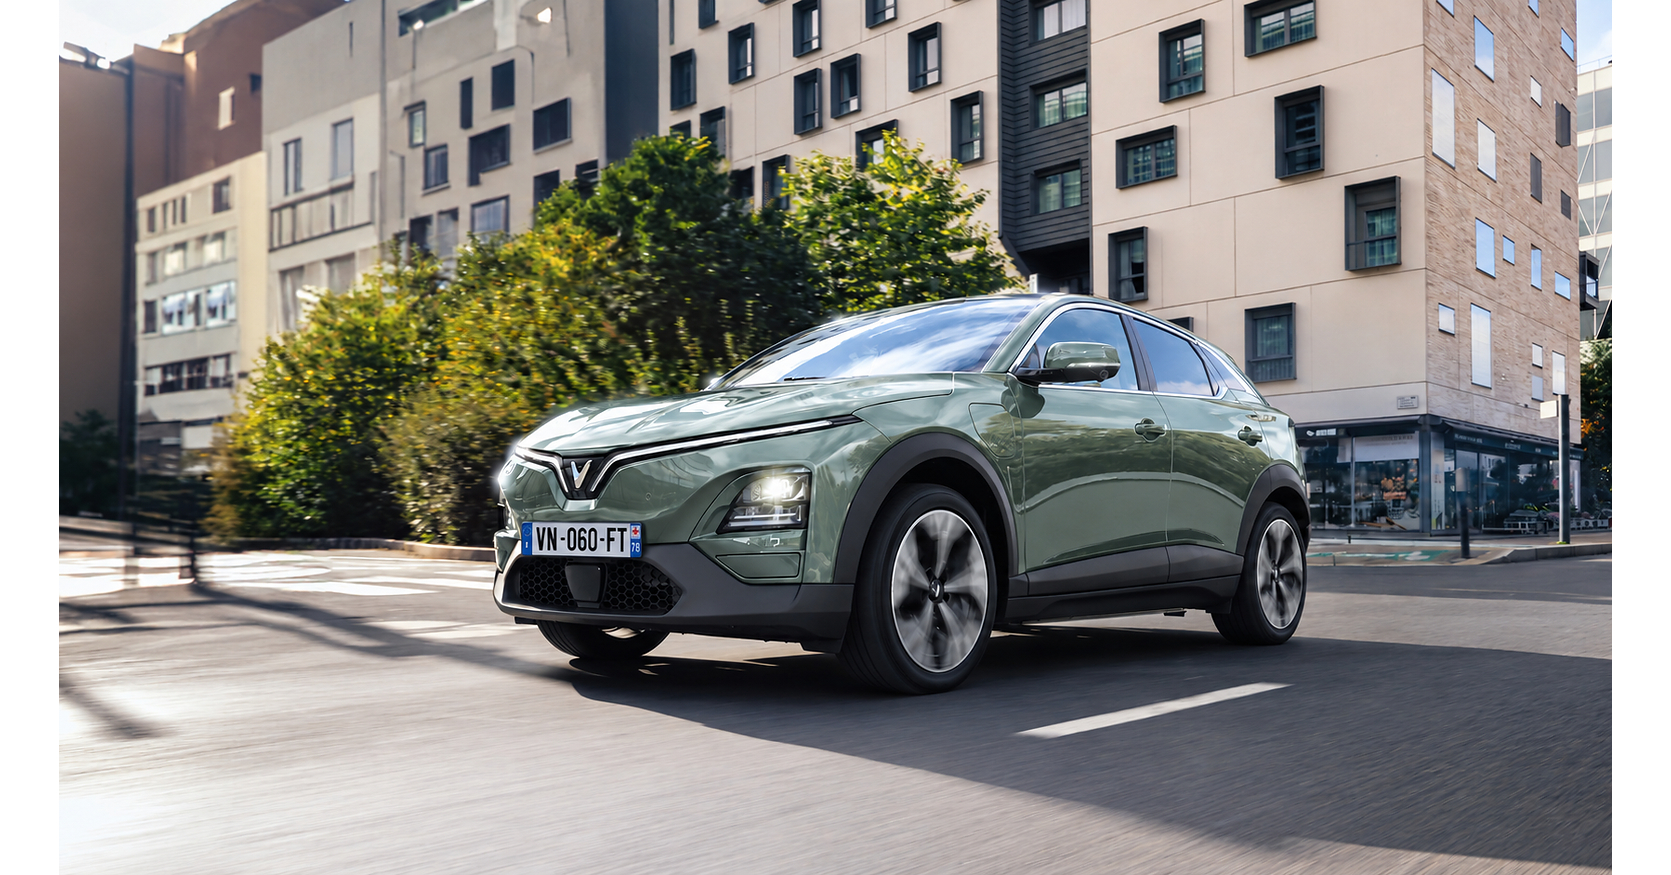
European battery-electric vehicle registrations reached 202,833 in August across 16 key markets, up 54.2% year over year and representing a 30.5% share of new-car sales. France and Germany posted EV shares of 38.3% and 32.5%, respectively, while EU rules require 90% of new urban buses to be zero-emission by 2030 and 100% by 2035. VinFast is positioning its VF 6 compact SUV and certified EB 12 electric bus for this expansion, supported by a local dealer and service-partner network.
Analysis
The strategic value of Europe for VFS is less near-term volume than external validation of its residual-value, warranty, and service proposition. A partner-led distribution model lowers fixed-cost intensity versus a direct retail rollout, but it also cedes gross margin and customer data; dealer economics will determine whether the network expands beyond a symbolic footprint. The key underwriting question is not certification or announced partnerships, but whether European registrations convert into repeatable dealer orders without incremental discounting or unusually high warranty reserves.
Competitive pressure is likely to prevent a material near-term pricing premium. BYD, SAIC/MG, Stellantis and Renault have broader local distribution, financing and parts infrastructure, while Tesla can respond with price cuts; VFS therefore risks using affordability to buy volume at negative contribution margins. The bus initiative has potentially better strategic economics because fleet tenders can create multi-year service revenue and improve factory utilization, but procurement cycles are typically 6-18 months and favor bidders with proven uptime, financing capacity and local maintenance guarantees.
For the next 1-3 months, the relevant catalyst is independently reported European registration data, dealer additions with disclosed minimum purchase commitments, and evidence that incentives are not masking transaction-price weakness. Over 6-18 months, a credible European foothold could reduce the perceived China/Vietnam-single-market discount in VFS's valuation; conversely, cash burn, inventory growth, or rising sales-and-marketing expense without a commensurate revenue ramp would reinforce dilution risk. This is a company promotional release rather than evidence of financial inflection, so the immediate signal is insufficient for a directional position.
Contrarian view: higher EV penetration does not automatically enlarge VFS's addressable profit pool. As EVs become mainstream, buyers and fleet operators increasingly prioritize financing, repair turnaround and residual values—areas where incumbents' installed infrastructure compounds. A broad European EV acceleration is more investable through scale manufacturers and charging/power-electronics suppliers than through a subscale entrant until VFS demonstrates unit economics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No new standalone VFS long on this release; place VFS on a 1-3 month watchlist for monthly EU registrations, transaction-price data and dealer order commitments. Upgrade only if volume scales while quarterly gross margin improves and operating cash burn does not accelerate.
- If VFS rallies more than 20% on European narrative momentum without corresponding registration data, consider a tactical short or bearish put spread with a 3-6 month horizon; target a reversal toward the pre-rally range. Cover if disclosed European orders, not partnerships, support a material revenue contribution or if gross-margin guidance rises.
- For exposure to European EV adoption rather than entrant-specific execution, prefer a diversified long basket in Renault (RNO.PA), Stellantis (STLAM.MI), and charging infrastructure proxy Allego (ALLG) over VFS. Reassess if subsidy rollbacks, EU tariff changes, or weaker consumer-credit conditions impair BEV demand.
- Monitor European municipal bus tenders over the next 6-18 months as the cleaner VFS proof point. A tender win is actionable only if it includes fleet size, delivery schedule, service obligations, financing terms and margin disclosure; absent those details, treat announcements as marketing rather than backlog.
More News
- Mark Ruffalo says Paramount’s $111 billion Warner Bros. deal ‘Will stifle creativity, weaken free speech, and cost people their jobs’
- States, cities sue U.S. agencies over weaker vehicle fuel economy rules
- Trump vs Europe as US presses for release of emergency diesel stocks
- Anthropic warns government attitudes may hurt customer ties, IPO prospectus shows: Reuters
- Paramount and Warner Bros Discovery to become Skydance
- FAA says Boeing 737 Max software glitch not a flight-safety issue