
ROYAL CARIBBEAN REVEALS 2028 SUMMER LINEUP OF ALASKA VACATIONS
Source: PR Newswire
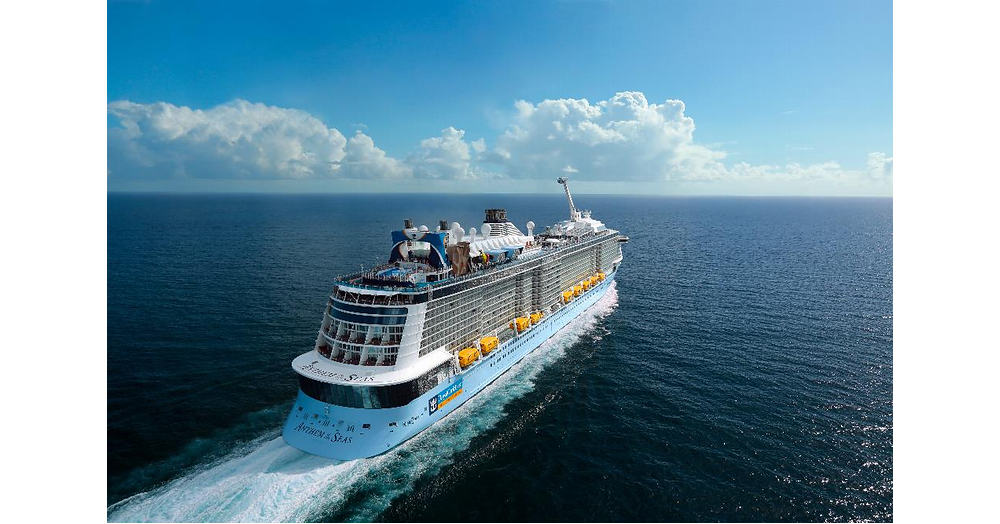
Royal Caribbean opened bookings for its 2028 Alaska program, deploying four ships—Anthem, Ovation, Serenade and Voyager of the Seas—on 7-night sailings from Seattle, Seward and Vancouver beginning in April 2028. The lineup includes 2- to 6-night Denali-focused Cruisetours and highlights the newly amplified Ovation of the Seas. The company also cited a new Alaska Railroad terminal in Seward intended to streamline guest embarkation and provide local community benefits.
Analysis
The investable signal is not incremental 2028 capacity itself, but the booking curve it creates: early deposits improve working-capital float and give RCL a multi-quarter read on premium-family demand before revenue is recognized. Alaska is a capacity-constrained, high-onboard-spend itinerary, so sustained early sell-through would support yield rather than merely occupancy; the relevant confirmation is whether net per-diem pricing holds above 2027 levels after promotional costs, not initial booking volume.
The fleet allocation also raises the opportunity cost of deploying ships away from Caribbean and European routes, where private-destination economics can produce higher onboard capture. RCL's differentiated onboard product and land extensions should skew toward higher-ticket households, but that advantage can be diluted if CCL and NCLH respond with discounting in Seattle/Vancouver or if airfares weaken the fly-cruise consumer. The ship enhancement is a modest earnings tailwind only if it earns a price premium sufficient to clear drydock capex and lost sailing days.
Near term, this is too distant to change FY2026-27 estimates or justify chasing RCL on a press release. Over the next 1-3 months, watch disclosed advance-booking commentary, Alaska pricing versus comparable 2027 departures, and onboard-revenue guidance; these are the catalysts that could turn a low-impact itinerary announcement into evidence of durable yield. Over 6-18 months, a consumer slowdown, higher West Coast airfares, port restrictions, or adverse glacier/weather disruption would challenge the premium-demand thesis and favor lower valuation peers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade on the announcement; keep RCL as a watch-list long and require evidence that 2028 Alaska pricing is holding above 2027 comparable itineraries before adding exposure.
- If RCL reports continued net-yield growth and stable booking lead times in the next two earnings updates, initiate a 6-12 month long RCL / short CCL pair. The thesis is superior premium onboard monetization and balance-sheet flexibility; exit if RCL cuts yield guidance or the relative spread moves 15% against entry.
- Use any post-earnings pullback driven by near-term fuel or macro volatility—not weaker bookings—to accumulate RCL equity for a 12-month horizon. Risk/reward is attractive only if consensus forward EBITDA is unchanged; do not add if management cites broad promotional intensity in Alaska or Caribbean.
- Monitor NCLH and CCL Seattle/Vancouver deployment and promotional activity as a competitive alert. A material capacity increase or discount-led fare response would weaken RCL's premium-price assumption and argues for reducing any RCL overweight rather than shorting the group.
More News
- UK Prime Minister Burnham says Iran 'played a part' in British air base incident
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- Greer urges G20 to back Trump tariff agenda, takes aim at China
- Google rolls out Gemini 4 Argon, its most advanced AI model
- Micron beats on revenue and earnings as global memory shortage continues
- Goldman pushes Fed rate hike to December after cooler inflation