
Zoomin Groomin Expands Five-Star Mobile Pet Grooming Services into Northwest Idaho
Source: PRWeb
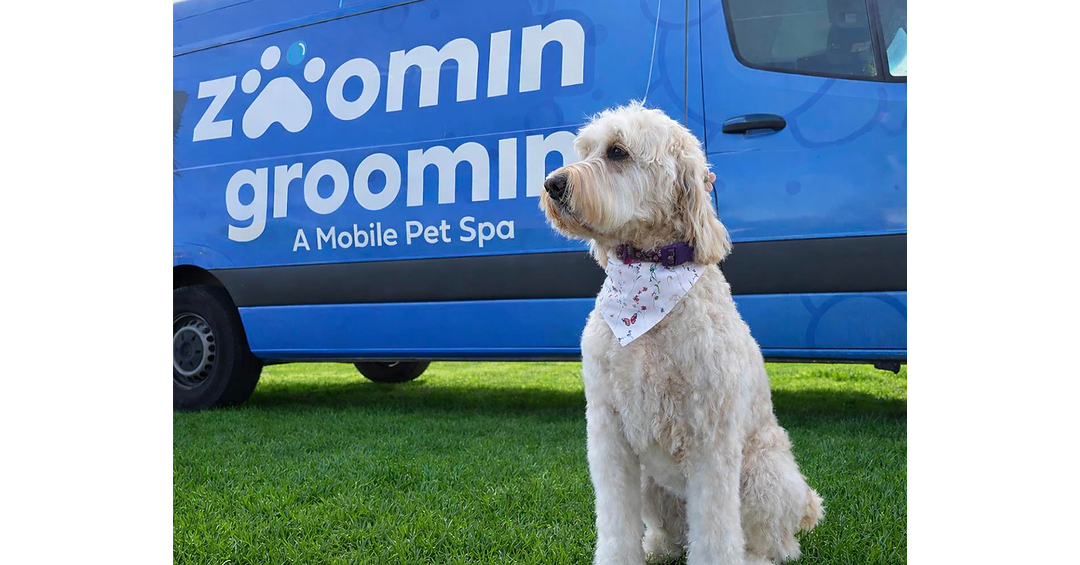
Zoomin Groomin is expanding its 100% mobile pet grooming service from Spokane into Northwest Idaho (Coeur d’Alene, Hayden, Rathdrum, and Post Falls), booking appointments now with services starting September 1. The franchise reports strong local traction in Spokane—500+ customer interactions, 72 Google reviews, and a perfect 5.0-star average—plus repeat bookings 75–80% of the time. The expansion increases fleet capacity and is framed as meeting demand for higher-quality, convenient grooming, though it’s a small company-level announcement unlikely to materially move broader markets.
Analysis
This is a micro-level unit-economics story, not a public-market catalyst. The only investable read-through is that convenience-based pet services can sustain premium pricing and repeat behavior in suburban markets, which is marginally supportive of adjacent consumer-service models; it is not large enough to move broad pet spend or change the earnings trajectory of any listed name on its own. For GOOGL, the angle is even thinner: more small businesses using local search, Maps, and reviews is directionally positive for local ad inventory, but the incremental revenue is noise.
The more meaningful second-order effect is pressure on fixed-location grooming salons and multi-service pet retailers with grooming as a traffic driver. Mobile formats attack labor utilization and occupancy, so if this model scales, the first P&L hit shows up in salon throughput and add-on attach rates rather than headline revenue. That makes WOOF the closest public-market watch item, but only as a slow-burn share-take risk over 6-18 months; there is no day-one earnings impact from one franchise expansion.
Contrarian view: the market tends to overvalue every local expansion announcement as proof of a scalable moat. The real bottleneck here is groomer supply and route density, not demand. The thesis would be falsified if repeat booking falls below roughly 60% or if management needs to discount to fill vans; that would quickly compress unit economics and turn this from a premium-convenience story into a labor-intensive delivery model.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- Do not trade GOOGL on this headline; keep the name on neutral and wait for next earnings to see whether Local Services / Maps monetization shows any measurable merchant-growth acceleration.
- Add WOOF to the watchlist as a slow-burn competitive risk to brick-and-mortar grooming, but do not initiate a short until there is evidence of salon traffic softness or margin pressure in management commentary over the next 1-2 quarters.
- If we want exposure to the broader convenience-services theme, express it only after confirming industry data; otherwise stay flat because the risk/reward here is too small for a standalone position.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Faraday Copper completes acquisition of BHP’s San Manuel project
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- Ukraine to resume strikes on Russian refineries, shattering hopes of an 'energy ceasefire'