
Micron's Q4 2026 Period Will Be Another Record Quarter
Source: seekingalpha.com
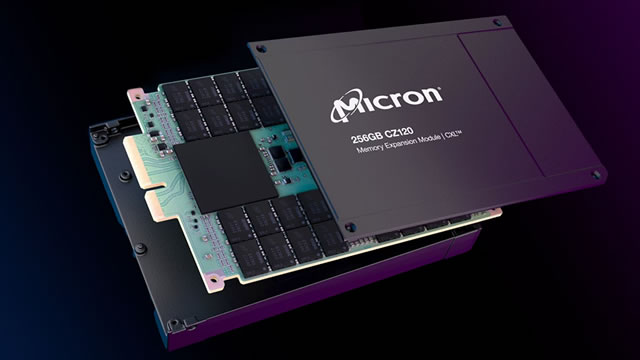
Micron is set to deliver record fiscal 4Q26 results, supported by robust DRAM demand and AI tailwinds. HBM/LPDDR innovation is backing data-center growth, while HBM supply constraints are sustaining higher memory pricing and long-term contracts booked through 2028. The view is that MU is a long-term buy despite cyclical risk and possible future supply/demand imbalances from new fab buildouts.
Analysis
MU’s upside is less about a single strong quarter and more about pricing power migrating from cyclical to semi-structural as AI memory becomes a bottleneck input, not a commodity. The first-order winner is MU’s equity, but the second-order winners are its debt holders and any suppliers tied to high-value HBM packaging and test equipment; tighter visibility and longer contracts should support lower credit spreads and better capital allocation discipline.
The hidden loser set is the AI hardware chain that cannot pass through memory inflation fast enough: server OEMs, ODMs, and some hyperscalers face margin leakage if HBM/LPDDR stays tight into the next budget cycle. That can show up before revenue cracks, via slower deployment cadence or lower incremental returns on AI capex. If memory costs rise while compute pricing commoditizes, the market may start penalizing AI infrastructure names with the least pricing power.
The main risk is classic memory mean reversion, but the timing matters: near term the stock can keep working on guide upgrades; over 6-18 months, new capacity from MU and rivals is the real falsifier. Watch for any sign that capex growth outpaces contract demand, or that lead times and spot pricing begin normalizing faster than expected. If that happens, the market will likely compress MU’s multiple well before reported earnings roll over.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Buy MU on any post-print pullback or failed breakout; 3-6 month horizon, targeting continued multiple support as forward visibility improves. Stop thesis if management implies capex intensity will outrun booked demand.
- Pair trade: long MU / short HPE or DELL over the next 1-3 months if memory pricing stays elevated; thesis is margin compression at hardware assemblers before they can reprice contracts.
- Use MU as a relative value long versus SMH only if the market starts discounting AI capex digestion; otherwise avoid over-hedging and let the stock-specific contract story work.
- Set an alert for evidence of HBM spot price softening or contract tenor shortening; that would be the earliest signal the cycle is transitioning from scarcity to oversupply.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Meta's quick success with Muse puts consumers back in the driver's seat of the AI trade
- No new stock highs, no problem: Options traders bet they're coming in these names
- As Trump and Xi meet, investors play both sides of AI divide
- Why is SK Hynix stock rallying today?
- The Nasdaq Set a Record and the Dow Lost 270 Points on the Same Morning