
Vox Royalty Enters into Binding Agreement to Acquire the White Dam Gold Royalty in Australia
Source: Newswire
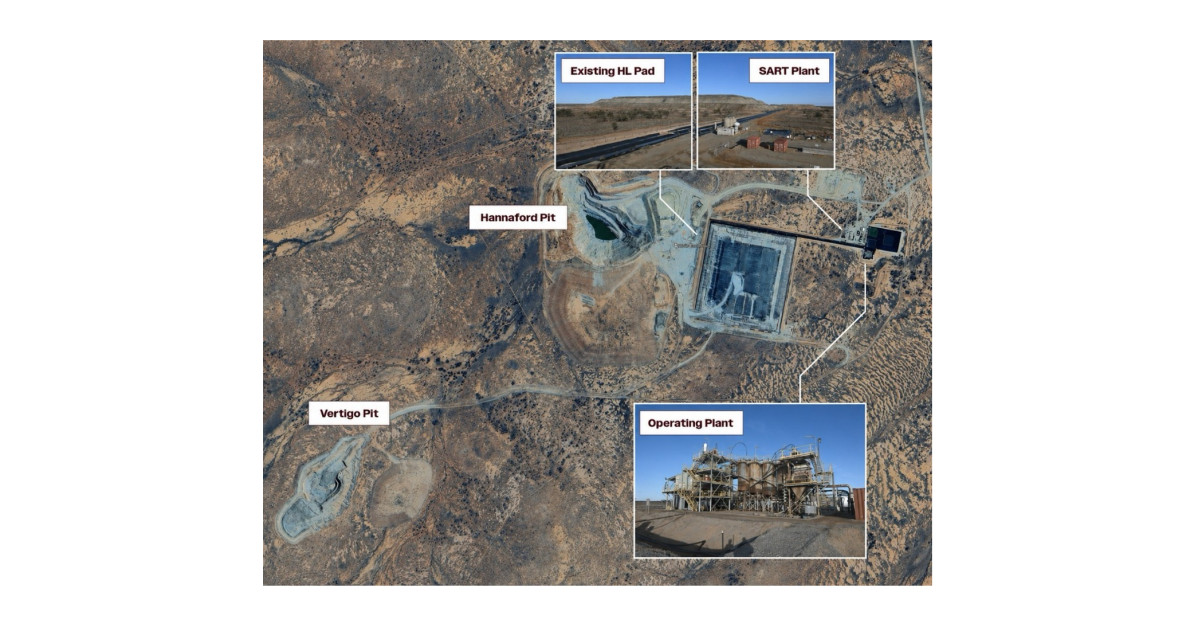
Vox Royalty will acquire a producing 2.0% net smelter return (NSR) royalty on Australia’s White Dam gold mine for A$5.0M up-front cash, subject to customary conditions precedent. White Dam is ramping after recommissioning (first gold poured in April 2026) with targeted annual production of 15,000–20,000oz and ongoing ~25,000m drilling after a July 2026 high-grade White Dam North gold/copper sulphide discovery. The royalty is uncapped and has no step-down, extending for the full life of the covered tenements, adding producing exposure plus exploration optionality for Vox at no incremental cost.
Analysis
The near-term winner is VOXR, but the bigger signal is on capital allocation: a small, uncapped NSR on a restarted asset with embedded copper exposure is the kind of low-balance-sheet, high-convexity inventory that can lift a royalty company’s quality-of-earnings narrative faster than the headline P&L impact. The market should care less about this specific check size and more about whether management can keep recycling cash into producing or near-producing assets before the next gold leg higher; that is where multiple expansion comes from.
For peers, this is mildly competitive for GROY and MALRY because it reinforces the premium on disciplined, data-driven deal sourcing rather than scale alone. The second-order effect is that as operators in Australia de-risk restarts and drill sulphide extensions, royalty owners with existing land/package coverage effectively get free exploration optionality; that favors diversified royalty portfolios over single-asset explorers and keeps dilution pressure on small miners high if they need to fund expansion. Copper optionality is the underappreciated kicker: if the sulphide zone is real, the royalty becomes less gold-beta and more multi-commodity torque.
The key risk is time. Cash flow contribution is likely months away, and the thesis reverses quickly if the restart stalls, the pad expansion slips, or drilling fails to convert geophysics into mineable tonnage. Contrarian view: the market may be overvaluing "optionality" here because royalty economics only matter after operators prove metallurgy, throughput, and funding discipline; until then, this is mostly a story stock catalyst rather than a hard earnings driver.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Long VOXR on any 1-3 day post-news weakness; treat this as a quality-screening signal, not a fundamental rerating yet. Risk/reward improves if the name sells off despite no change in operator execution, because the asset is still being de-risked.
- Pair trade: long VOXR / short GROY over the next 1-3 months as a relative-value expression on accretive royalty compounding versus more generic gold exposure. Falsify if VOXR fails to outperform after the next operating update or if the market re-prices gold royalties lower broadly.
- Set a watch alert on Broken Hill Gold's Q3 2026 drilling and ramp updates; if the sulphide discovery expands materially, VOXR gains free exploration leverage. If the next update is ambiguous or the restart slips, fade the optionality premium.
- Do not chase VOXR for a large position until completion closes and the operator shows sustained production proof. The upside is cleaner on confirmation than on press-release momentum.
More News
- Here are Friday's biggest analyst calls: Nvidia, SpaceX, Tesla, Apple, Mobileye, EchoStar, Toll Brothers & more
- Amid rising streaming subscription costs, here are 3 strategies CNBC staffers use to save
- Palantir patient data tech rejected by many NHS trusts in England
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'