
SUNDANCE MOUNTAIN RESORT ANNOUNCES 2026/2027 SEASON PASS SALES AHEAD OF MAJOR TERRAIN EXPANSION
Source: PR Newswire
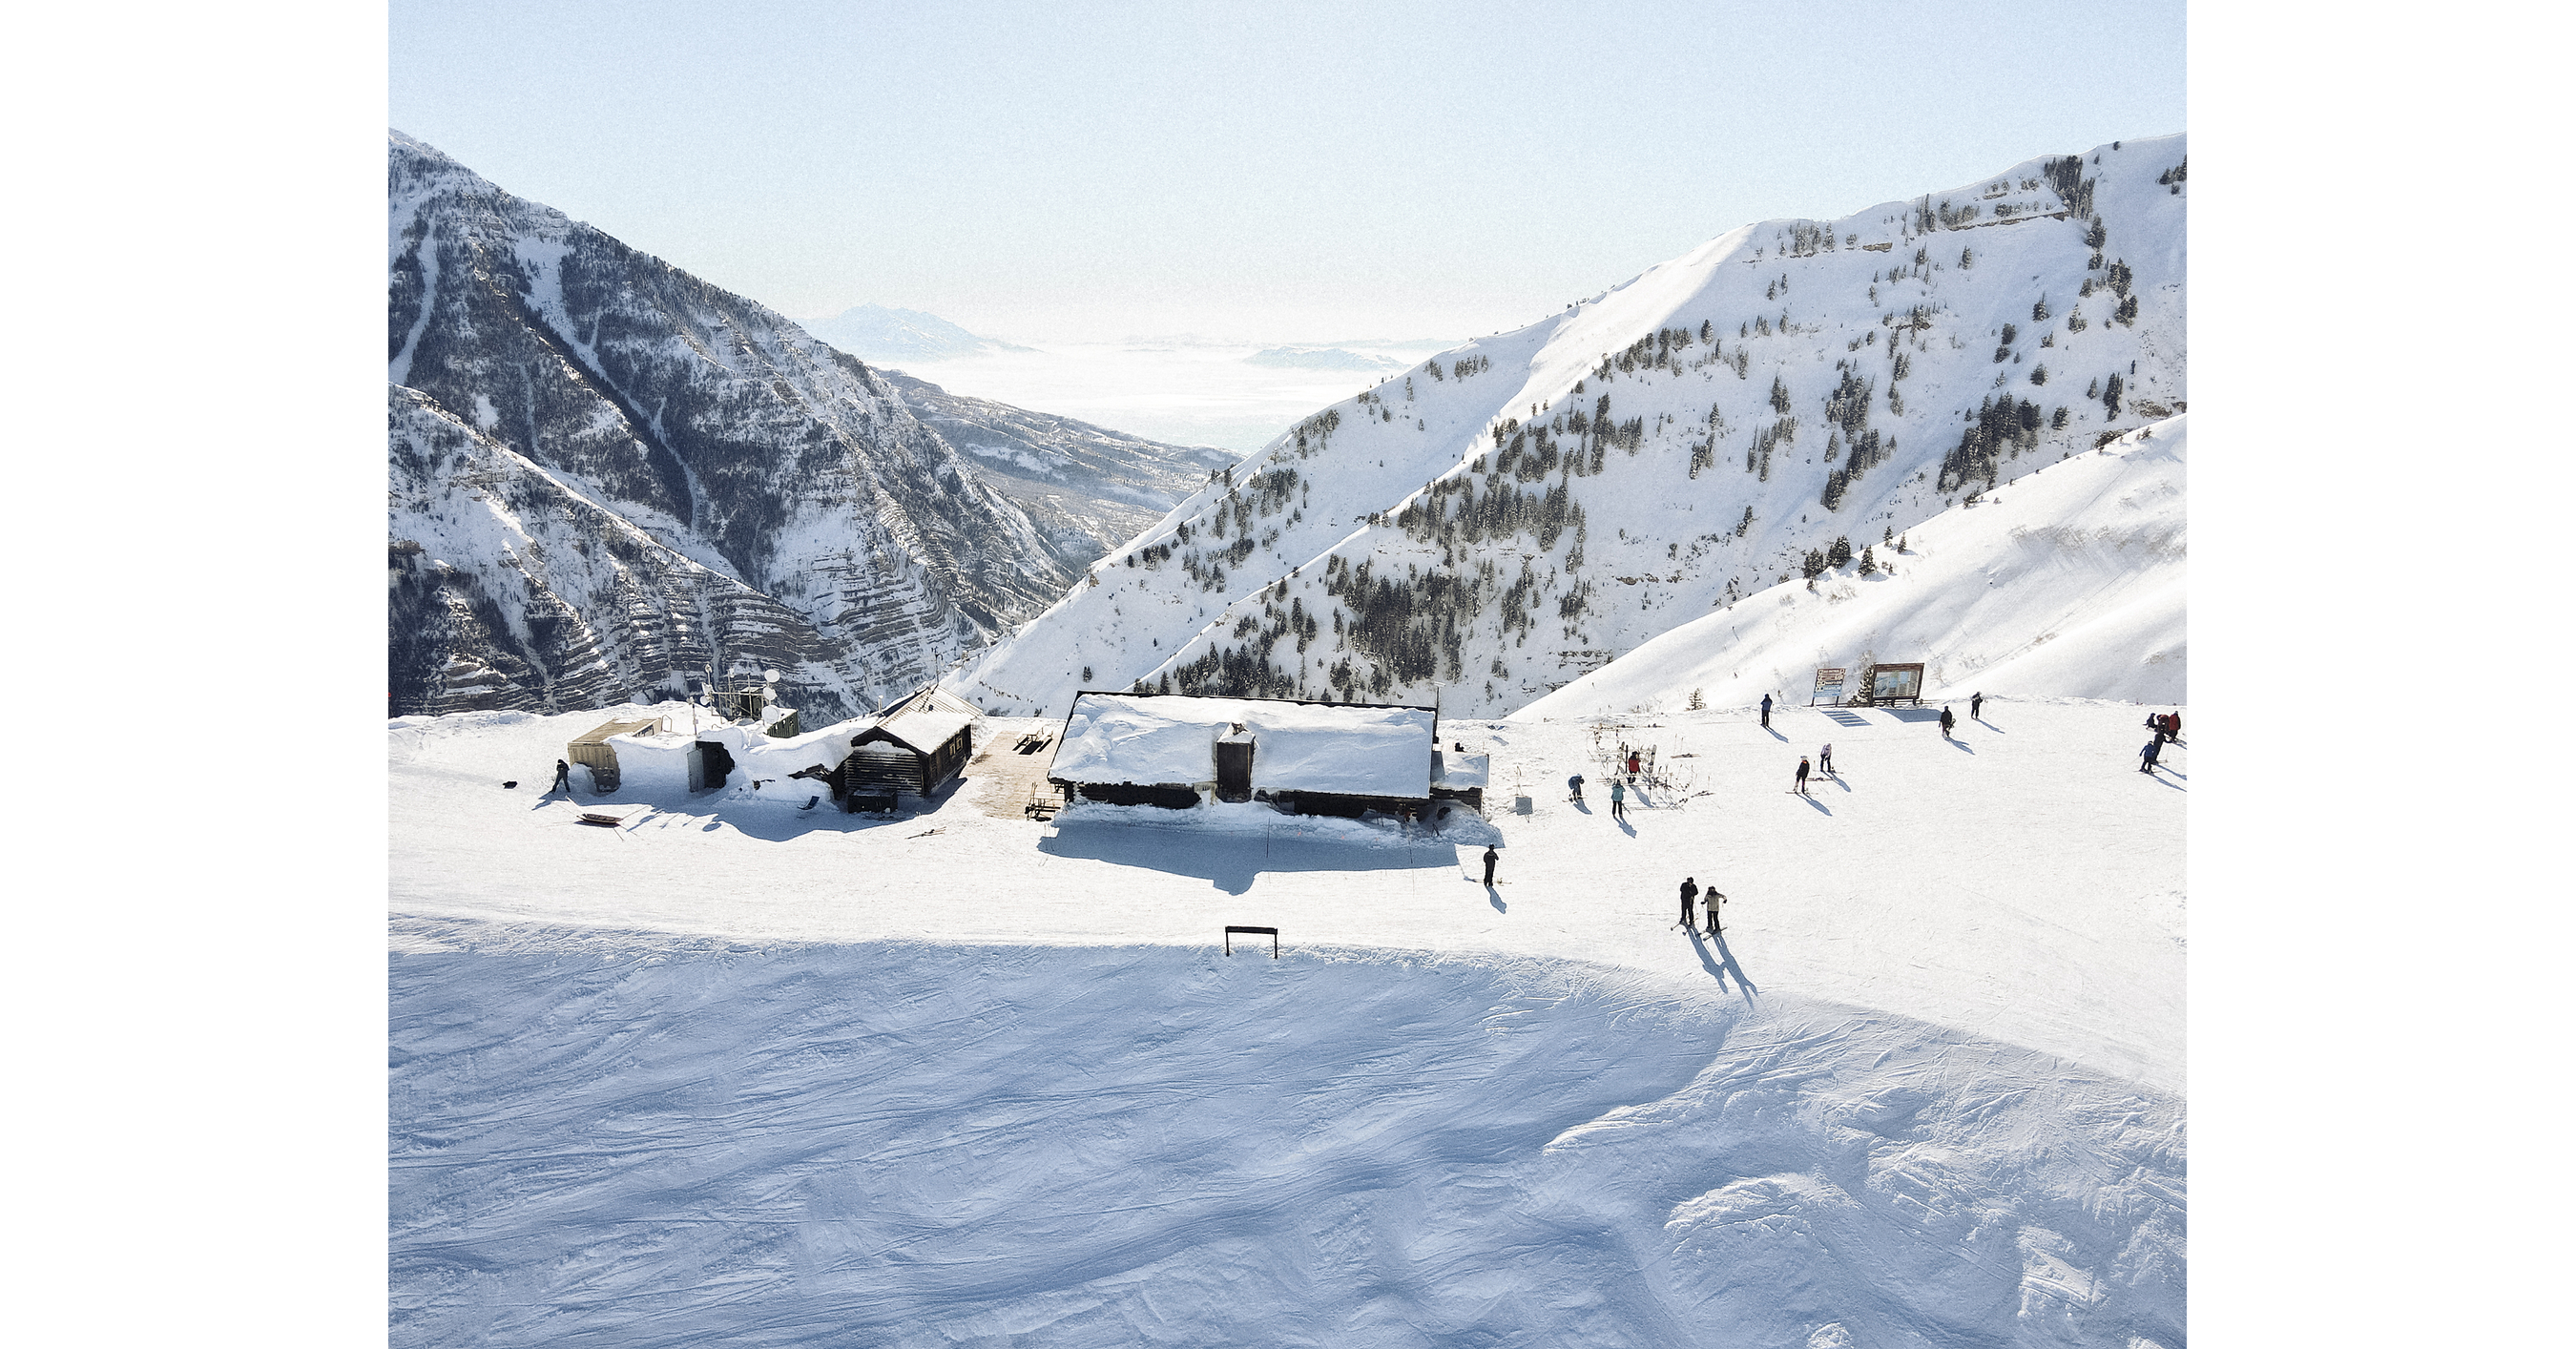
Sundance Mountain Resort opened sales for 2026/27 season passes priced from $205 for junior night skiing to $1,249 for adult VIP access, alongside discounted S-Cards. The resort will offer more than 600 skiable acres after adding over 60 acres of terrain, supported by the new Electric Horseman high-speed quad and a 1.7-mile Storyteller ridge run. The expansion enhances the guest offering but is routine promotional news with limited broader market relevance.
Analysis
This is not independently actionable public-equity news: Sundance is privately held, and the operating changes are too small to alter earnings expectations for listed destination-resort operators. The more relevant read-through is competitive: added lift capacity and terrain can improve skier dispersion, reduce peak-day friction, and support ancillary capture in lodging, food and beverage, and lessons—but the economic payoff depends on utilization rather than acreage. The broad menu of lower-frequency products also suggests an effort to monetize the local Provo/Salt Lake catchment without relying solely on destination guests.
For Vail Resorts (MTN) and Alterra-related private assets, the implication is marginally negative only in Utah regional share, particularly for premium weekend and corporate demand. Sundance's relative proximity and differentiated boutique positioning could pressure day-ticket yield at nearby resorts during normal snow years, but its limited scale makes any diversion immaterial at the consolidated-company level. POWDR-linked Snowbird and Solitude are private, eliminating a clean direct comp trade.
Near term, no listed-equity catalyst exists. Over 1-3 months, track Utah early-season snowfall, lodging occupancy, and regional airport traffic: a weak snowpack would turn incremental fixed lift and terrain operating costs into a margin headwind for all Utah resorts, while strong snow and constrained weekend capacity would validate higher ancillary spend. Over 6-18 months, sustained capital upgrades across smaller independents could incrementally weaken the network advantage embedded in MTN's Epic Pass, but one resort expansion does not change that thesis.
Contrarian view: the press-release framing likely overstates demand creation. Faster access can mostly redistribute existing skiers to less-congested terrain; unless it raises visit frequency, overnight stays, or price realization, the return is operational quality rather than material revenue growth. There is no trade absent evidence of price changes, pass-sales velocity, or lodging occupancy materially outperforming Utah peers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No immediate position: do not trade MTN or broad travel/leisure ETFs on this announcement; expected consolidated earnings sensitivity is de minimis.
- Set a winter watch alert on MTN: consider a tactical short only if Utah snowfall is below normal through January and MTN signals elevated discounting or weaker pass/lodging yield; falsify on stable season-pass sales and resilient resort EBITDA guidance.
- For an existing MTN long, monitor Utah competitor pricing and peak-period inventory through the 2026/27 booking cycle. Reduce exposure if regional day-ticket pricing or ancillary spend weakens while wage and snowmaking costs rise; retain if Epic Pass renewal and resort EBITDA guidance remain intact.
- Use ski-industry data as a macro demand read-through rather than a single-name catalyst: Salt Lake City hotel RevPAR, regional airline load factors, and Utah snow-water equivalent over the next 3-6 months will determine whether incremental resort capacity is absorbed or becomes promotional supply.
More News
- New aircraft carrier, 10,000 US troops: Is the Iran war about to escalate?
- U.S. to send third carrier group to Mideast as Trump warns of new Iran strikes
- US Adds Carrier and 10,000 Troops to Mideast
- Hackers Breached Propulsion System of US-Bound Oil Tanker
- Why Lilly and Novo are betting on amylin to power a new wave of obesity drugs after GLP-1s
- Rep. Landsman: AI Czar Wouldn’t Provide Enough Oversight