
KHLOÉ KARDASHIAN KÜNDIGT DIE AUSWEITUNG IHRES VERTRIEBS IN DIE SEPHORA-FILIALEN AN - MIT IHREM WELTWEIT ANERKANNTEN DUFT-PORTFOLIO MIT LUXUSMARKEN
Source: PR Newswire
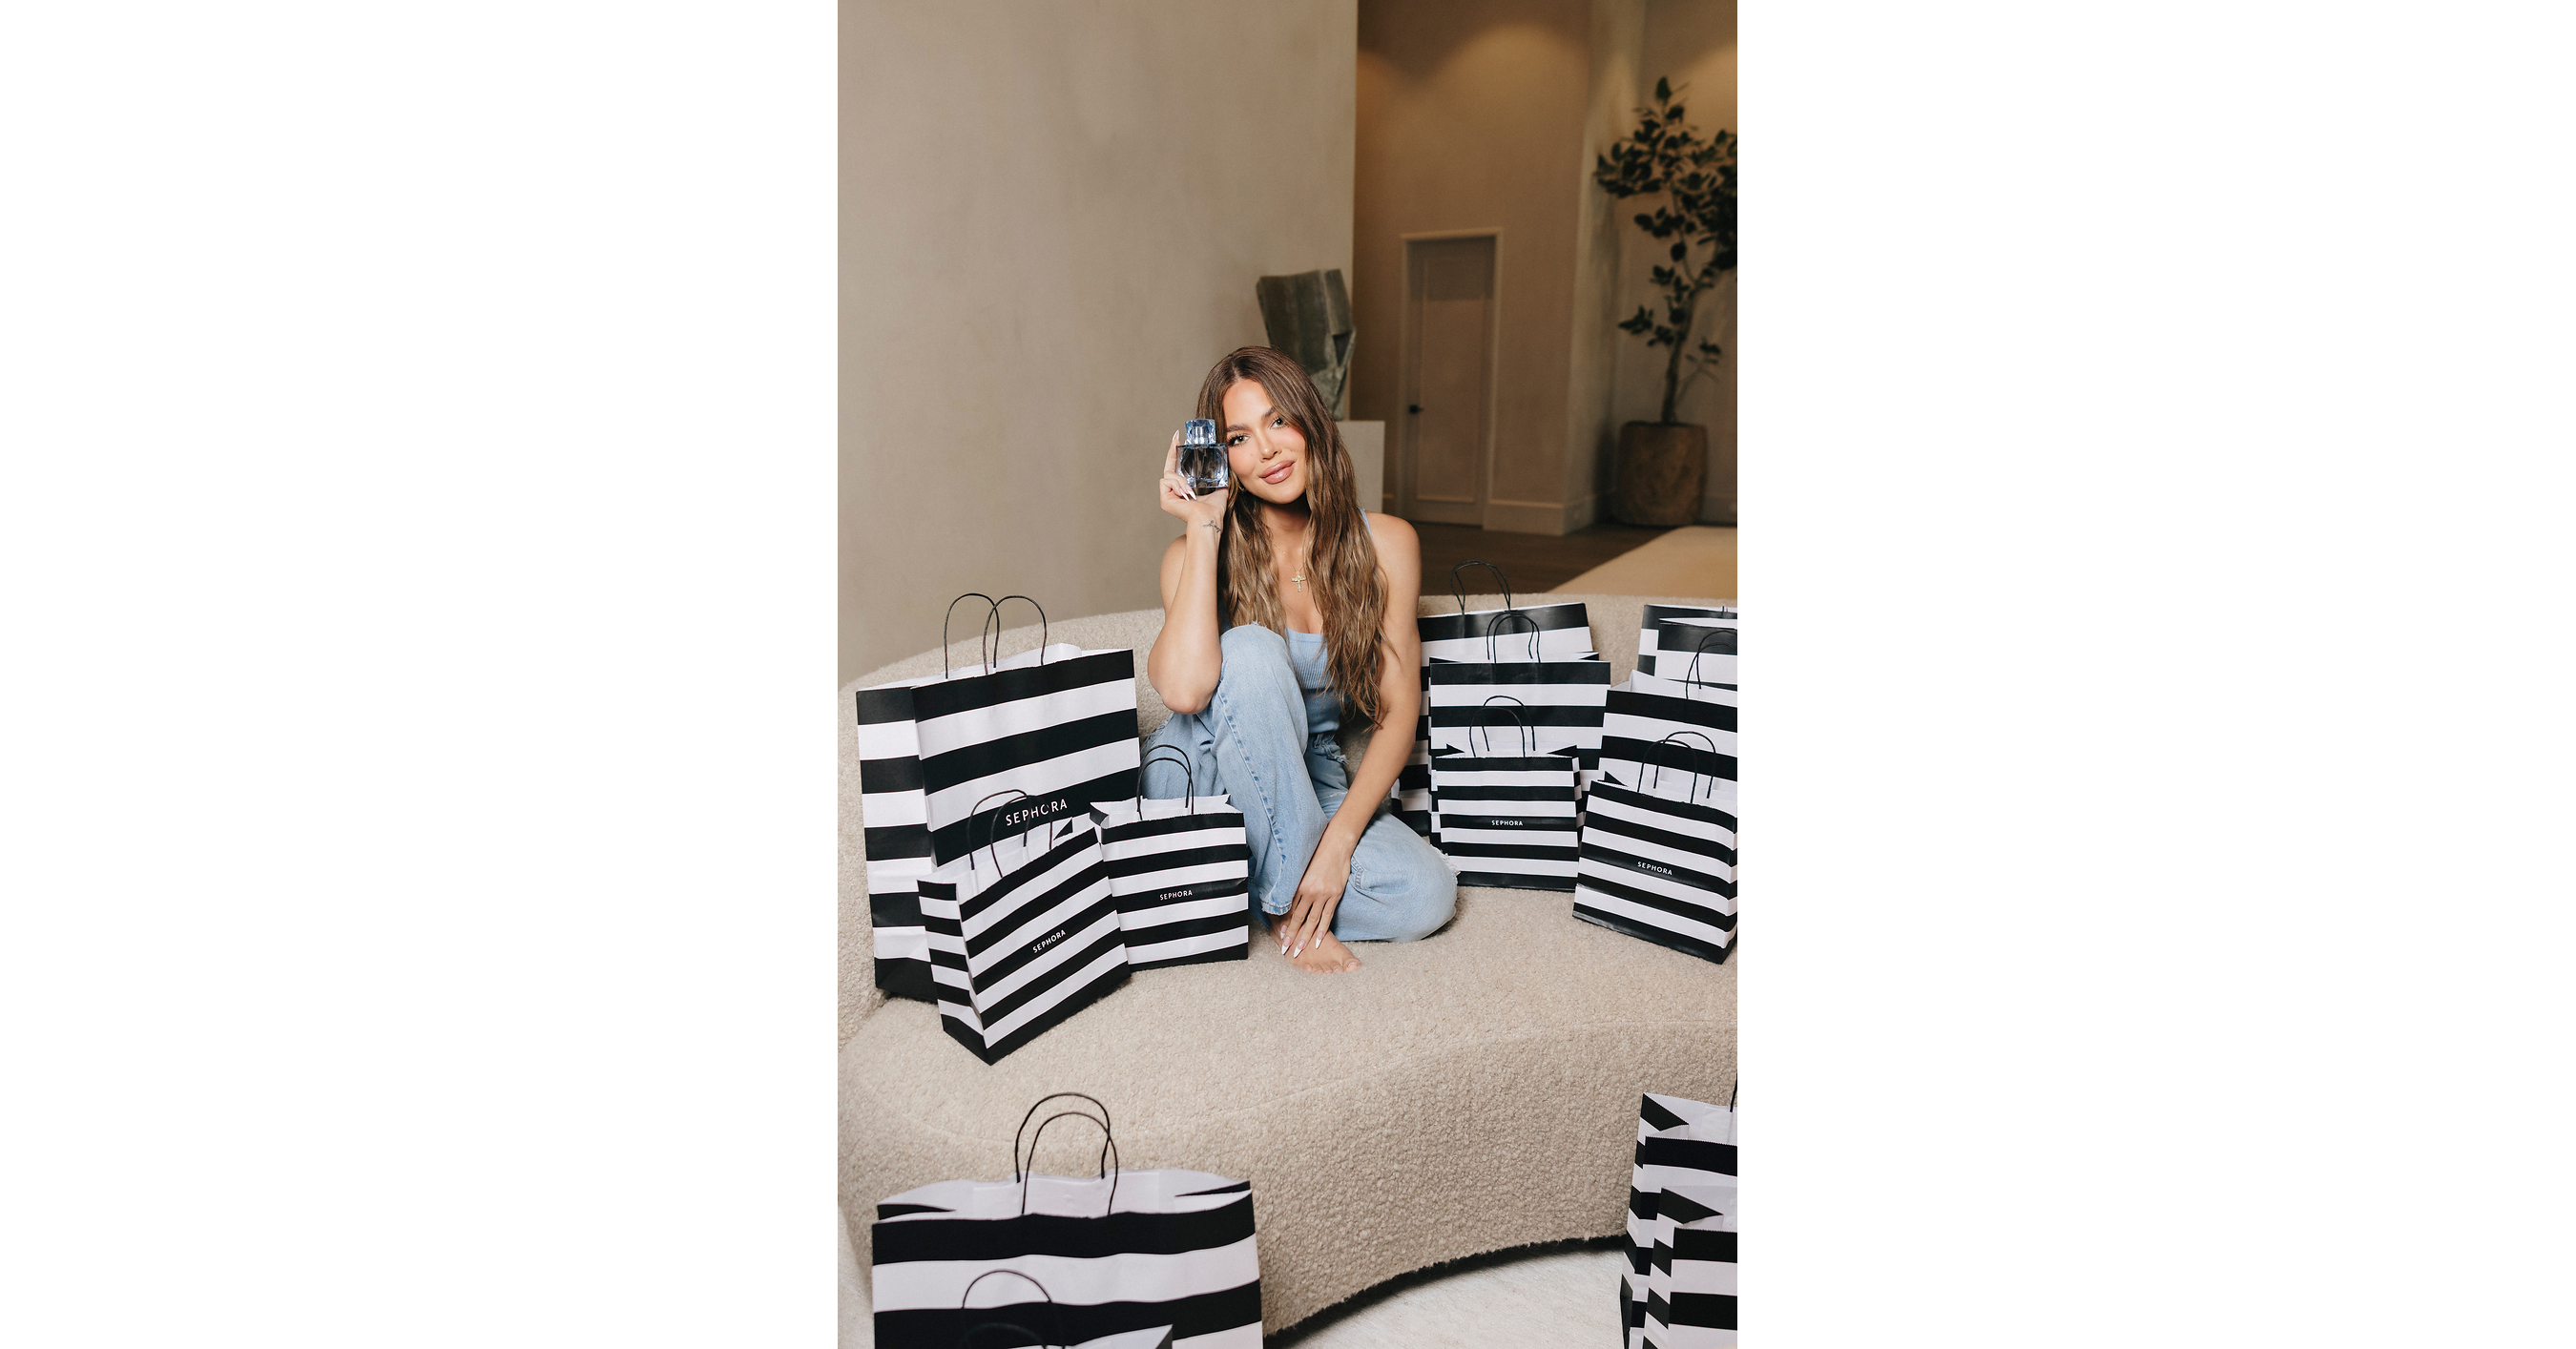
Khloé Kardashian Fragrances launched at Sephora on September 14, 2026, placing its XO Khloé, Almost Always and XO BLUE scents in 1,300 Sephora and Sephora at Kohl's stores across the U.S., with Sephora serving as the exclusive Canadian retailer. Luxe Brands is supporting the rollout with a 360-degree media campaign, including digital, social, out-of-home and Hulu's "The Kardashians" integrations. The North American Sephora partnership is positioned as a platform for future expansion into Mexico, Brazil, India and Asian beauty markets.
Analysis
This is not a GM catalyst: the Hummer fragrance license sits within a third-party brand portfolio and has no discernible path to GM revenue, margin, or valuation. The more relevant public read-through is KSS, where Sephora shop-in-shops can benefit from incremental traffic and basket attachment; however, a single celebrity fragrance launch is immaterial against Kohl's revenue base and does not alter the core merchandising, inventory, or balance-sheet debate.
The useful near-term datapoint is not launch publicity but sell-through productivity per door during the first 8-12 weeks, particularly whether the brand expands fragrance-category conversion rather than cannibalizing existing prestige labels. If Sephora's promotional investment drives repeat purchase and younger-customer traffic, KSS could gain modestly through holiday traffic and cross-shopping; if discounting is required after the initial social-media burst, it would reinforce that celebrity-led beauty demand is marketing-dependent rather than a durable category-growth signal. Sephora owner LVMH is not a clean public U.S. equity vehicle, so the announcement offers little direct investable exposure.
Consensus risk is over-attributing Sephora traffic to a Kohl's turnaround. Beauty may improve store visits, but its economic value to KSS depends on conversion into higher-margin apparel, home, and impulse purchases; isolated beauty productivity can coexist with weak overall comparable sales. No trade is warranted absent category sales, conversion, and gross-margin disclosure in KSS earnings commentary.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- No position in GM on this development; treat any market linkage through the Hummer fragrance license as noise. Reassess only if GM discloses a material licensing-revenue strategy, which is currently unsupported.
- Maintain KSS as a watch item rather than initiating a long. Monitor the next earnings release for Sephora-driven traffic, beauty comparable sales, and consolidated gross-margin progression; a long case requires evidence that beauty traffic lifts total-store conversion, not merely Sephora sales.
- For existing KSS exposure, use holiday-quarter guidance as the 1-3 month catalyst. Reduce or hedge if management cites higher beauty promotions, weaker non-beauty attachment, or incremental markdown pressure, as those outcomes would undermine the traffic-to-profit conversion thesis.
- Do not extrapolate this launch into a broad prestige-beauty long basket without independently verified sell-through data. A 6-18 month expansion thesis depends on repeat demand and international distribution economics, neither of which is disclosed by the privately held brand owner.
More News
- S&P 500 pulls within 1.2% of its all-time high even as majority of its stocks fell: Broadcom, Nvidia and other AI stocks made up the difference
- Wells Fargo raises Nucor stock price target on market share gains
- Why GM and Hilton are ditching the NYSE for Nasdaq
- PENSKE AUTOMOTIVE GROUP REPORTS QUARTERLY RESULTS
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain