
Uno su tre: mentre l'Europa passa all'elettrico, VinFast si prepara al lungo termine.
Source: PR Newswire
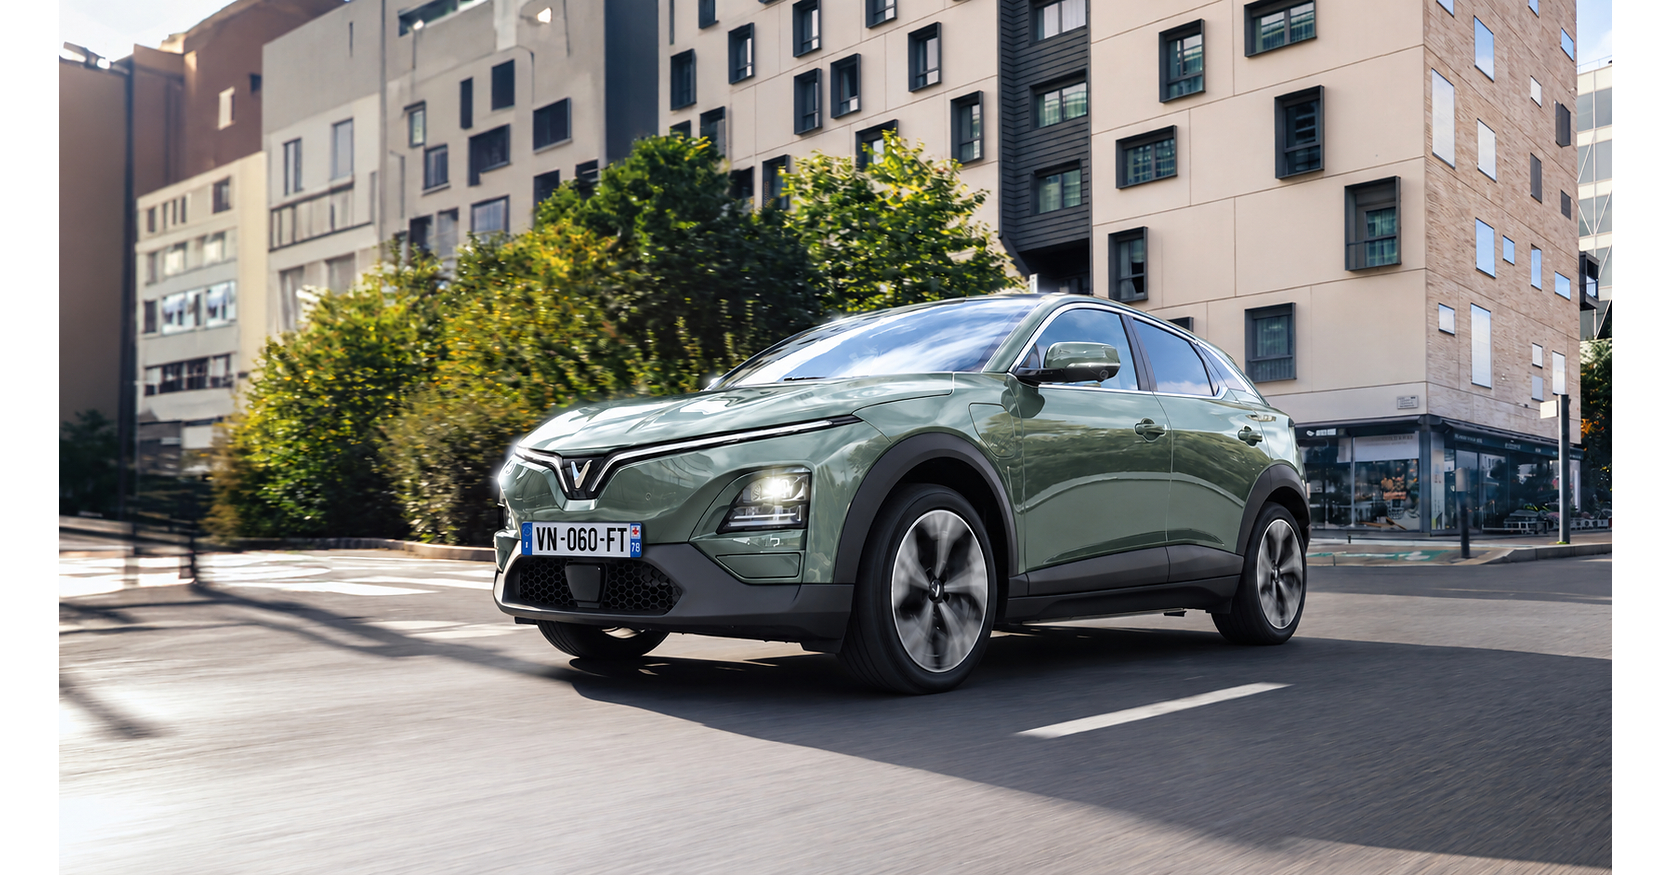
Ad agosto, i BEV hanno raggiunto il 30,5% delle nuove immatricolazioni in 16 principali mercati europei, con 202.833 veicoli registrati (+54,2% annuo), superando le precedenti stime di quota del 21-23%. Francia e Germania hanno raggiunto rispettivamente quote BEV del 38,3% e 32,5%, mentre l'UE richiede che il 90% dei nuovi autobus urbani sia a zero emissioni entro il 2030. VinFast punta a beneficiare della transizione con il SUV compatto VF 6, gli autobus elettrici EB 8 ed EB 12 e una rete locale di concessionari e assistenza; l'EB 12 ha ottenuto la certificazione europea completa.
Analysis
The relevant investable signal is not near-term passenger-vehicle share, but whether VinFast can convert European homologation and dealer-service partnerships into fleet contracts. Municipal bus procurement is lumpy, multi-year, and heavily weighted toward uptime guarantees, financing and local parts availability; certification only earns eligibility, not economic orders. A credible first contract would be disproportionately important for VFS because it can validate residual values and service capability, lowering a key barrier to retail adoption and potentially reducing sales-and-marketing intensity over 12-18 months.
Competitive pressure is likely to be greater on subscale European EV offerings than on incumbents with captive fleets. BYD, Yutong and Solaris already possess stronger procurement references, while Volvo, Daimler Truck and Traton benefit from established service footprints; VinFast may need to price aggressively or subsidize warranties to win early tenders, limiting any revenue upside to gross-profit conversion. The second-order beneficiary of accelerating electrification is charging and grid equipment—ABB, Schneider Electric and Alfen—although municipal depot build-outs typically lag vehicle awards by 6-18 months.
For VFS, the immediate news value is low: this is issuer-sponsored positioning without disclosed European orders, unit economics, dealer commitments, backlog, or service-capex requirements. The stock should be treated as an event-driven optionality vehicle rather than a clean European-EV-demand proxy, given execution risk and likely funding needs. A thesis turns credible only if management discloses binding fleet awards, delivery schedules, European gross-margin trajectory, and warranty/service provisions; absent these, stronger European BEV demand may principally accrue to scaled competitors.
Contrarian view: faster BEV penetration can intensify—not relieve—price competition as Chinese OEM capacity seeks European utilization. If VinFast responds with low prices to establish share, volume growth could coincide with deeper cash burn and multiple compression. Conversely, a contracted bus order with financed economics and a named local service partner could force a re-rating because the market currently has limited evidence that its European infrastructure can support recurring fleet revenue.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No directional VFS position on this release. Set a 1-3 month alert for disclosed European fleet tender wins, contract value, delivery timing and associated service obligations; initiate only after evidence that orders are binding rather than certification-led marketing.
- If a named municipal or operator award is announced, consider a small long VFS only after confirming contract margin, financing terms and incremental working-capital needs. Size as high-volatility event exposure; exit if management cannot show improving vehicle gross margin or cash-burn containment in the following two reporting periods.
- For a liquid structural expression over 6-18 months, favor long ABB or Schneider Electric against a basket of auto OEM exposure: depot charging, switchgear and grid upgrades capture fleet electrification with less vehicle price-war risk. Reassess if European municipal procurement funding is delayed or charging-order growth decelerates.
- Avoid treating passenger-EV penetration as sufficient evidence for VFS. Falsify any bullish thesis if European dealer/service coverage remains undisclosed, warranty provisions rise materially, or the company signals additional equity financing before fleet revenue ramps.
More News
- Mark Ruffalo says Paramount’s $111 billion Warner Bros. deal ‘Will stifle creativity, weaken free speech, and cost people their jobs’
- States, cities sue U.S. agencies over weaker vehicle fuel economy rules
- Trump vs Europe as US presses for release of emergency diesel stocks
- Anthropic warns government attitudes may hurt customer ties, IPO prospectus shows: Reuters
- Paramount and Warner Bros Discovery to become Skydance
- FAA says Boeing 737 Max software glitch not a flight-safety issue
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace
- AI Research Tools for SEDAR+, UK and ASX Filings