
CRRC présente son portefeuille de solutions éoliennes au salon WindEnergy de Hambourg, obtient des certifications clés et renforce ses partenariats internationaux
Source: PR Newswire
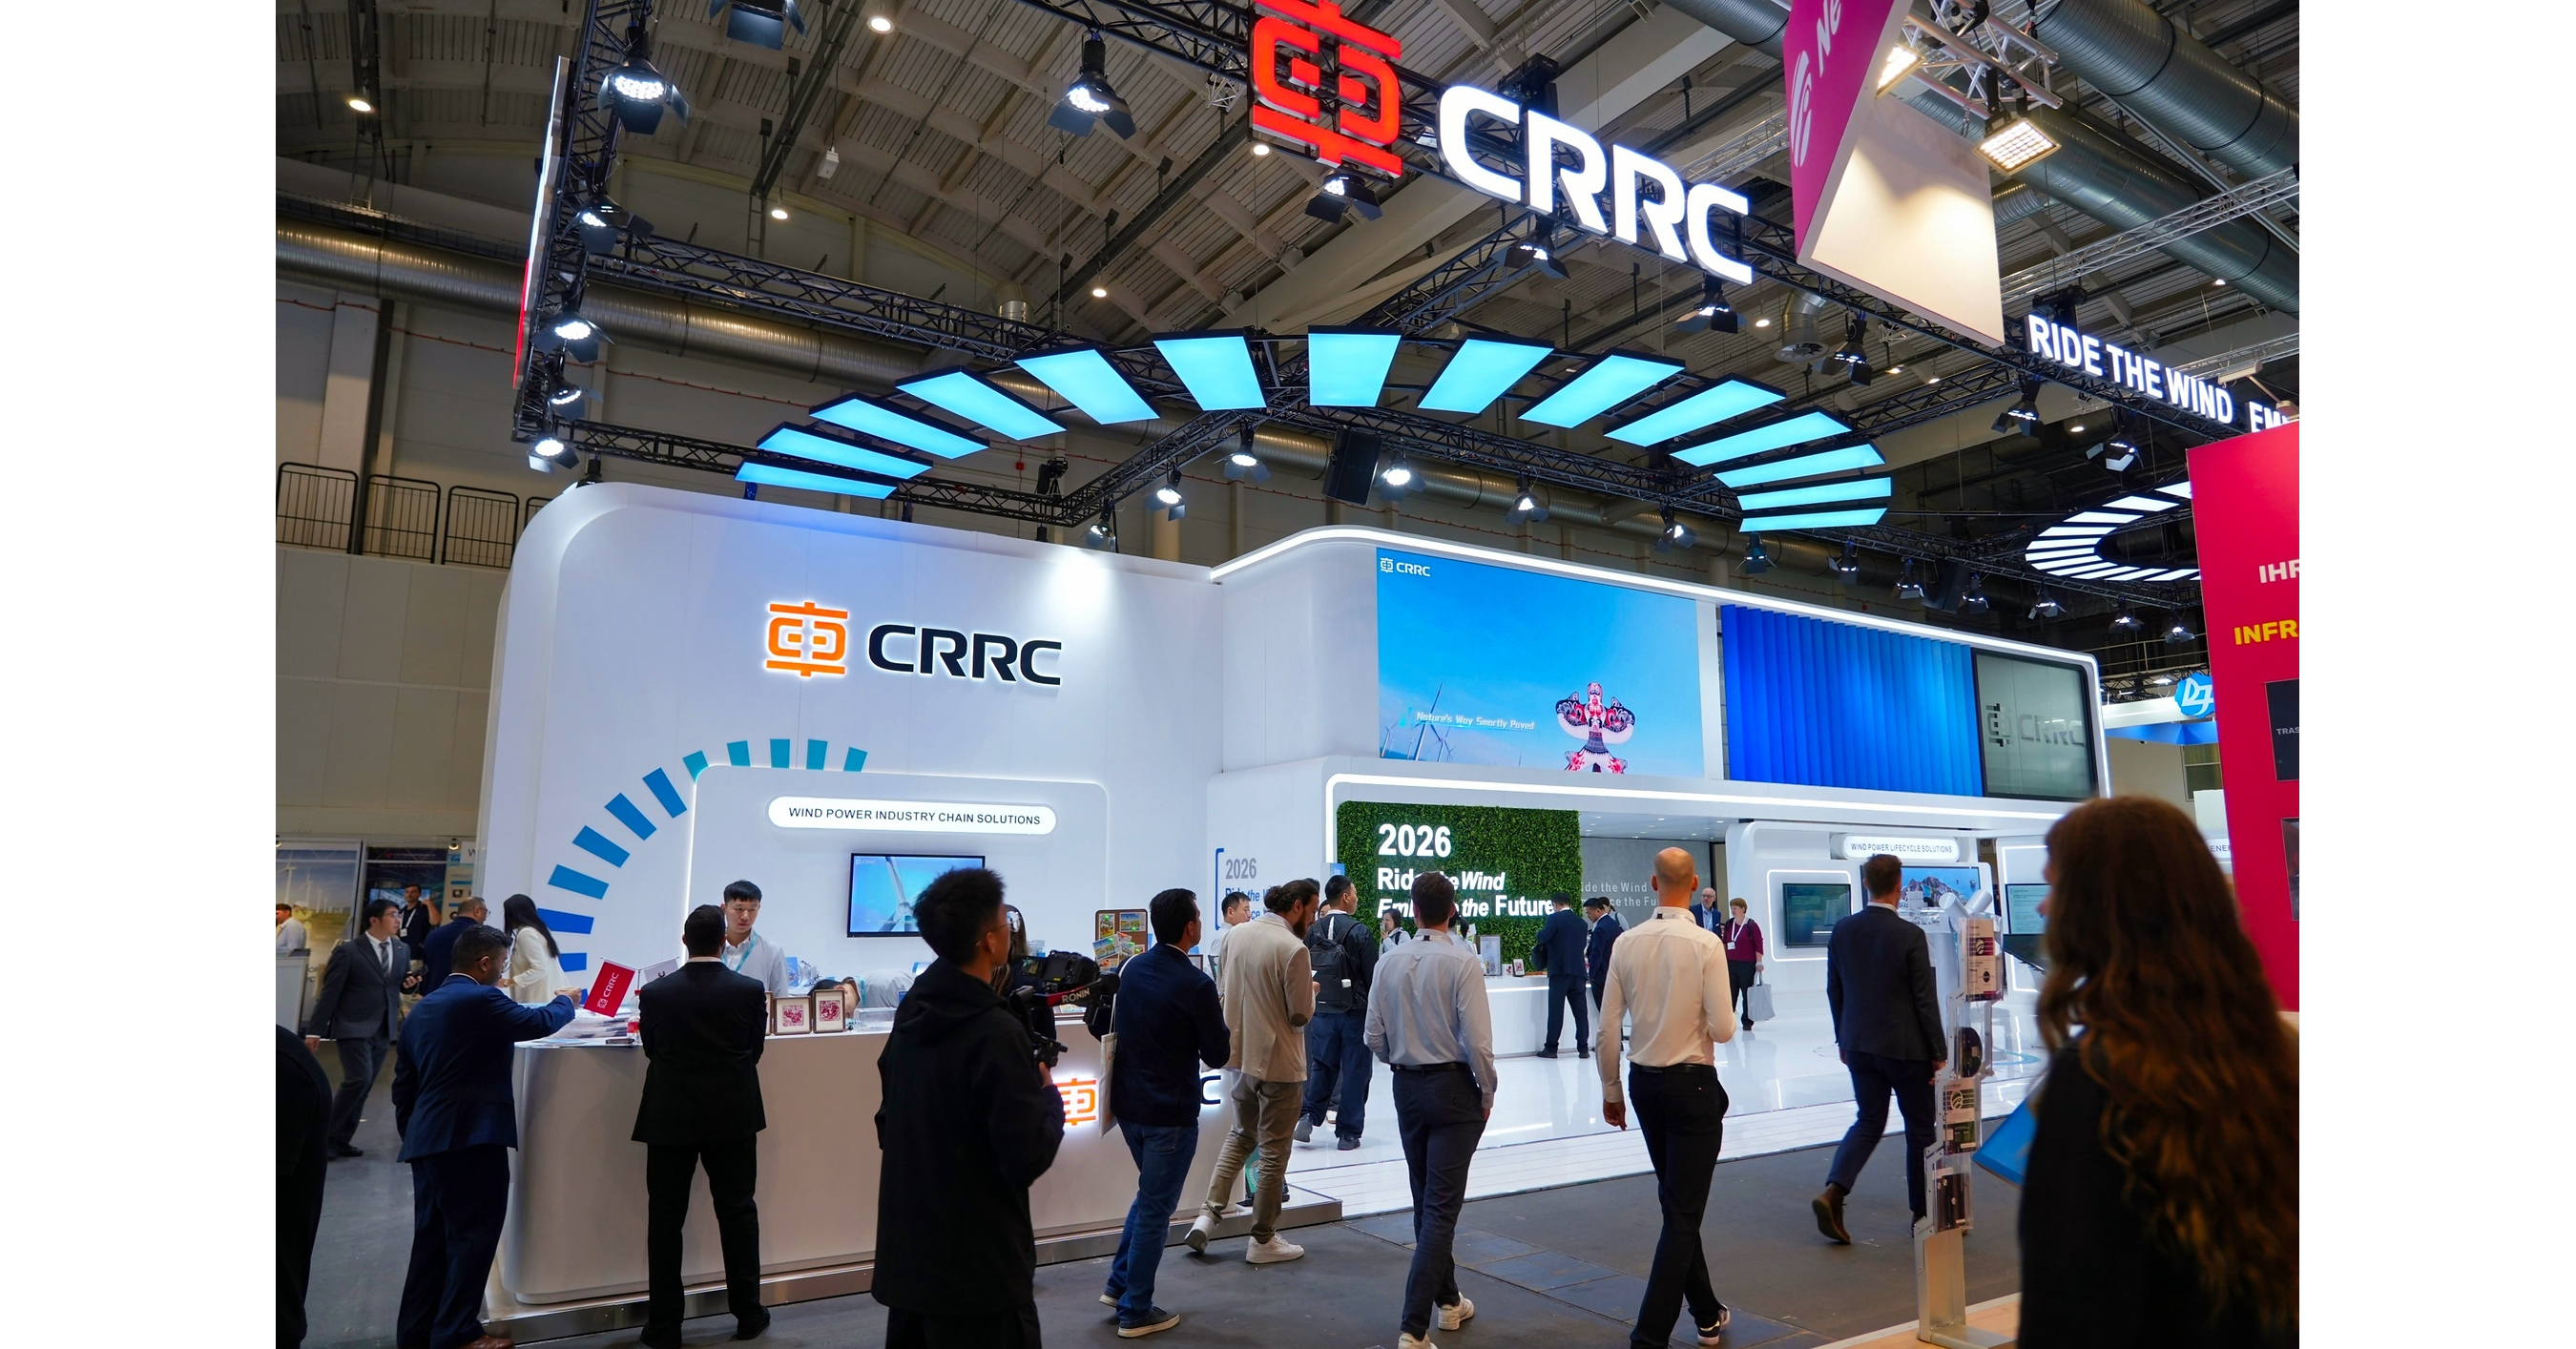
CRRC secured TÜV SÜD type certification for its 7.15MW D195 wind turbine and expanded its technical collaboration with floating-wind developer X1 Wind at WindEnergy Hamburg 2026. The company highlighted a global wind footprint of more than 20 turbine manufacturing sites serving nearly 400 wind farms, with turbine offerings spanning 1.5MW-12MW onshore and 8MW-20MW offshore. Existing projects include 46.2MW in Vietnam and 50MW in Kazakhstan, while the X1 Wind partnership targets joint R&D and faster wind-power innovation.
Analysis
The certification is commercially relevant only insofar as it shortens qualification cycles with European developers, lenders and insurers; it is not evidence of backlog or revenue conversion. CRRC’s vertically integrated manufacturing model could pressure turbine ASPs and service-bundle pricing if it secures EU reference projects, with the most exposed European OEMs being Nordex (NDX1) in onshore and Vestas (VWS) in selected value-sensitive tenders. Siemens Energy (ENR) is relatively less directly exposed because its wind earnings sensitivity is increasingly tied to offshore execution and warranty normalization rather than commodity-style onshore pricing.
Near term, this is not a stand-alone trade catalyst: certification and an R&D partnership lack disclosed order value, delivery dates, financing support, or local-content commitments. Over 1-3 months, watch European tender awards, project-finance acceptance of CRRC equipment, and any localized blade/nacelle investment; those would validate whether certification converts into addressable demand. Over 6-18 months, the key counterforce is EU trade and cybersecurity policy: tighter foreign-subsidy scrutiny, local-content preferences, or grid-security restrictions could prevent price competition from translating into share gains and may instead support VWS/NDX1 multiples.
Consensus may overstate the immediate threat to European OEMs. Wind equipment is a bankability and service-network market, not simply a lowest-cost procurement market; developers bear substantial lifetime availability and spare-parts risk. The more consequential second-order effect may be lower bid pricing by incumbents defending share, which would delay margin recovery even if CRRC wins few projects—particularly relevant to Nordex’s operating-margin trajectory.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- No directional position on CRRC (601766) from this release alone; require a disclosed European order, project-finance approval, and delivery economics before treating the certification as an earnings catalyst.
- Maintain a 1-3 month watch on NDX1 versus VWS: initiate a tactical short NDX1 / long VWS pair only if CRRC appears in a European onshore tender shortlist or NDX1 signals pricing concessions. Nordex has greater exposure to price-sensitive onshore competition; invalidate the trade if Nordex raises margin guidance or reports improving order pricing.
- For existing VWS or ENR longs, use European tender pricing and order-margin commentary as the risk trigger rather than shipment headlines. A broad deterioration in OEM order margins would be more material than any individual CRRC certification.
- Monitor EU foreign-subsidy, procurement-security, and localization developments over the next 6-18 months. A formal restrictive action would be a potential positive catalyst for VWS/NDX1; absence of action combined with financed CRRC project awards would shift the balance toward European OEM multiple compression.
More News
- Will Trump strike nuclear sites again as Iran engages ‘cognitive warfare’?
- How the US midterm elections reflected resistance to data centres
- Elon Musk once said the Cybertruck would be Tesla’s ‘best product ever.’ Now he’s winding down production
- AI Party isn't Ending Because Of The Blue Wave Says Ives
- SoftBank, ABB consider China carve-out to rescue $5.4bn robotics deal
- A ‘geologic freak’ called the Smackover may end America’s lithium dependence on China, and Big Oil is already there