
Adobe posts record quarter, lifts guidance as AI push pays off
Source: proactiveinvestors.com
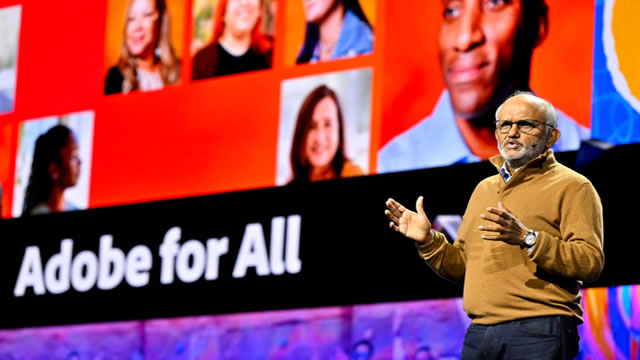
Adobe reported record Q3 revenue of $6.8 billion, up 13% year over year and above the $6.69 billion analyst consensus. The company also beat profit expectations and raised full-year revenue and earnings guidance, citing growing traction for its AI software tools. The results support a strengthening monetization outlook for Adobe's AI product push.
Analysis
The investable question is whether AI is creating incremental recurring revenue or merely improving retention within Adobe’s existing installed base. Near-term upside should come from reduced AI-disruption fears and post-earnings estimate revisions; the more consequential 1-3 month catalyst is disclosure of paid AI attach rates, net-new ARR, and pricing realization in Creative Cloud and Document Cloud. Without those metrics, the market is likely to treat AI traction as a multiple-defense narrative rather than a durable reacceleration catalyst.
Adobe’s distribution advantage is underappreciated: embedding AI into established creative and enterprise workflows lowers customer-acquisition cost versus standalone AI-design tools and makes switching operationally disruptive. The offset is that inference expense and bundled features can dilute gross-margin expansion if usage grows faster than monetization; this is particularly relevant if customers consume generative credits without upgrading seats or plans. Over 6-18 months, Adobe’s strongest competitive benefit is likely enterprise governance, rights management, and workflow integration—not raw image-generation quality, where product parity can emerge quickly.
Consensus risk remains that AI tools compress the value of creative software by lowering skill barriers. That outcome is more damaging to low-end point-solution vendors and stock-content ecosystems than to Adobe if it can capture the workflow layer, but it would invalidate the bullish view if paid-seat growth slows while AI usage rises. A reversal signal would be weaker next-quarter recurring-revenue growth, a reduction in forward operating-margin expectations, or management framing AI primarily as retention rather than a separately monetized product tier.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Accumulate ADBE in thirds over the next 1-3 weeks rather than chase the initial earnings reaction; add only if the next investor communication supports paid AI monetization and does not signal material gross-margin pressure. Target a 10-15% relative move versus IGV over 3 months; exit if forward guidance is cut or recurring-revenue growth decelerates despite rising AI engagement.
- For defined-risk upside, use a 3- to 6-month ADBE call spread: buy near-ATM calls and sell calls 10-15% higher. This expresses the estimate-revision and multiple-stabilization thesis while capping exposure if AI enthusiasm fades; limit premium at risk to the amount justified by the portfolio’s technology risk budget.
- Monitor Adobe’s next disclosure for three decision metrics: paid Firefly/AI conversion, net-new ARR contribution, and gross-margin/infrastructure-cost commentary. If management cannot quantify at least one monetization metric, treat the result as a sentiment event rather than a fundamental upgrade and avoid increasing exposure.
- Avoid using public creative-software peers as a clean short hedge: Adobe’s principal competitive threats are largely private or embedded in broader platforms, making a direct pair trade noisy. A sector hedge through IGV is preferable if the position is intended to isolate Adobe-specific execution.
More News
- 2 Unloved Stocks of 2026 to Consider Buying Now
- Adobe: A Fairly Priced Compounder In An Expensive Market
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Biotech stocks are surging. How investors can play the new drug innovation boom
- AI funding fears rattle Wall Street. Here's how we're adjusting our portfolio
- Braskem creditors, shareholders near deal on $11bn debt restructuring
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Index and ETF Holdings Data for AI Research
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)