
NWPG's NFI Empire Advances Project Reborn-001 Toward Auction Benefiting The Brett Boyer Foundation
Source: Newswire
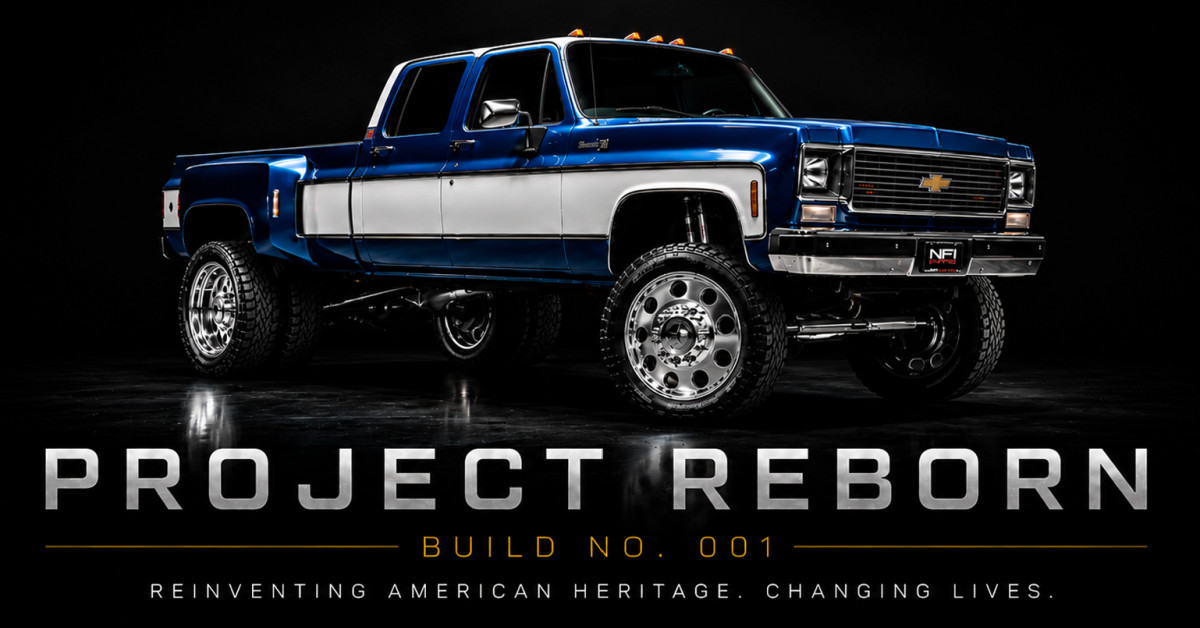
Newport Gold's wholly owned NFI Empire received a GMC Sierra 3500 Duramax donor vehicle from Copart for Project Reborn-001, a custom 1979 Chevrolet K30 build planned for auction at The Red Bird Games in Brentwood, Tennessee. Auction proceeds will benefit The Brett Boyer Foundation's congenital heart disease research and family-support initiatives. The update is a charitable project milestone rather than a material financial, earnings, or operating development for NWPG or Copart.
Analysis
This is immaterial to CPRT’s earnings power, throughput, take rate, or capital allocation; it should not alter estimates or justify a directional position. The only modest read-through is reputational: donating a rebuildable late-model platform highlights the breadth of Copart’s inventory and its accessibility to specialty rebuilders, but a single charitable transaction has no bearing on auction volumes, insurance total-loss trends, or pricing.
For NWPG, the release is promotional rather than a financially measurable operating milestone. There is no disclosed build cost, auction-date certainty, expected proceeds, recurring revenue model, audited segment economics, or evidence that a custom-build business can scale without consuming disproportionate labor and working capital. In an illiquid OTC security, publicity-led volume can create sharp but non-fundamental moves; the asymmetric risk is downside if the auction generates limited proceeds or management shifts the narrative before providing verifiable financial disclosures.
The relevant CPRT investment debate remains the 1-3 month cadence of U.S. salvage supply, insurance carrier assignment volumes, used-vehicle values, and international-unit growth—not brand-adjacent charity activity. Over 6-18 months, higher vehicle repair complexity and parts costs remain constructive for total-loss frequency, while falling used-car values or insurer retention of damaged vehicles would pressure average selling prices and consignment economics. No trade is warranted from this item alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- Take no incremental CPRT exposure on this release; maintain existing thesis only through independently reported unit growth, U.S. insurance assignment volumes, and auction-service revenue trends.
- Do not trade NWPG on the announcement. Treat any abnormal liquidity or price spike as an alert to assess filing quality, share-count changes, cash balance, related-party transactions, build costs, and auction proceeds before considering exposure.
- For CPRT holders, use the next earnings release as the catalyst window: add only if unit growth and auction revenue outperform while margin holds; reduce if management cites weaker salvage volumes, declining selling prices, or material international-margin pressure.
- Monitor wholesale used-vehicle indices and repair-cost inflation over the next 1-3 months. A sustained decline in used-car values is a thesis risk for CPRT and should prompt tighter risk limits regardless of this non-financial announcement.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Is Amazon Stock a Buy After Its Best Quarter in Years?
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid
- Trip.com swings to Q2 loss after $763 million antitrust penalty