
SAZERAC REVIVES HISTORIC GLENMORE NAME WITH THE LAUNCH OF TWO NEW KENTUCKY WHISKEYS
Source: PR Newswire
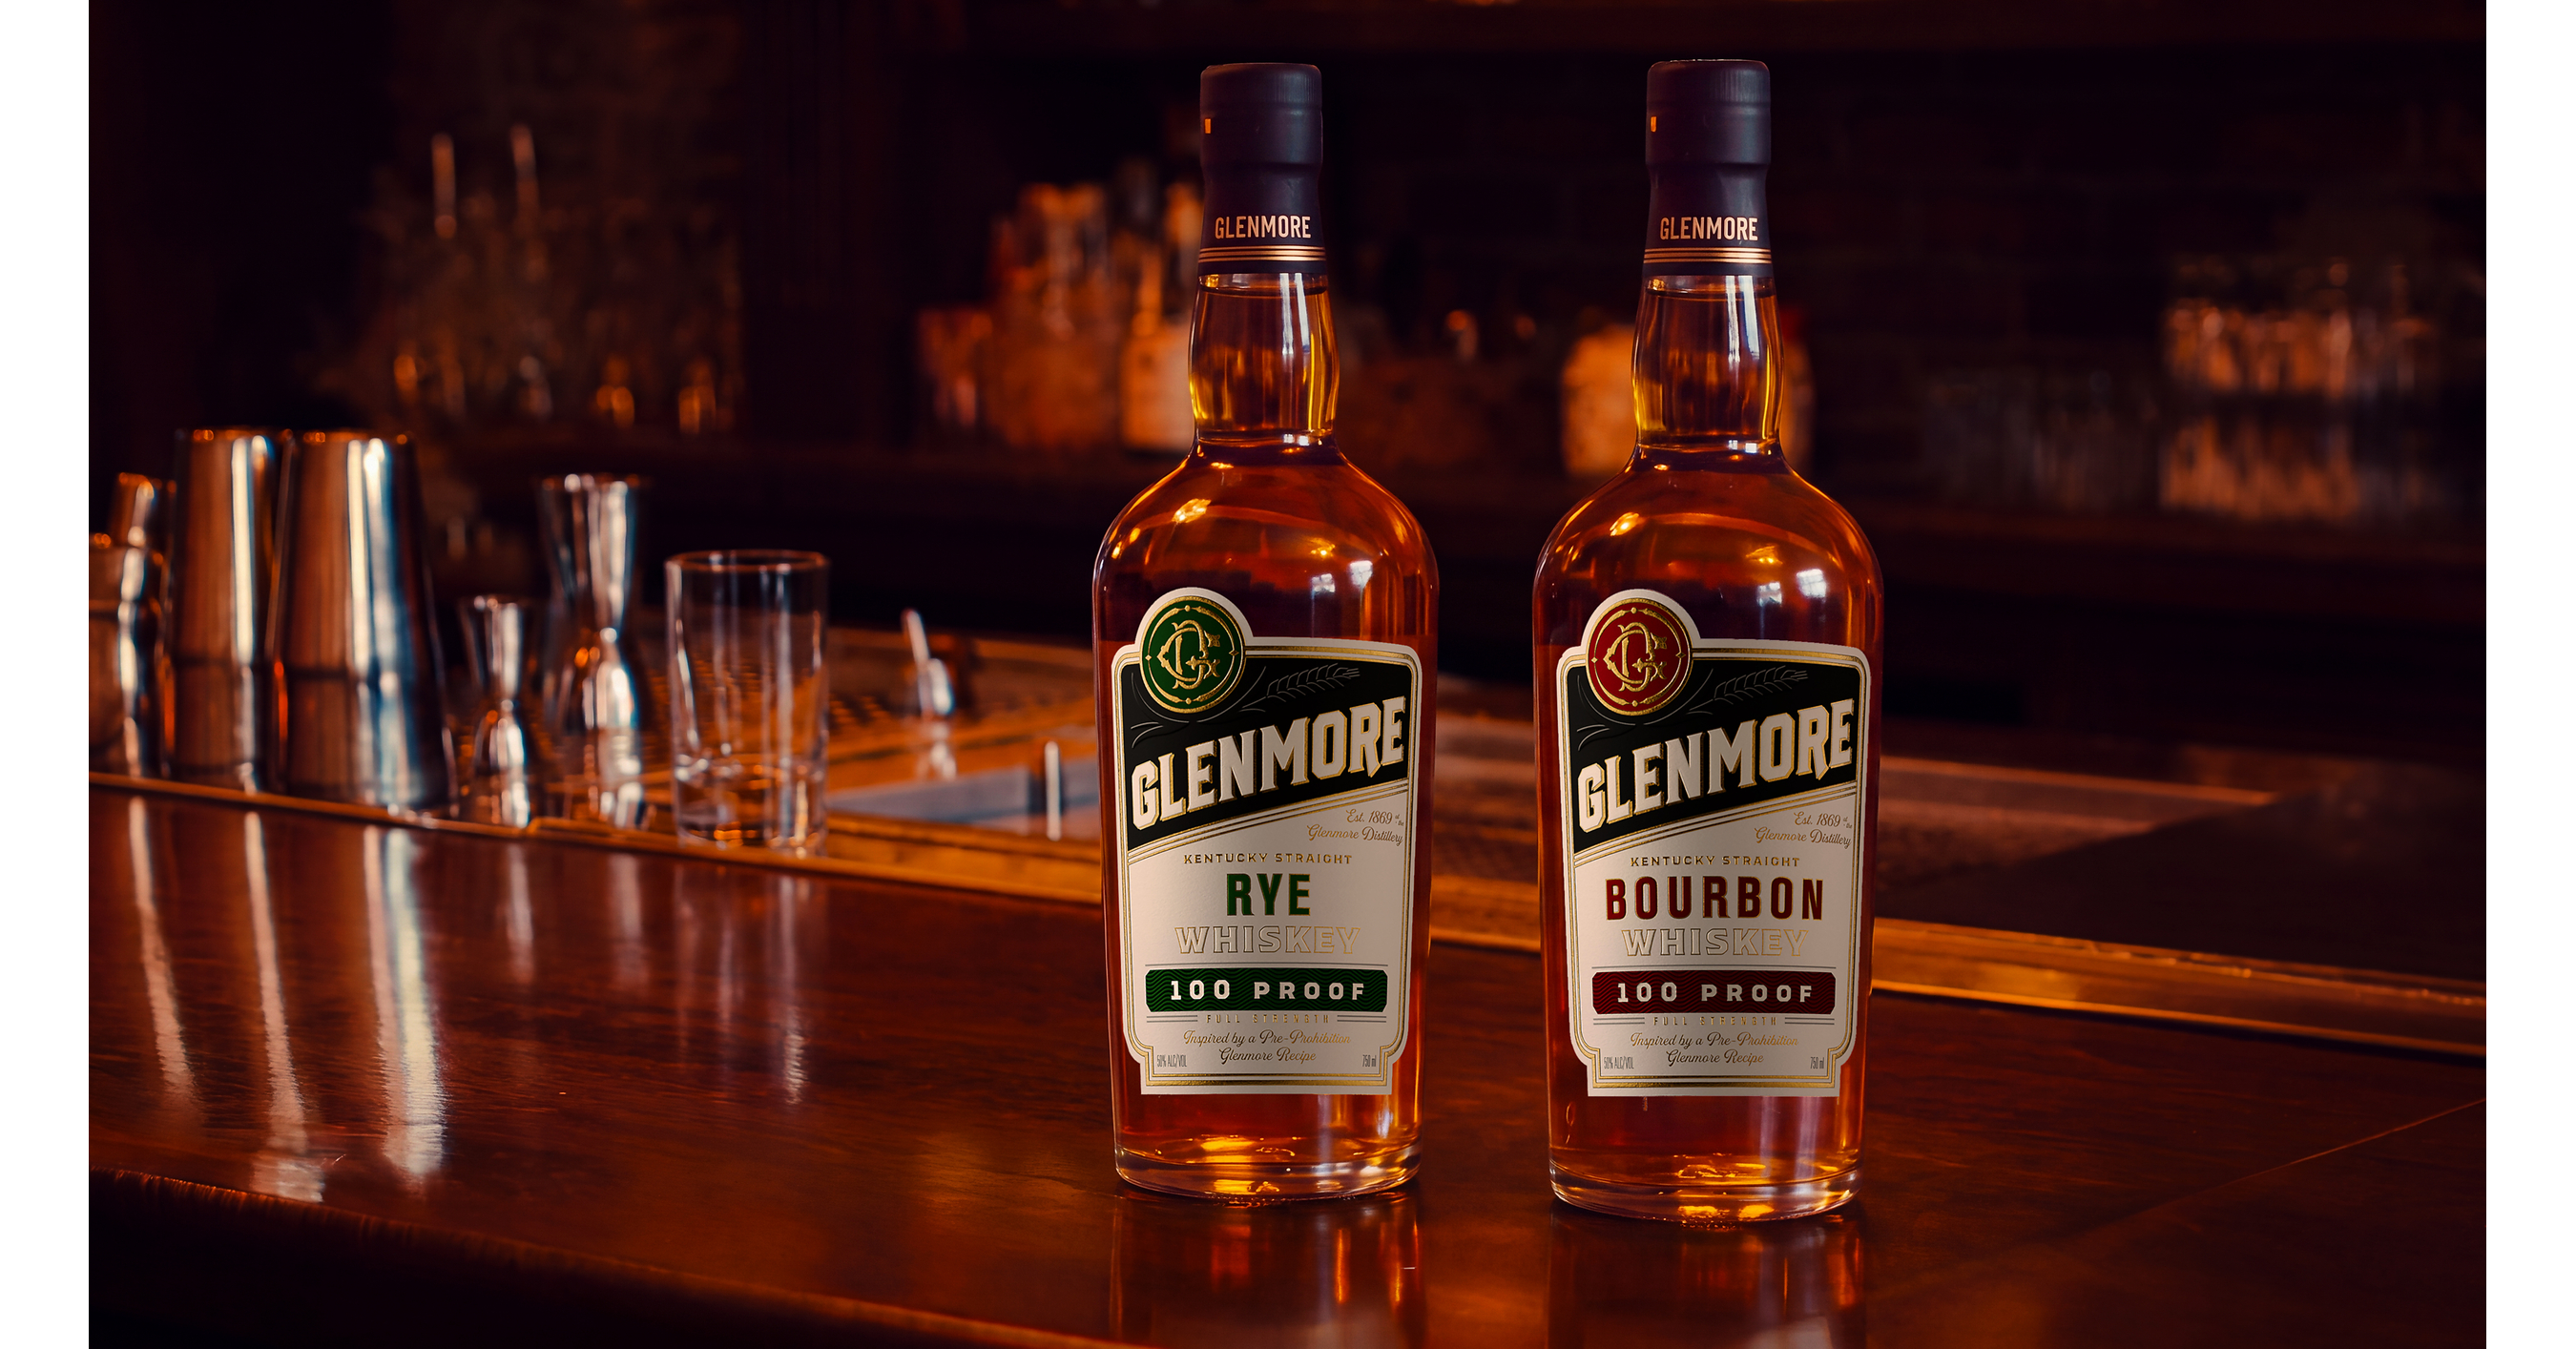
Sazerac launched Glenmore Kentucky Straight Bourbon Whiskey and Glenmore Kentucky Straight Rye Whiskey, reviving the historic Glenmore brand at a suggested retail price of $19.99 per 750ml bottle. Both products are bottled at 100 proof; the bourbon is shipping immediately through Sazerac's U.S. distributor network, while the rye is scheduled to become available in September 2026. The launch expands Sazerac's whiskey portfolio but is unlikely to have material public-market implications.
Analysis
This is not a public-markets catalyst: Sazerac is privately held, and a value-priced line extension has no independently verifiable volume, pricing, or margin disclosure. The relevant mechanism is category-level competition at the $20 shelf-price tier, where distributor execution and retailer reset placement matter more than heritage branding. There is no basis to infer incremental demand versus cannibalization of Sazerac’s existing accessible whiskey portfolio.
Near term, watch syndicated scanner data and distributor depletion commentary for evidence that the launch takes share from comparable mainstream American whiskey rather than merely expands Sazerac facings. Public peers with greatest theoretical exposure are Brown-Forman (BF.B), Diageo (DEO), and Pernod Ricard (RI), but their bourbon/rye revenue sensitivity is too diluted for this announcement alone to affect estimates. The more meaningful second-order read-through would be further promotional intensity in US brown spirits, which could pressure gross margin across the category if competitors defend retail shelf space with trade spending.
Contrarian view: a $20, 100-proof offer may be better positioned than premium whiskey launches if consumers continue trading down, but that benefit accrues primarily to private Sazerac. Conversely, the launch could signal that capacity holders expect slower premiumization and are targeting velocity-led price points; this becomes investable only if BF.B, DEO, or RI cite US whiskey discounting, weaker price/mix, or inventory normalization in upcoming results. No trade is warranted on the release itself.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate position: treat as a private-company product-launch datapoint, not a catalyst for BF.B, DEO, or RI.
- Monitor BF.B quarterly US whiskey net-sales growth, organic price/mix, and gross-margin commentary over the next 1-3 months; a shift to negative price/mix or increased A&P/trade spend would support a tactical underweight versus staples.
- Set an alert for Nielsen/IRI evidence of broad sub-$25 bourbon/rye share gains alongside declining premium-tier velocity. If confirmed over two consecutive reporting periods, reassess a relative short BF.B versus a more diversified global spirits exposure such as DEO; falsify if premium velocity stabilizes without promotional escalation.
- For 6-18 months, watch US brown-spirits inventory and distributor-depletion trends rather than launches. A sustained retail trade-down would favor scale operators with low-cost production and distribution, but public-peer earnings disclosures are required before establishing exposure.
More News
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid
- Trip.com swings to Q2 loss after $763 million antitrust penalty
- Federal Reserve decision, retail sales, and oil inventories due Wednesday
- Reliance Worldwide shares hit 1-year high on Brookfield’s $2.9 bln deal
- Why Dave & Buster's Stock Tumbled Today