
VIO Med Spa Earns Place Among Nation's Largest Franchise Systems on 2026 Franchise Times Top 400
Source: PR Newswire
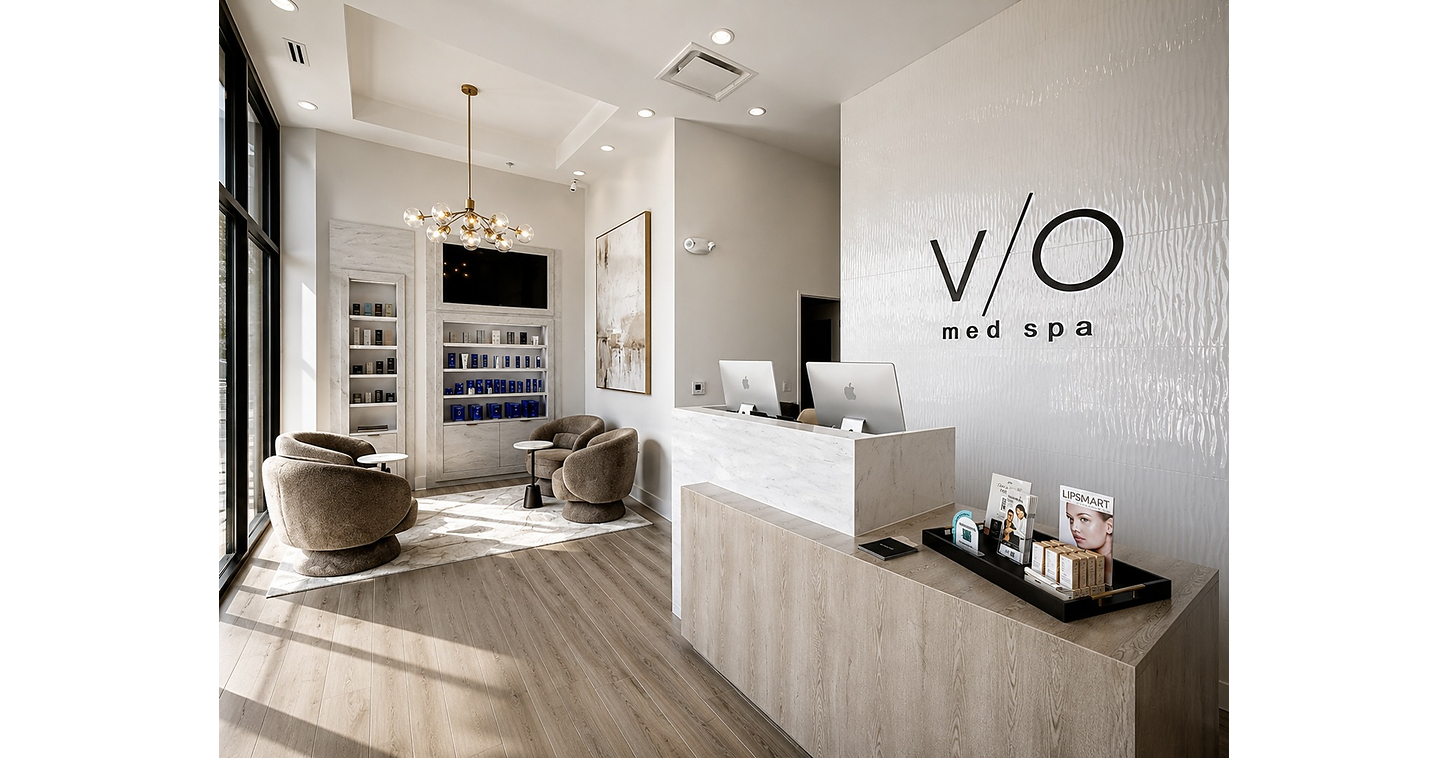
VIO Med Spa ranked No. 373 in the 2026 Franchise Times Top 400 based on 2025 systemwide sales and signed a record 19 new franchise owners in the first nine months of 2026. The company reported 2025 average unit volume of $1.3M across 51 operational franchise outlets, with a $2.3M top-quartile average, while launching ClubVIO recurring-revenue memberships and a smaller-footprint store design intended to reduce development costs. VIO operates 65 locations across 20 states and has more than 175 territories open, sold, or under development.
Analysis
This is not directly tradeable: VIO and its sponsor are private, and the disclosed development pipeline is not equivalent to opened, revenue-producing units. The relevant public read-through is limited to aesthetic consumables and equipment vendors—AbbVie (ABBV), Galderma (GALD), Evolus (EOLS), InMode (INMD), and Bausch Health (BHC)—but one franchise network’s expansion is immaterial to their consolidated sales. The more useful signal is that franchise capital remains available for a discretionary, cash-pay category despite a selective consumer backdrop.
A membership-led model can improve franchisee retention and unit economics by smoothing visit frequency, but it also creates deferred-service obligations and raises the risk that promotional pricing masks underlying treatment demand. The key 1-3 month diligence item is not franchise agreements but conversion: openings, mature-unit same-store sales, membership penetration, treatment mix, and four-wall payback versus the prior store format. If lower build-out costs materially shorten payback, regional competitors may respond with discounting or aggressive provider recruiting, pressuring labor and marketing costs before the category’s supply-demand balance is proven.
For public equities, the cleaner 6-18 month implication is that scaled, medically supervised chains may consolidate share from independent spas, favoring branded injectables with training, compliance support, and repeat-treatment protocols. However, the consensus risk is that aesthetics demand is more rate- and employment-sensitive than recurring-revenue framing suggests; membership can reduce churn but cannot eliminate discretionary spend compression. A weakening high-income consumer, provider shortages, or state-level tightening of medical-director and delegation rules would most quickly challenge the expansion thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Key Decisions for Investors
- No standalone trade on this release; treat it as a watch signal rather than a catalyst because neither the franchisor nor sponsor is publicly listed and financial conversion data are absent.
- Maintain a 3-6 month quality bias toward ABBV and GALD over smaller device exposure such as INMD: consumable injectables have recurring treatment demand and less dependence on new-location equipment capex. Reassess if U.S. aesthetics growth or management commentary turns negative for two consecutive reporting periods.
- Use EOLS as a higher-beta sentiment monitor, not a directional recommendation: sustained franchise openings and injector adoption could support share gains, but a slowdown in cash-pay procedure demand would likely hit its valuation disproportionately. Require evidence of stable procedure volumes and improving operating leverage before initiating.
- Set an alert around state medical-spa supervision/delegation proposals and quarterly commentary on aesthetic procedure volumes from ABBV, GALD, EOLS, and INMD. A regulatory tightening event or a clear deceleration in U.S. consumer aesthetics is the falsifier for the broader category read-through.
More News
- Europe’s winter energy crunch may already be underway. Two U.S. stocks that may benefit
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial