
RTX Corporation Q3: Crushing Operational Expectations But Valuation Limits The Upside
Source: seekingalpha.com
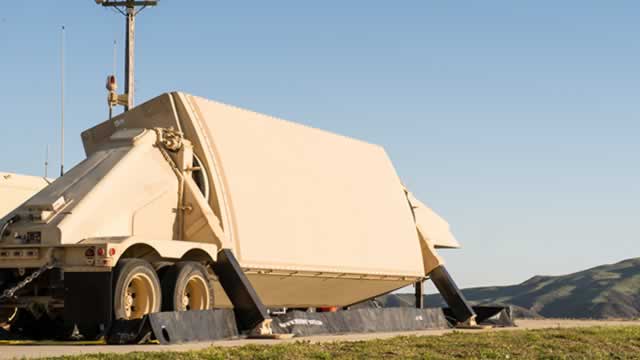
RTX reported 2026 Q3 revenue, operating profit and EPS growth that exceeded the author’s initial projections, and a record $340 billion backlog: $176 billion in commercial aviation and $164 billion in defense. The article says relative valuation models indicate 21–44% downside versus peers, tempering the positive operational performance.
Analysis
The key tension is between execution momentum and valuation: a durable order book can support estimates, but it does not by itself validate a premium multiple. Backlog converts to value only as deliveries, customer funding, pricing, and supplier capacity support cash generation; slippage or cost escalation could leave reported backlog intact while pushing cash realization out. The commercial and defense portions also have different sensitivities: commercial conversion depends on aircraft production and utilization, while defense conversion is exposed to procurement timing and budget priorities. These are distinct risks, not a single visibility signal.
Near term, strong results may sustain relative strength, making an outright short vulnerable to estimate upgrades. Over 1–3 months, focus on guidance, segment cash conversion, delivery cadence, and whether analyst revisions catch up with execution. Over 6–18 months, the debate is whether backlog growth translates into returns and free cash flow sufficient to defend the valuation versus aerospace-and-defense alternatives.
The stated 21–44% downside is model output, not an independently established fair-value range; without the peer set, valuation date, and assumptions, it is not a price target. Consensus may be underestimating execution durability, while valuation models may underweight the time and risk involved in converting orders to cash. No immediate directional trade is compelling on this evidence alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- Keep RTX at benchmark weight pending verification of valuation inputs and cash conversion; avoid treating the article’s downside range as a short target.
- For a relative-value expression, consider a small short-RTX/long-aerospace-and-defense-ETF pair only if RTX continues to outperform while its relative valuation premium widens. Define risk by the pair spread, and exit if RTX’s estimate revisions and cash conversion improve enough to justify that premium.
- Over the next 1–3 months, verify segment-level free cash flow, delivery and backlog conversion, guidance revisions, and the valuation model’s peer set and assumptions. Weak conversion or downward guidance revisions would strengthen the underweight case; sustained conversion and upward revisions would falsify it.
- Do not infer that the entire backlog is equally firm or profitable. Monitor procurement delays, commercial aircraft production constraints, and supplier bottlenecks as potential causes of timing slippage over the next 6–18 months.
More News
- Why popular airplanes are getting scrapped years early
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Trump set to announce plan by Audi to build a U.S. factory in Georgia, source says
- AI funding fears rattle Wall Street. Here's how we're adjusting our portfolio
- Braskem creditors, shareholders near deal on $11bn debt restructuring
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Selecting an AI Research Platform for Institutional Investors
- Weekly Update: New Reporting Features and More Sources for Document Search