
Haier Biomedical präsentiert automatisierte Biolagerung und vernetzte Pharma-Lösungen auf der ISPE Singapore 2026
Source: PR Newswire
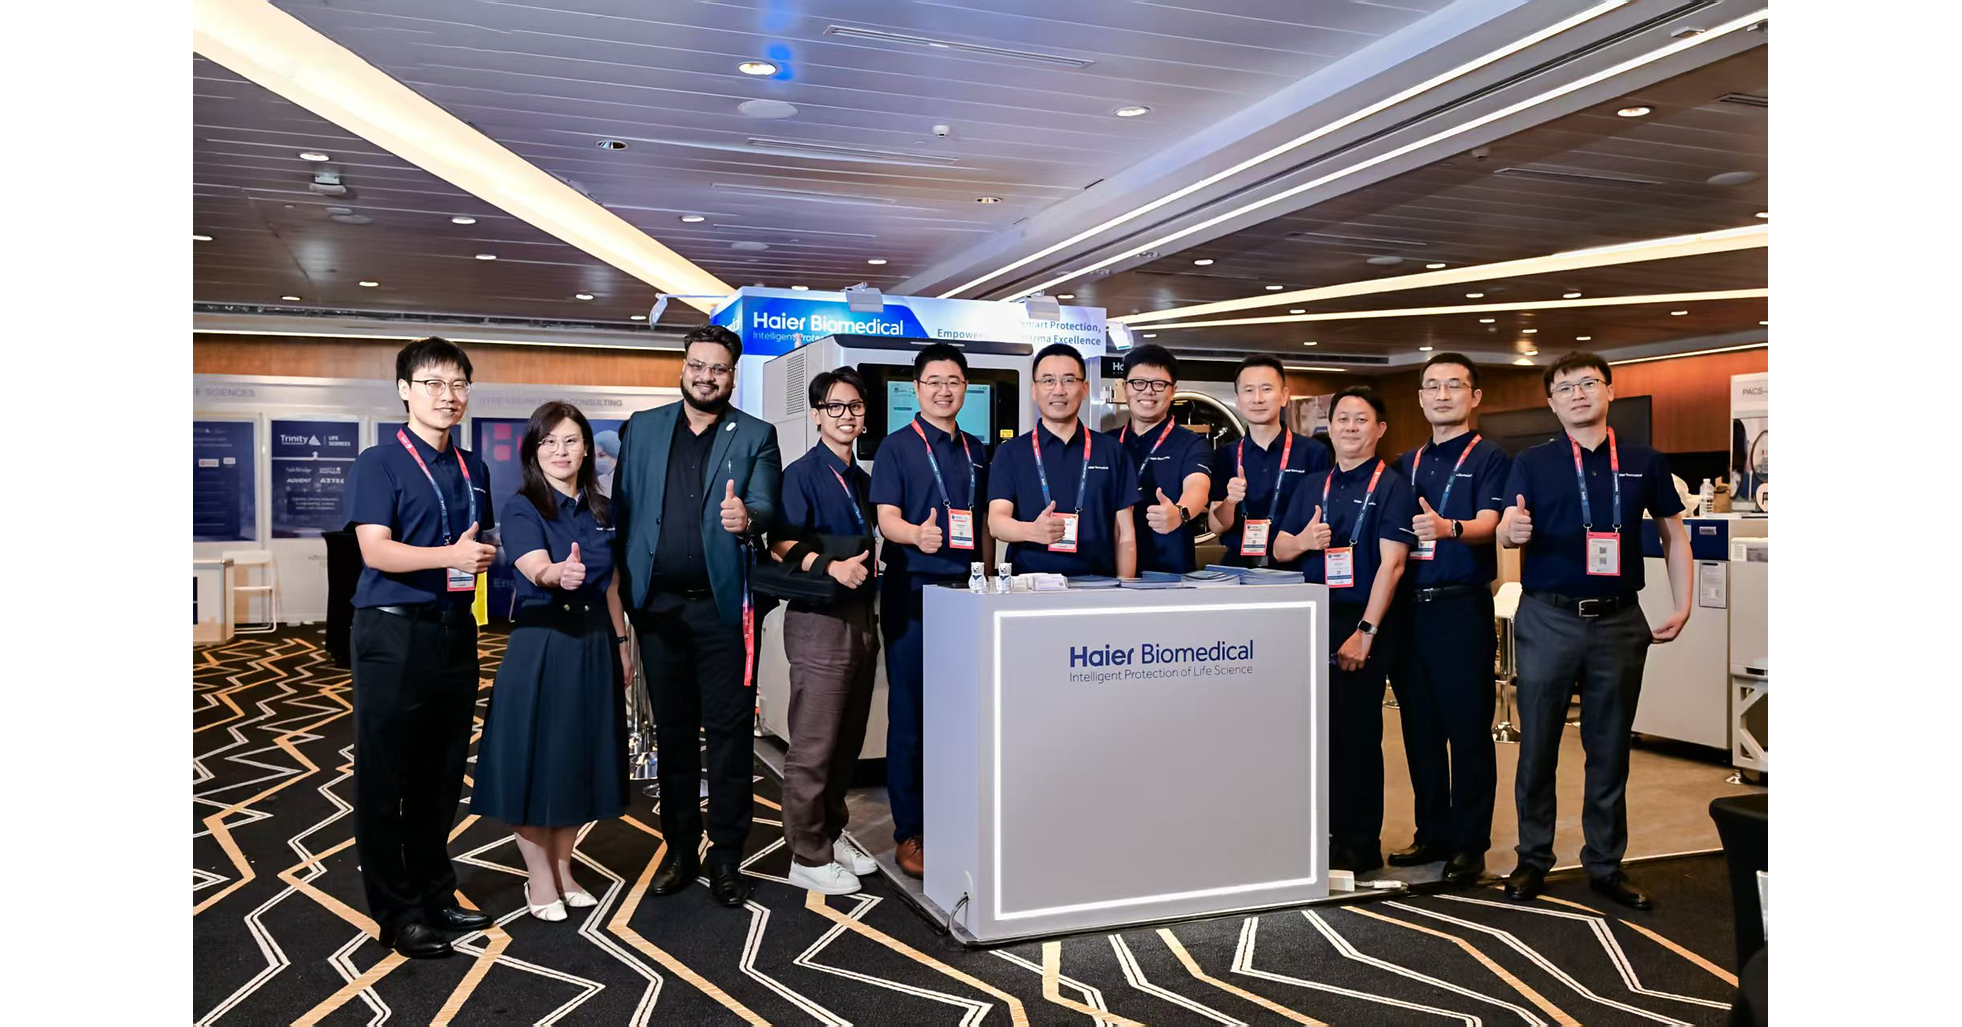
Haier Biomedical stellte auf der ISPE Singapore 2026 automatisierte -80°C-Lagerung sowie einen Pilot-Gefriertrockner und eine „Smart RFID ULT Storage Solution“ vor, um Probenmanagement und Rückverfolgbarkeit entlang des gesamten Workflows zu verbessern. Operativ berichtete das Unternehmen für das 1. Halbjahr 2026 einen 23%-Anstieg des Umsatzes mit Pharmakunden (YoY) und 19% Wachstum bei Laborlösungen, während KI-bezogene Bereiche 18% des Umsatzes ausmachten (+3 Prozentpunkte vs. 2025). Die Präsentation unterstreicht die Verschiebung von Einzelgeräten hin zu integrierten Mehrprodukt-Portfolios und laufenden Dienstleistungen.
Analysis
The strategic signal is less about a new product launch and more about a shift from one-off equipment sales to workflow lock-in. If Haier can own sample identity, storage location, and audit trail inside regulated labs, it raises switching costs and makes the installed base materially stickier; that is the real multiple driver, not the freezer SKU. The cleaner second-order winner is RFID/track-and-trace infrastructure, while the loser is any standalone ULT/freezer vendor competing only on price and service response.
Near term, this is mostly a marketing validation event, not a financial inflection. The stock only becomes interesting over the next 1-3 months if order conversion shows up in backlog, service attach, and gross margin; pharma buyers tend to stretch sales cycles after conference demos, not shorten them. If the integrated system is actually displacing piecemeal vendor stacks at CDMOs and QC labs, that is a 6-18 month competitive shift, not a day-one catalyst.
Contrarian view: the market may be overweighting the AI label here. A rising share of "AI-related" revenue can just mean software bundling and automation reclassification, which does not automatically imply high-margin recurring revenue. The thesis fails if margins do not expand, recurring service revenue stays muted, or customers treat this as a refresh cycle rather than a platform adoption; in that case, the business remains a hardware franchise with a new narrative.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- Do not chase 688139.SH on the press release alone; only add on weakness after the next earnings print confirms backlog conversion and gross-margin expansion. Falsifier: no improvement in margin mix or service revenue over the next two quarters.
- Watch/alert the pure RFID beneficiary basket for 1-3 months: long PI (Impinj) as the cleanest second-order beneficiary if regulated sample traceability adoption broadens. Risk/reward is attractive only if the spend shifts from manual scanning to RFID-enabled workflows; otherwise leave it unconfirmed.
- If you want relative value exposure to lab workflow digitization, prefer long DHR/TMO over standalone cryogenic hardware names on any sector pullback. The platform names are better positioned to capture validation, service, and software attach, while point solutions face pricing pressure.
- Use AZTA as the main short candidate only if subsequent channel checks show pricing compression in sample storage or weaker order conversion. Until then, it is a watch item, not a conviction short.
More News
- Christine Lagarde: IMFC Statement
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Palantir patient data tech rejected by many NHS trusts in England
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- Wall Street Anxiety Spreads as AI Rout Meets $110 Oil Shock
- Wall Street's fear gauge is ripping. Traders see it going even higher
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- Alternative Data Due Diligence for Institutional Investors