
China Xplained | Étreinte chinoise ou opportunité pour la Chine ?
Source: PR Newswire
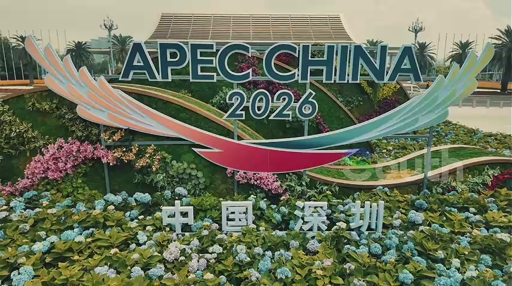
Le Forum des médias de l'Asie-Pacifique 2026 s'est ouvert le 5 septembre à Shenzhen, réunissant plus de 400 représentants avant la réunion des dirigeants économiques de l'APEC prévue en Chine en novembre. L'article examine si l'expansion manufacturière chinoise évince les économies en développement ou crée des opportunités via les chaînes d'approvisionnement et les investissements, sans avancer de données financières ou de conclusion chiffrée.
Analysis
This is promotional narrative rather than a policy action, earnings disclosure, or independently verifiable demand signal; it does not merit a directional position. The investable issue is whether China’s manufacturing push translates into renewed export-price deflation, which would pressure regional producers with less scale, weaker supplier ecosystems, and higher funding costs—notably Taiwan/Korea hardware assemblers, ASEAN commodity-light manufacturers, and selected European capital-goods suppliers.
Over the next 1-3 months, monitor China export unit values, PPI, container rates, and monthly trade data for evidence that capacity is being cleared through price rather than incremental global demand. A sustained decline in export prices alongside rising volumes would be margin-negative for competing manufacturers but supportive for downstream global buyers and disinflation-sensitive assets. The 6-18 month implication is more consequential: continued Chinese scale advantages in batteries, solar, industrial automation, and consumer electronics can force consolidation or protectionist responses, creating episodic tariff-driven volatility rather than a smooth competitive outcome.
The contrarian point is that China’s export competitiveness is not uniformly bearish for emerging markets. Countries embedded in Chinese-led supply chains—Mexico, Vietnam, Malaysia, and Thailand—can gain assembly, logistics, and localization investment even as domestic producers lose share. The key distinction is between economies selling substitutable finished goods and those providing complementary labor, industrial land, components, or access to protected end markets.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No immediate trade: treat this as an alert, not a catalyst. Require confirmation from Chinese export-price data and evidence of inventory liquidation before expressing a view.
- If China export unit values fall for two consecutive monthly releases while volumes accelerate, consider a 3-6 month pair: long Global X China Electric Vehicle & Battery ETF (2845 HK) or CATL (300750 CH) proxies versus short iShares MSCI Global Clean Energy ETF (ICLN). Thesis: Chinese cost leaders can sustain price cuts longer than ex-China solar/battery competitors; exit if export prices stabilize or major tariff action materially restricts market access.
- Use Vietnam ETF (VNM) and iShares MSCI Malaysia ETF (EWM) as watchlist beneficiaries of supply-chain localization, not direct China-beta longs. Initiate only after FDI/manufacturing-export data confirm acceleration; the principal risk is that Chinese overcapacity displaces, rather than complements, local production.
- For a tariff-escalation hedge over the next 6-12 months, monitor European solar and industrial-automation names versus Chinese suppliers. Any coordinated US/EU trade action would likely compress China-exposure multiples first, even if it improves long-run pricing for protected domestic producers.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- France is flashing euro crisis signals. This time, the fault lines are different
- EU entering winter with lowest gas reserves on record, IEA boss warns
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- ‘They are trying to intimidate us’: Indonesia’s Prabowo remains defiant in the face of an MSCI double downgrade
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.