
Micron: American-Made DRAM Could Be A Competitive Advantage
Source: seekingalpha.com
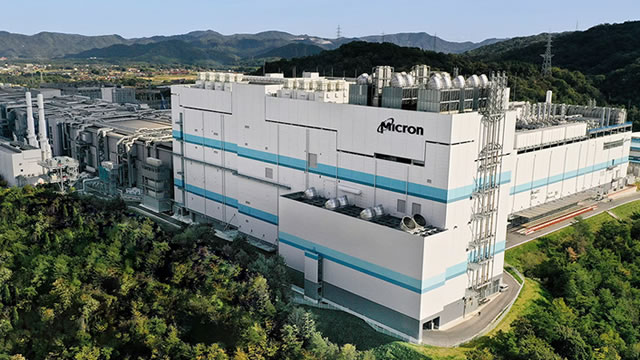
Micron is expanding U.S. DRAM manufacturing, with federal and state incentives—including CHIPS Act grants and tax credits—and customer premiums for U.S.-made memory helping offset higher production costs. The article says the economics are broadly attractive without requiring a rerating, but provides no specific cost, incentive or premium figures.
Analysis
The investment case hinges less on a “Made in America” premium than on whether that premium is contractually durable and large enough to cover U.S. operating and capital costs through a memory downturn. Grants and tax credits can improve project returns, but their timing, conditions, and accounting treatment matter; they do not eliminate execution risks from ramp, yields, labor, or underutilization. The key second-order risk is that U.S. capacity adds fixed costs and depreciation while DRAM pricing remains cyclical, potentially amplifying downside if demand softens before utilization builds. Samsung and SK hynix could also compete for the same customers and incentives, limiting any scarcity premium. Near term, this is not by itself a rerating catalyst. Over 1–3 months, look for project milestones, funding visibility, and customer commitments; over 6–18 months, realized yields, utilization, and segment economics will determine whether localization is accretive. The thesis weakens if incentives are delayed or reduced, customer premiums fail to appear in realized pricing, or management signals rising costs without corresponding demand or margin support.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Do not pay a premium for the announcement alone; treat the U.S. buildout as a conditional long-term strategic benefit, not proof of near-term earnings accretion.
- For MU, consider adding on broad memory-sector weakness only if subsequent disclosures support durable customer commitments and incentive realization. Verify project-level capex, grant timing and conditions, ramp schedule, and expected utilization before sizing.
- Track DRAM contract pricing and MU guidance alongside buildout costs: improving memory pricing could absorb ramp costs, while falling prices plus higher depreciation would challenge the thesis.
- Use MU’s next project and earnings disclosures as the 1–3 month catalyst check. Reassess if management raises cost or capex expectations without improving demand visibility, or if incentives are delayed or reduced.
More News
- U.S. chip stocks recover sharply after Thursday’s brutal selloff
- South Korean corporate reforms hit rough patch as Samsung digs in
- TSMC considers making advanced memory chips, The Information reports
- TSMC is weighing a move into AI memory chips at Nvidia’s request
- Anthropic's IPO Is Coming. Where Are the Best Opportunities?
- Stocks making the biggest moves midday: Nvidia, Moderna, IonQ, Airbnb, Firefly Aerospace & more