
icotec Receives CMS approval for New Technology Add-On Payment for its CMORE® CT System
Source: PR Newswire
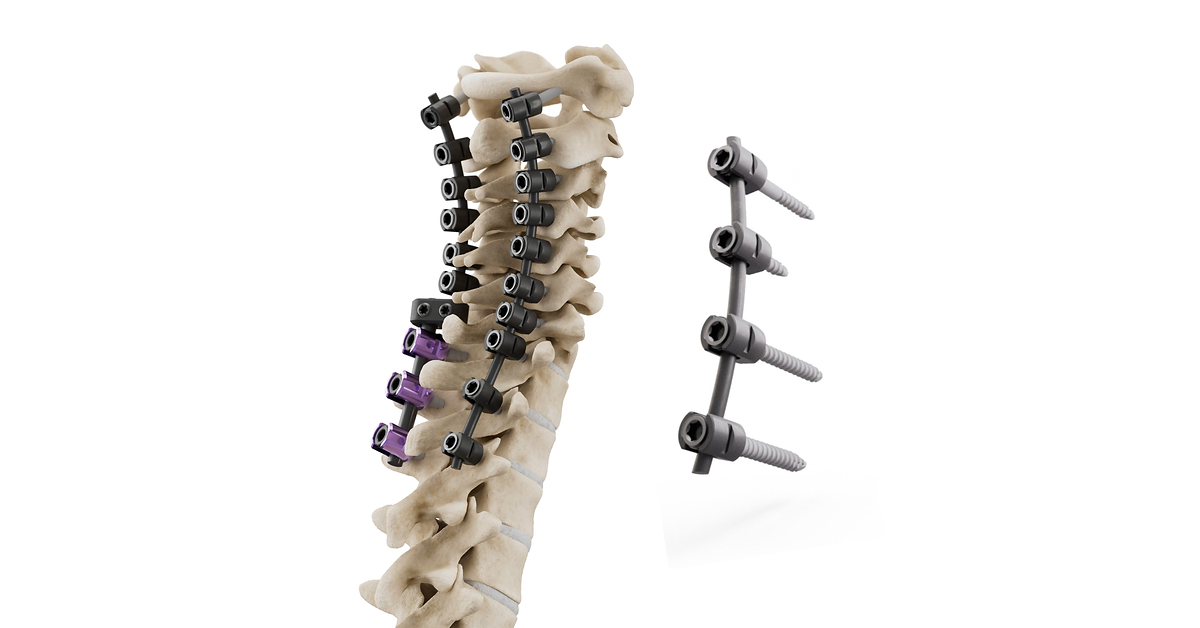
CMS approved a New Technology Add-On Payment (NTAP) for icotec’s CMORE® CT spinal implant system, effective October 1, 2026, potentially providing additional reimbursement to eligible hospitals for qualifying Medicare procedures. The system is designed for posterior cervicothoracic spine stabilization and is made from radiolucent Carbon/PEEK; eligibility and payment are determined by CMS and applicable payer requirements, and icotec does not guarantee specific reimbursement.
Analysis
The key economic point is that NTAP can reduce a hospital’s adoption friction; it does not establish that icotec receives a higher price or that every CMORE CT case qualifies. The immediate effect is therefore a purchasing-enablement signal, not evidence of material revenue. The release is issuer-supplied, and actual economics depend on qualifying diagnoses and procedures, coding, hospital eligibility, and the payment relative to the device’s incremental cost.
Over the next 1–3 months, watch for evidence of hospital ordering and surgeon use rather than treating the designation itself as a demand inflection. If reimbursement meaningfully offsets cost for eligible cases, icotec could gain a foothold in complex cervicothoracic procedures, potentially taking share from established spine implant suppliers such as Medtronic, Stryker, Globus Medical, and Johnson & Johnson’s DePuy Synthes. That remains conditional: clinical preference, purchasing contracts, and availability of compatible systems can outweigh reimbursement. The longer-term differentiator is whether radiolucency translates into demonstrable imaging or treatment-planning benefits and repeat adoption—not the designation alone.
The contrarian read is that the headline may overstate near-term commercial impact: the eligible case pool may be narrow, and hospital reimbursement is not a guarantee of manufacturer revenue. No company identities or tradable tickers were supplied for icotec, so this is not a direct equity catalyst. Reassess if icotec reports adoption, qualifying case volumes, or revenue conversion; the thesis weakens if hospitals do not adopt despite the payment or if eligibility/coding proves restrictive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No direct position based on this announcement alone; icotec has no supplied public ticker, and the reimbursement designation does not establish incremental company revenue.
- Set a 1–3 month watch item for hospital adoption, qualifying procedure volumes, and any disclosed reimbursement-versus-device-cost evidence. Verify CMS eligibility and coding details before underwriting a revenue impact.
- Do not short established spine suppliers on this signal alone. Revisit relative positioning only if credible evidence shows sustained CMORE CT adoption displacing incumbent systems.
- Falsification trigger: limited ordering or case use after the effective date, restrictive qualification in practice, or no evidence that the payment changes hospital purchasing decisions.
More News
- Australia top court rules against coal mine expansion, citing climate harm
- GIC Private Ltd, Medline 10% owner, sells over $721m in shares
- A 32% beat, a +6% jump: the IT solutions name our models picked in July
- Paramount's hard-fought takeover of Warner Bros. Discovery closes Tuesday. Here's how we got here
- Nvidia Is on the Verge of a $6 Trillion Market Value
- Controversial $110 billion mega-merger of Paramount and Warner Bros. finally closes
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Can Hedge Funds Use ChatGPT? A Control Framework
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash