
iQIYI iJOY Conference 2026: Expanding Its Premium Slate with 350+ New Titles and Entering a New Chapter for AI-Powered Entertainment
Source: PR Newswire
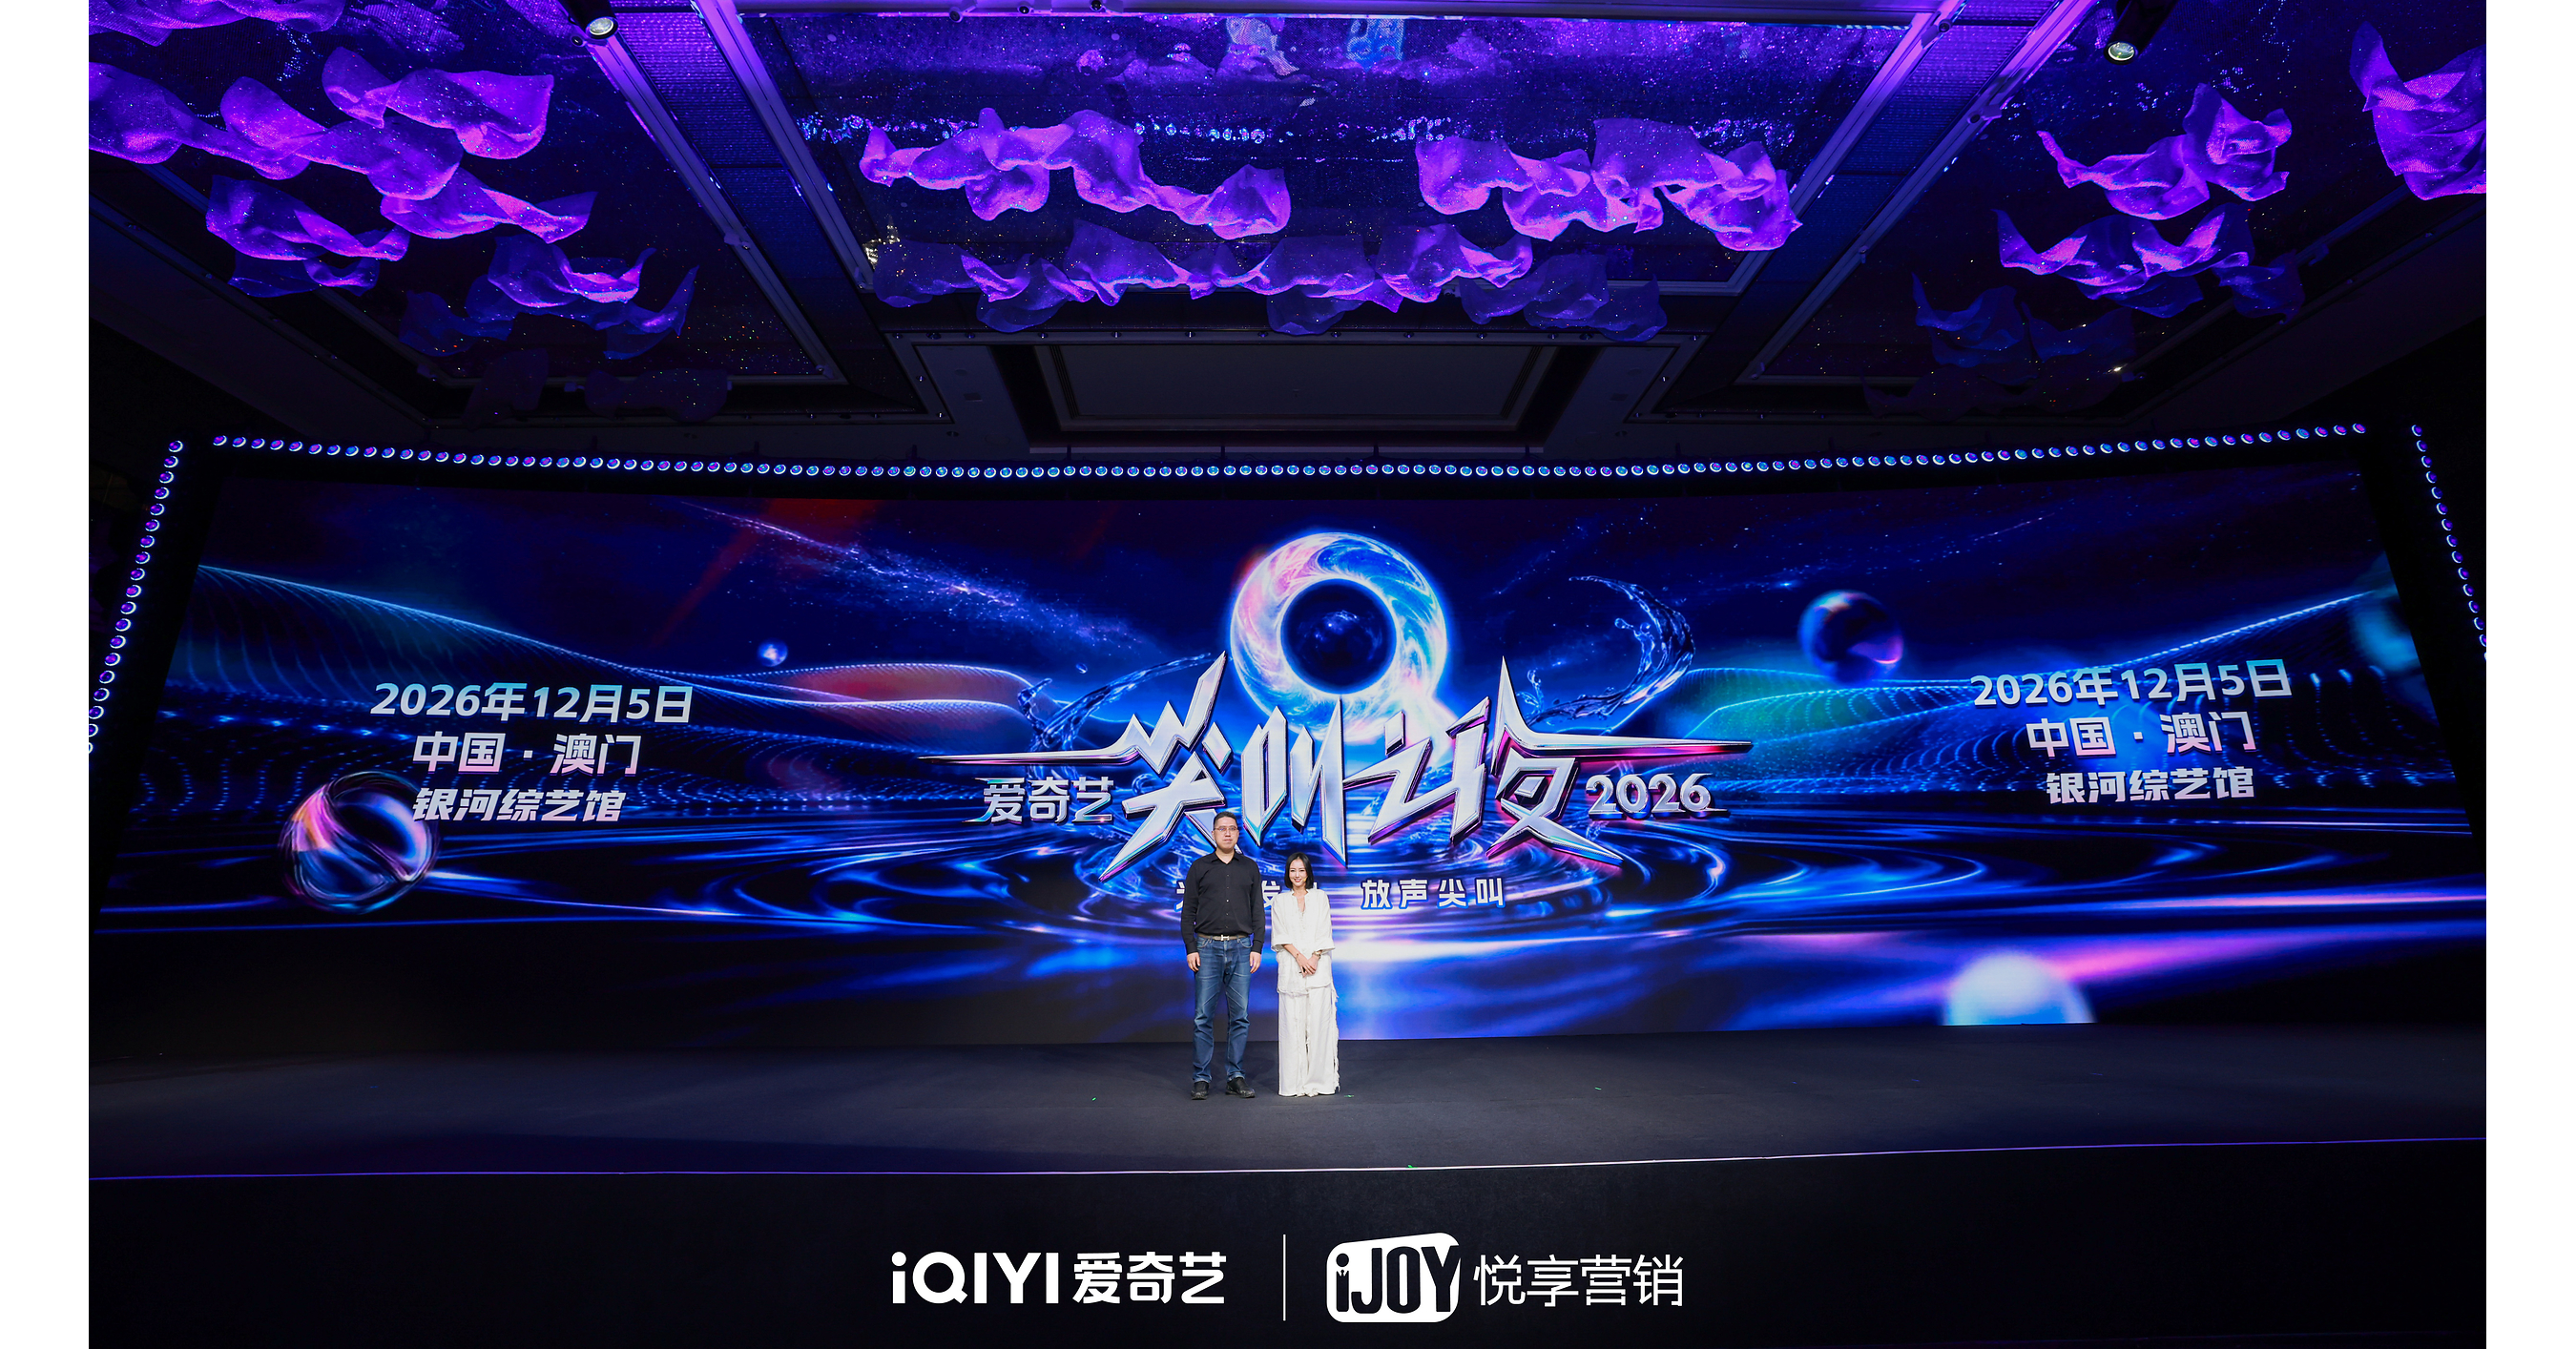
iQIYI unveiled more than 350 titles for 2026-2027 and expanded its All in AI strategy, including its first full-length hybrid AI multi-season drama, "Immortals Over Mortal Love," scheduled for Q4 2026. The company said its long-form AIGC series "The Ferry Man" recouped production costs within its first week and generated over RMB8 million (US$1.19 million) in revenue-sharing earnings in its first month. iQIYI also launched a household-focused big-data marketing system and secured a three-year, 2026-2028 residency for its Scream Night event at Macao's Galaxy Arena.
Analysis
IQ’s strategic upside is not the AI label itself but potential content-cost deflation: if hybrid production lowers episode-level spend without impairing completion rates, the company can expand its content library while holding cash-content spend flatter than revenue. That would improve operating leverage in a business where premium-content amortization has historically constrained margins. The key competitive effect is likely pressure on BILI’s creator economics and on Tencent Video/Youku’s willingness to sustain high-budget exclusivity; incumbent platforms with deeper balance sheets can absorb a pricing or creator-incentive response, limiting IQ’s ability to retain all savings.
Near term, the announcement is unlikely to alter estimates absent evidence that AI-produced formats drive paid-member retention or ad yield rather than merely lower production cost. Over the next 1-3 months, monitor management disclosure on content cash spend, paid-member ARPU, advertising growth, and the conversion rate of AI titles into subscription acquisition; a single low-revenue series is not proof of scalable unit economics. Over 6-18 months, successful AI-enabled micro-drama production could shift bargaining power away from traditional studios and talent, but it also raises censorship, IP-rights, and quality-control risk—any regulatory restriction on training data or creator disputes would erase the presumed cost advantage and prompt multiple compression.
Contrarian view: the market may over-credit AI for an improvement that is more likely to come from disciplined content procurement and advertising recovery. IQ should not rerate toward global AI-software multiples unless it demonstrates repeatable margin expansion and materially lower churn; Chinese streaming remains a competitive consumer-media market, not a recurring software model. The thesis is falsified if quarterly content cash spend rises faster than revenue, paid-member ARPU declines, or management reduces profitability/FCF expectations while scaling creator incentives.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- Maintain IQ as a watch-list long rather than chase the event-driven move. Initiate only after the next quarterly report confirms content-cost growth below revenue growth and stable-to-higher paid-member ARPU; target a 3-6 month rerating on operating-margin expansion, with a stop if management signals renewed content-spend escalation.
- Express relative AI-content adoption through long IQ / short BILI over 3-6 months only if IQ shows improving subscriber retention while BILI’s creator incentives or content costs accelerate. The pair isolates China consumer-internet beta; exit if BILI’s advertising growth materially outpaces IQ’s or IQ’s paid-member base contracts.
- Avoid treating the cited AI-title monetization as an earnings catalyst until management provides production cost, marketing spend, and net revenue-retention data. Set an alert for the first full-quarter disclosure following the Q4 launch; absent demonstrable positive contribution margin, regard AI content as promotional rather than valuation-relevant.
- For broader sector exposure, monitor TCEHY and BABA for competitive spending responses in video. A renewed exclusive-content arms race would be negative for IQ’s margin thesis even if audience engagement improves, and would favor the larger balance sheets rather than IQ.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Facebook found liable as TikTok settles for $100m over user safety
- Boom or bust? The case for and against panicking about 5% yields
- Bond market alarms are ringing on Wall Street. Here's what's ahead
- Shares of Akamai surge after deal with Anthropic. What Wall Street is saying