
YFORE, fournisseur mondial de premier rang, inaugure une usine de fabrication aux États-Unis, à Atlanta
Source: PR Newswire
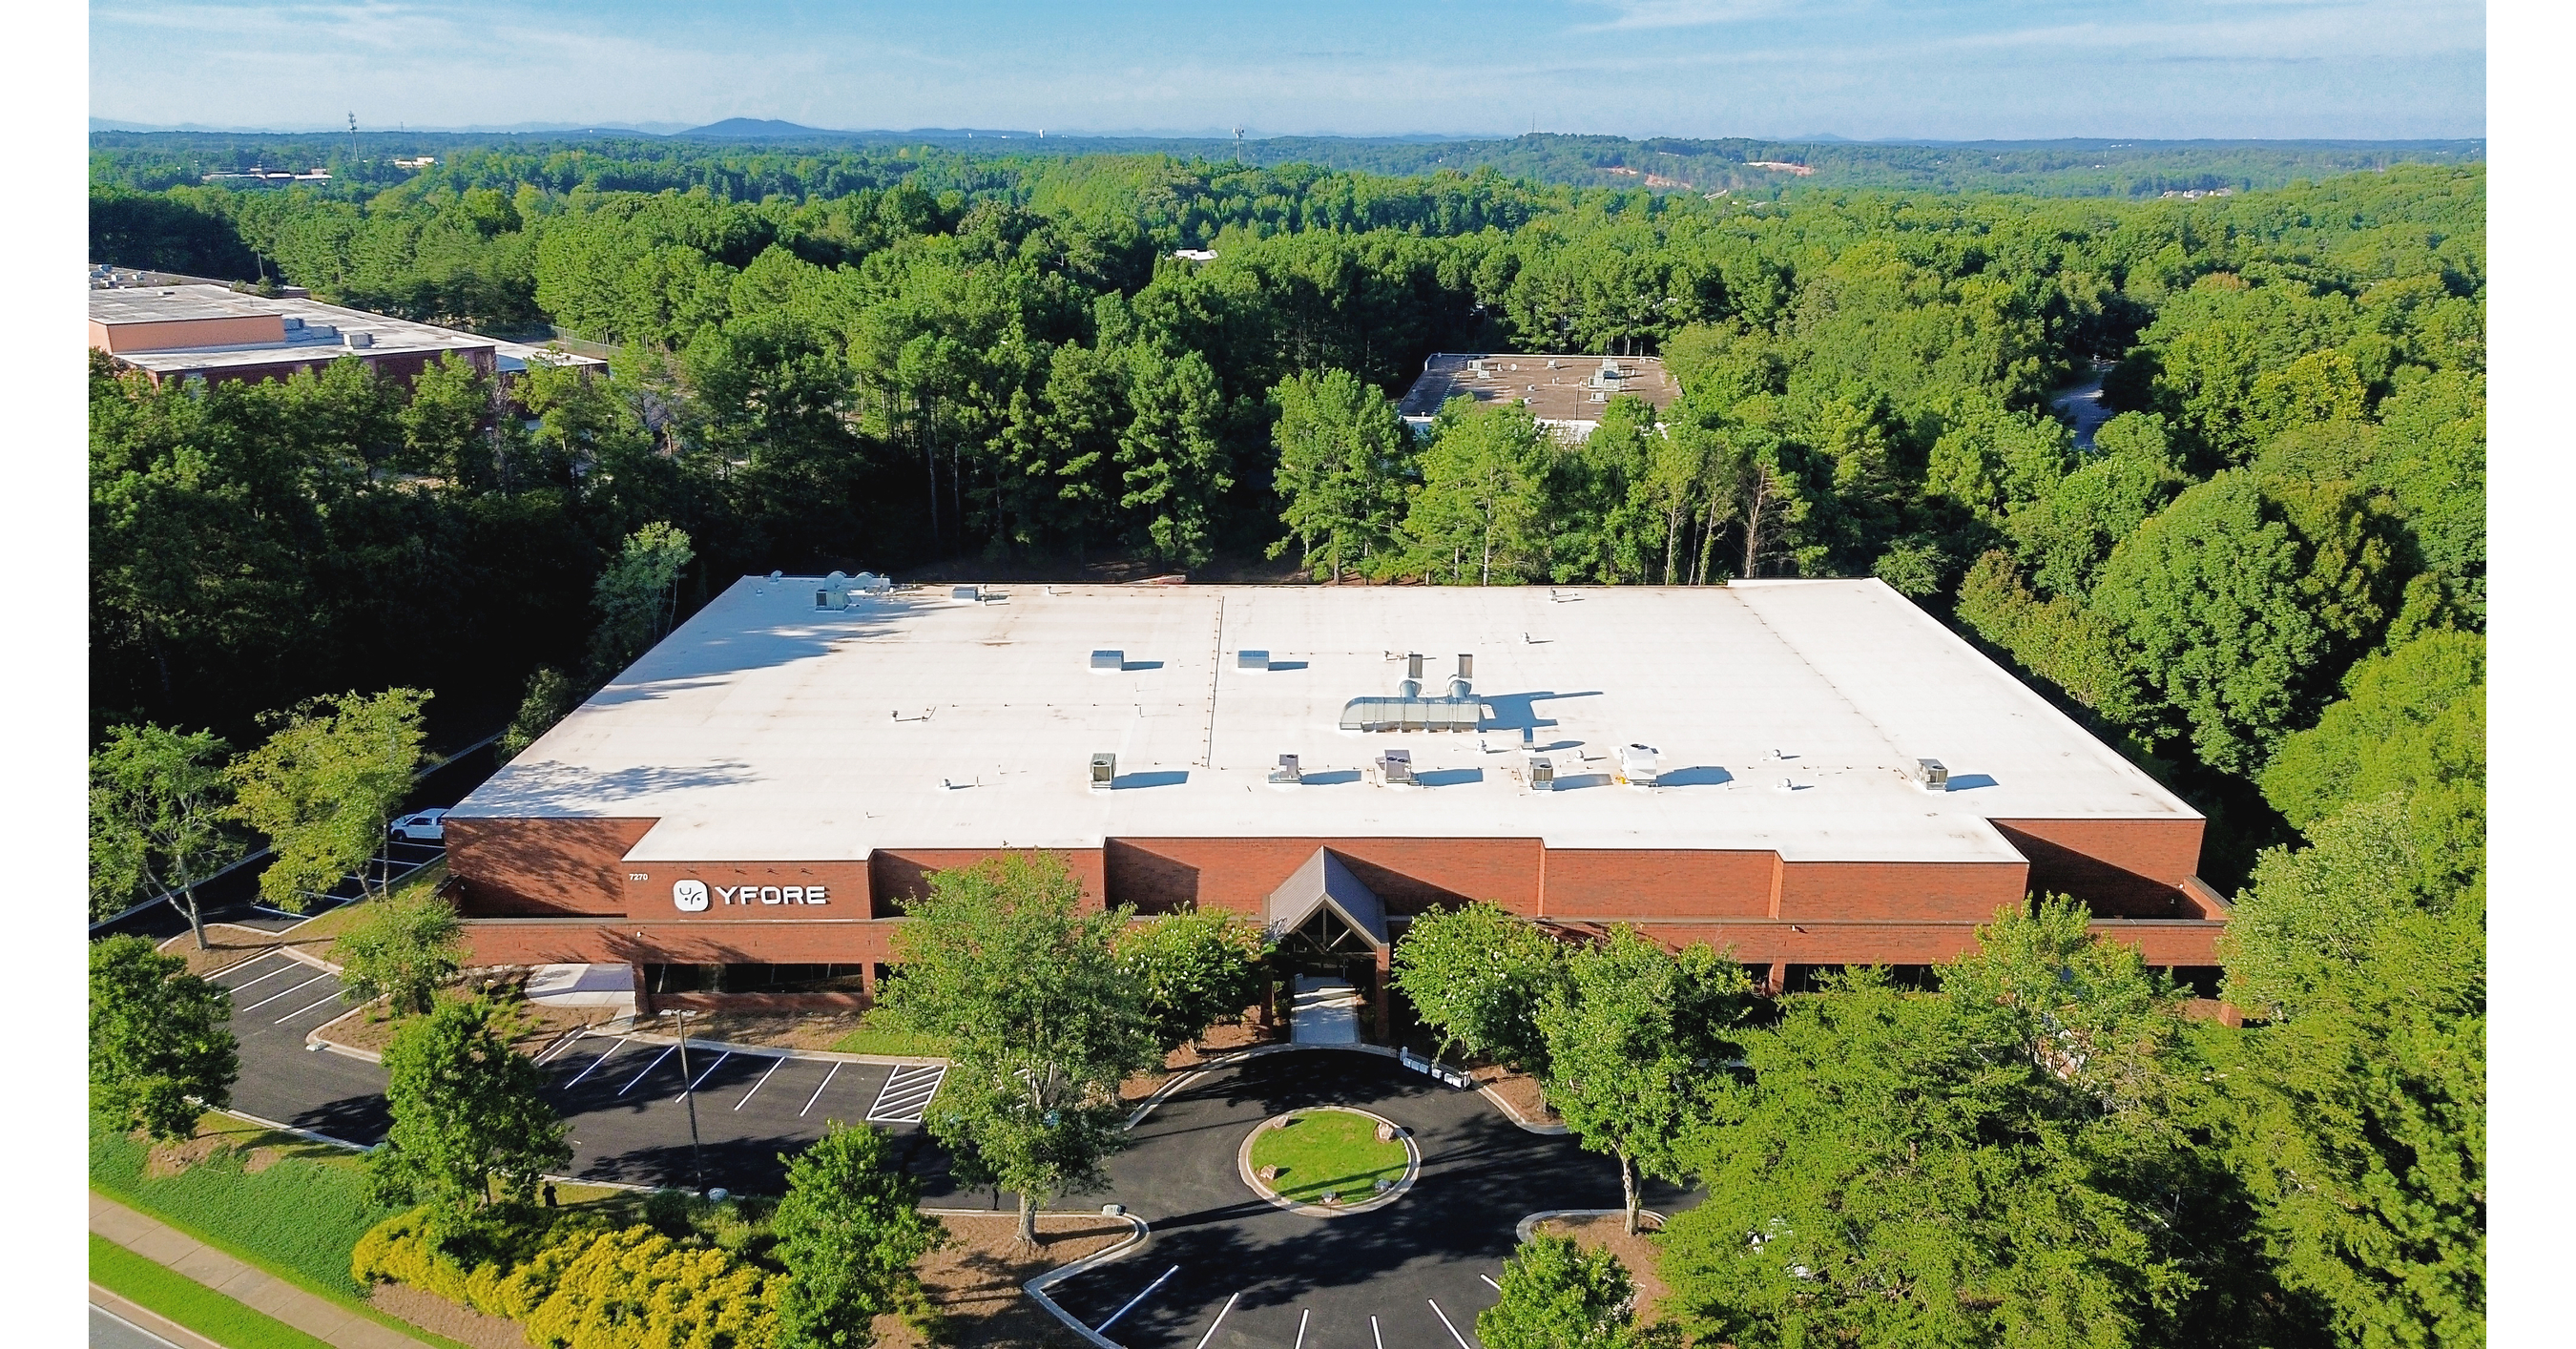
YFORE inaugurated a 62,225 sq. ft. U.S. facility in Suwanee, Georgia, integrating R&D, manufacturing, procurement, sales, and delivery to build more localized, resilient auto supply chains. The company also showcased U.S.-made digital key technologies (BLE/UWB/NFC) and smart mirror and cabin detection systems aimed at improving vehicle intelligence and E-NCAP compliance. While this is a strategic capacity/innovation expansion rather than a financial update, it is likely a modest positive signal for the business and local growth.
Analysis
This is less a capacity story than a qualification story: a U.S. footprint materially lowers the friction cost for OEM sourcing decisions in categories where design-in, service speed, and geopolitical optics matter. The first-order winner is the supplier able to offer local engineering + local assembly; the second-order winner is any OEM seeking a credible China-plus-one sourcing option for 2027-2029 platforms. The likely losers are incumbents with higher-cost legacy North American plants that have been able to defend margin on “integration” rather than differentiated IP.
The competitive pressure is most acute in smart mirrors and digital access, where the bill of materials is not the moat; software, reliability, and validation are. If this new U.S. site helps YFORE win even a few platform programs, the market impact will show up in RFQs and pricing, not in current-quarter revenue, which means the earnings read-through is months away. I would expect the first visible effect to be gross margin pressure for niche auto-electronics suppliers rather than a broad industry volume shift.
The contrarian view is that the market often overvalues “localization” as a universal positive. In reality, local plants commoditize sourcing and can actually intensify price competition because OEMs gain a second source with lower political risk. The key falsifier is whether YFORE converts this footprint into named North American program wins within 1-3 quarters; without that, the site is more strategic signaling than P&L accretion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate standalone trade: use this as a watch item for North American OEM sourcing updates; the stock-level signal is too indirect until program awards are visible.
- Short GNTX on strength over the next 1-3 months if OEM RFQs for digital mirrors/occupant sensing turn more price competitive; thesis is margin compression, not volume loss. Falsifier: no evidence of pricing pressure or margin guidance deterioration by the next earnings cycle.
- Long APTV or LEA as a relative beneficiary of the broader localization trend only on pullbacks; these names can capture incremental North American content demand without relying on a single niche product line. Risk/reward improves if auto build remains stable and tariff risk stays elevated.
- Set an alert for any disclosed YFORE win at GM/Ford/Stellantis/Tesla over the next 1-2 quarters; that would convert this from optics to a real competitive threat and justify a more aggressive short in mirror/access-exposed suppliers.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?
- TikTok CEO sees major scientific breakthroughs from AI within three years
- What the Iran war has done to the world’s energy supply, in charts
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)
- AI Portfolio Monitoring: Build an Alert Policy Analysts Can Audit