
Life Time Expands Ultra Fit Class Across North America as Science-Backed Sprint Training Gains Momentum
Source: PR Newswire
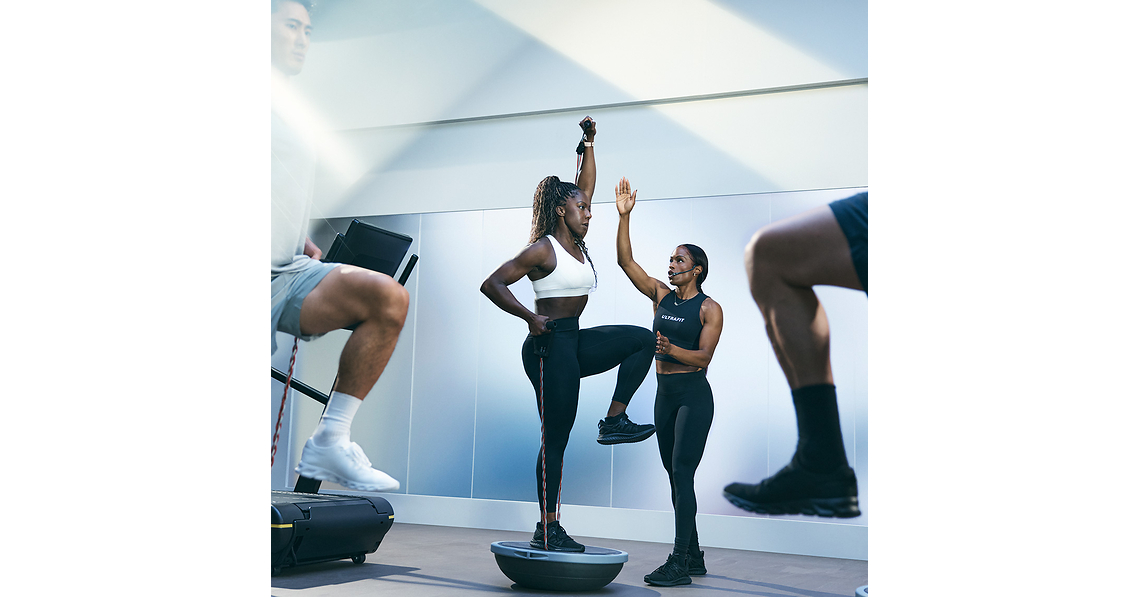
Life Time (LTH) is expanding Ultra Fit, its high-intensity Signature Group Training format, adding 200+ newly certified coaches and new classes across 195+ clubs as member demand rises. The company says Ultra Fit classes are increasingly filling, with higher class sizes over the past two years, and that the format integrates sprint interval efforts with strength, stability and balance plus heart-rate guidance. The update is supportive for Life Time’s programming traction, but it is unlikely to meaningfully move the stock beyond routine/sector-light news.
Analysis
This is more about operating leverage than a new product launch. For LTH, every incremental class that fills with existing members is high-margin throughput on a fixed club base: better studio utilization, stronger perceived value, and lower churn risk without meaningful capex if floor space is already flexible. The real upside is in retention and pricing power over the next 2-4 quarters, not immediate revenue per class.
The competitive read-through is negative for boutique fitness operators that rely on paid, coach-led intensity as their core proposition. If LTH can package the same “high-intensity” format inside a broader membership, it pressures standalone concepts like XPOF franchises on value-for-money and convenience. Planet Fitness is less exposed, but the broader implication is that premium clubs can keep adding low-marginal-cost programming while smaller studios must keep discounting or spending more to defend attendance.
Contrarian view: the market may be overestimating how much member demand converts into earnings. The article is a usage signal, but not yet proof of higher net sign-ups or materially higher dues growth. The key watch item is whether class expansion lifts retention and ancillary spend enough to offset coach certification, labor, and scheduling complexity. If management does not show same-club revenue acceleration or margin expansion in the next 1-2 quarters, the narrative fades quickly.
Tail risk is cannibalization: if members substitute Ultra Fit for paid personal training or other premium offerings, the economics are weaker than the marketing suggests. Falsify the bullish thesis if LTH reports flat/declining member engagement metrics, rising labor costs, or no improvement in retention/ARPU by the next two earnings prints.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Long LTH on pullbacks over the next 1-2 weeks; target a 3-6 month thesis on retention and same-club revenue, with downside limited if the stock already discounts modest consumer strength.
- Pair trade: long LTH / short XPOF for 1-3 months; thesis is that integrated premium clubs can monetize fitness trends inside existing memberships better than franchise studios can defend traffic and pricing.
- Do not chase on the press-release spike; wait for the next quarterly print to confirm whether class expansion is translating into same-club sales and margin expansion before adding risk.
- Set an alert on LTH if management does not show higher member engagement or ARPU in the next two earnings cycles; that would likely mark the point to fade the move.
- If you want convexity, use a modest call spread in LTH into the next earnings event rather than stock, because the upside is operationally real but likely incremental rather than transformational.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Build an Automated Research Process for a Fund
- Weekly Update: AI-Powered Report Editing, Investor Relations, and Enhanced Search