
Stirlingshire Investments Appoints Former LPL Financial CEO Dan Arnold as Executive Chairman
Source: PR Newswire
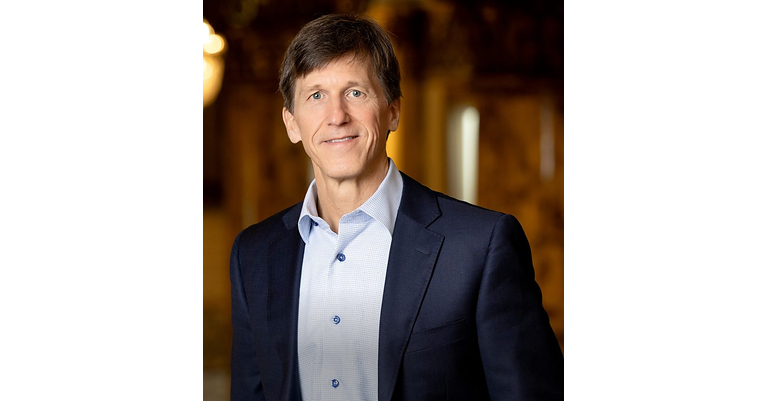
Stirlingshire Investments appointed former LPL Financial President and CEO Dan Arnold as Executive Chairman, tasking him with advisor recruitment, operational execution, partnerships, and scaling growth initiatives. The firm is expanding its AI-native Stirling One wealth-management platform, which integrates onboarding, trading, portfolio management, compliance, tax optimization and advisor tools, while offering advisors a 100% payout and zero platform-expense model. The appointment strengthens leadership credibility for a private wealth-management platform but is unlikely to have broad public-market impact.
Analysis
This is not an investable catalyst for the listed incumbents today: the appointing firm is private, no advisor-count, assets-under-management, funding, pricing economics, or audited retention data are supplied, and the operating-model claims remain promotional. The only near-term public-market read-through is modestly negative for LPLA at the margin because a former CEO’s recruiting relationships could lower switching friction for a targeted cohort of independent advisors; however, a leadership hire alone does not establish a scalable custody, clearing, service, or compliance infrastructure.
The relevant competitive question is whether a 100% payout model is economically durable once technology support, supervision, errors-and-omissions exposure, transition packages, and advisor-service costs are included. If it is subsidized by external capital, it could pressure recruiting concessions and retention costs at LPLA and, secondarily, broker-dealer platforms; if it is funded through client-level fees or product economics, advisor adoption may be materially weaker than the headline payout suggests. This is a longer-cycle threat, with any measurable impact likely appearing first in LPLA’s recruited advisor count, net new assets, and payout ratio over 2-6 quarters rather than in near-term earnings.
The contrarian view is that incumbents may benefit from a new entrant’s recruitment marketing: advisor due diligence tends to elevate the value of established custodial integration, balance-sheet support, and proven compliance controls. HOOD and SOFI are not clean peers—their wealth economics skew toward self-directed or digital-client acquisition rather than independent-advisor platform monetization—while STT and LSEG have little direct revenue sensitivity. Treat this as a competitive-intelligence alert, not a directional catalyst.
Falsification for the benign-incumbent thesis would be independently verified rapid advisor/AUM migration, disclosed institutional custody and clearing partnerships, and evidence that the entrant can maintain its payout model without elevated losses or funding needs. More specifically, a sustained deceleration in LPLA net new assets or an unexpected rise in its advisor payout/recruiting expense over the next two earnings cycles would warrant reassessment.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No immediate position based solely on this release; avoid treating it as a tradable LPLA event absent disclosed advisor transitions, AUM, financing, or custody/clearing arrangements.
- Create a 1-3 month LPLA watchlist: review quarterly recruited advisors, net new assets, advisor retention, payout ratio, and recruiting expense. Escalate to a short/underweight review only if net new assets decelerate materially versus guidance while compensation costs rise.
- Maintain any existing LPLA exposure hedged through earnings if competitive recruiting becomes a broader theme; a modest LPLA underweight versus RIA/asset-manager proxies is preferable to a HOOD or SOFI short, which have weak fundamental linkage.
- Monitor private-market signals over 6-18 months: named custodial partners, adviser count, AUM, client fee schedule, capital raises, and regulatory filings. Verified scale plus sustained 100% payout would be the trigger to reassess platform-margin risk across independent wealth managers.
More News
- 5 of the Fastest-Growing Stocks in the Market
- The Growth of the Tokenized Equities Market Is Off-the-Charts. Here's What Crypto Investors Need to Know.
- Robinhood director Baiju Bhatt sells $5.16M HOOD shares
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Biotech stocks are surging. How investors can play the new drug innovation boom
- AI funding fears rattle Wall Street. Here's how we're adjusting our portfolio