
1 Reason Why Netflix Stock Looks Oversold
Source: fool.com
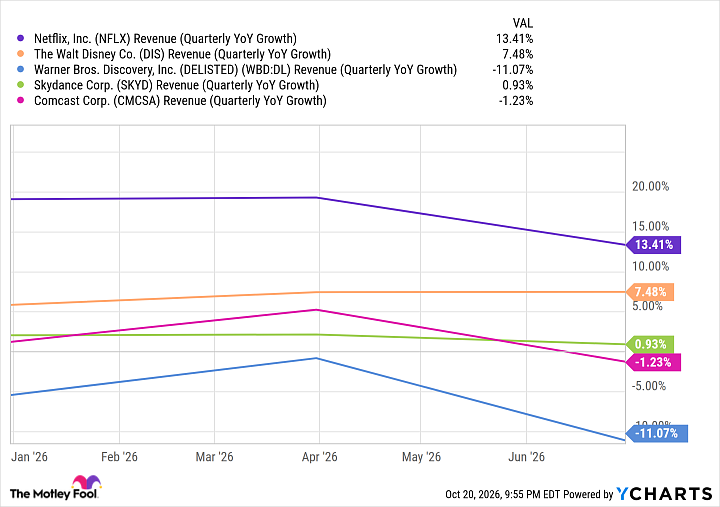
Netflix shares are down 31% year to date and fell 6% after earnings, while viewer share declined from 8.8% to 7.8% and viewing hours rose just 2% in the first half. Q3 revenue nevertheless increased 11.8% to $12.9 billion, and EPS rose from $0.59 to $0.87, partly because of the timing of lower content spending. Analysts forecast 11.2% revenue growth to $56.9 billion in 2027; the article argues that Netflix is growing faster than media peers and looks attractively valued, while noting that growth may slow as the March price increase rolls off.
Analysis
The key issue is whether monetization is outrunning audience engagement. Price increases can sustain revenue while masking weaker viewing share; when the March increase laps, growth will depend more visibly on subscriber adds, ad-tier economics and further pricing power. The reported response to pricing is not enough to establish low churn without cohort or cancellation data. EPS is also a noisy signal this quarter: content-spending timing may reverse, so assess normalized cash content costs and operating margins rather than extrapolating the per-share improvement.
Over 1–3 months, the next evidence point is whether engagement and subscriber metrics stabilize and management can support its forward growth outlook without another pricing contribution. Over 6–18 months, sustained share losses to YouTube would weaken Netflix’s ability to raise prices, even if revenue remains ahead of legacy media peers. Alphabet may capture more attention and ad inventory, but YouTube viewing-share gains do not translate mechanically into Netflix subscription losses.
The contrarian case is that the sell-off may overstate near-term risk because Netflix can monetize a smaller share of viewing more effectively than diversified peers. But calling the stock oversold is not a catalyst: the thesis requires proof that pricing has not impaired retention and that content costs normalize without margin deterioration. A reversal in engagement or a guidance cut would invalidate the recovery case.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- Treat NFLX as a conditional, staged-long candidate rather than a confirmed value trade. Prefer adding only after the next report shows stable engagement and retention alongside growth that is not primarily price-led; verify churn, net additions and ad-tier contribution, which are not provided here.
- Do not extrapolate the quarter’s EPS growth. Track content cash spending and normalized operating margin; a spending rebound that absorbs revenue growth would weaken the earnings-quality thesis.
- Use GOOG as a relative watchlist hedge against the attention-share thesis, not as a direct streaming pair: YouTube can benefit from engagement shifts, but the article provides no evidence on incremental monetization or stock-relative valuation.
- Falsification: reduce or abandon the NFLX recovery thesis if viewing share continues to fall and the post-price-hike period brings weaker retention, or if management lowers growth expectations as the price increase laps. Reassess legacy-media shorts separately; their balance-sheet and segment exposures are not interchangeable.
More News
- Asia stocks rebound as SpaceX, Super Micro results lift chipmakers
- Netflix Sales Growth to Decline for Fourth Quarter in a Row
- France to deploy troops, admits to failures over weekend unrest
- SpaceX posts first operating profit as public company as AI revenue nearly triples to $7.6 billion—cruising past Starlink
- AI rally fades away from Wall Street as a tiny IPO makes big waves
- Nscale Anthropic in AI Computing Talks