
Furniture China i Maison Shanghai 2026 zaczynają końcowe odliczanie
Source: PR Newswire
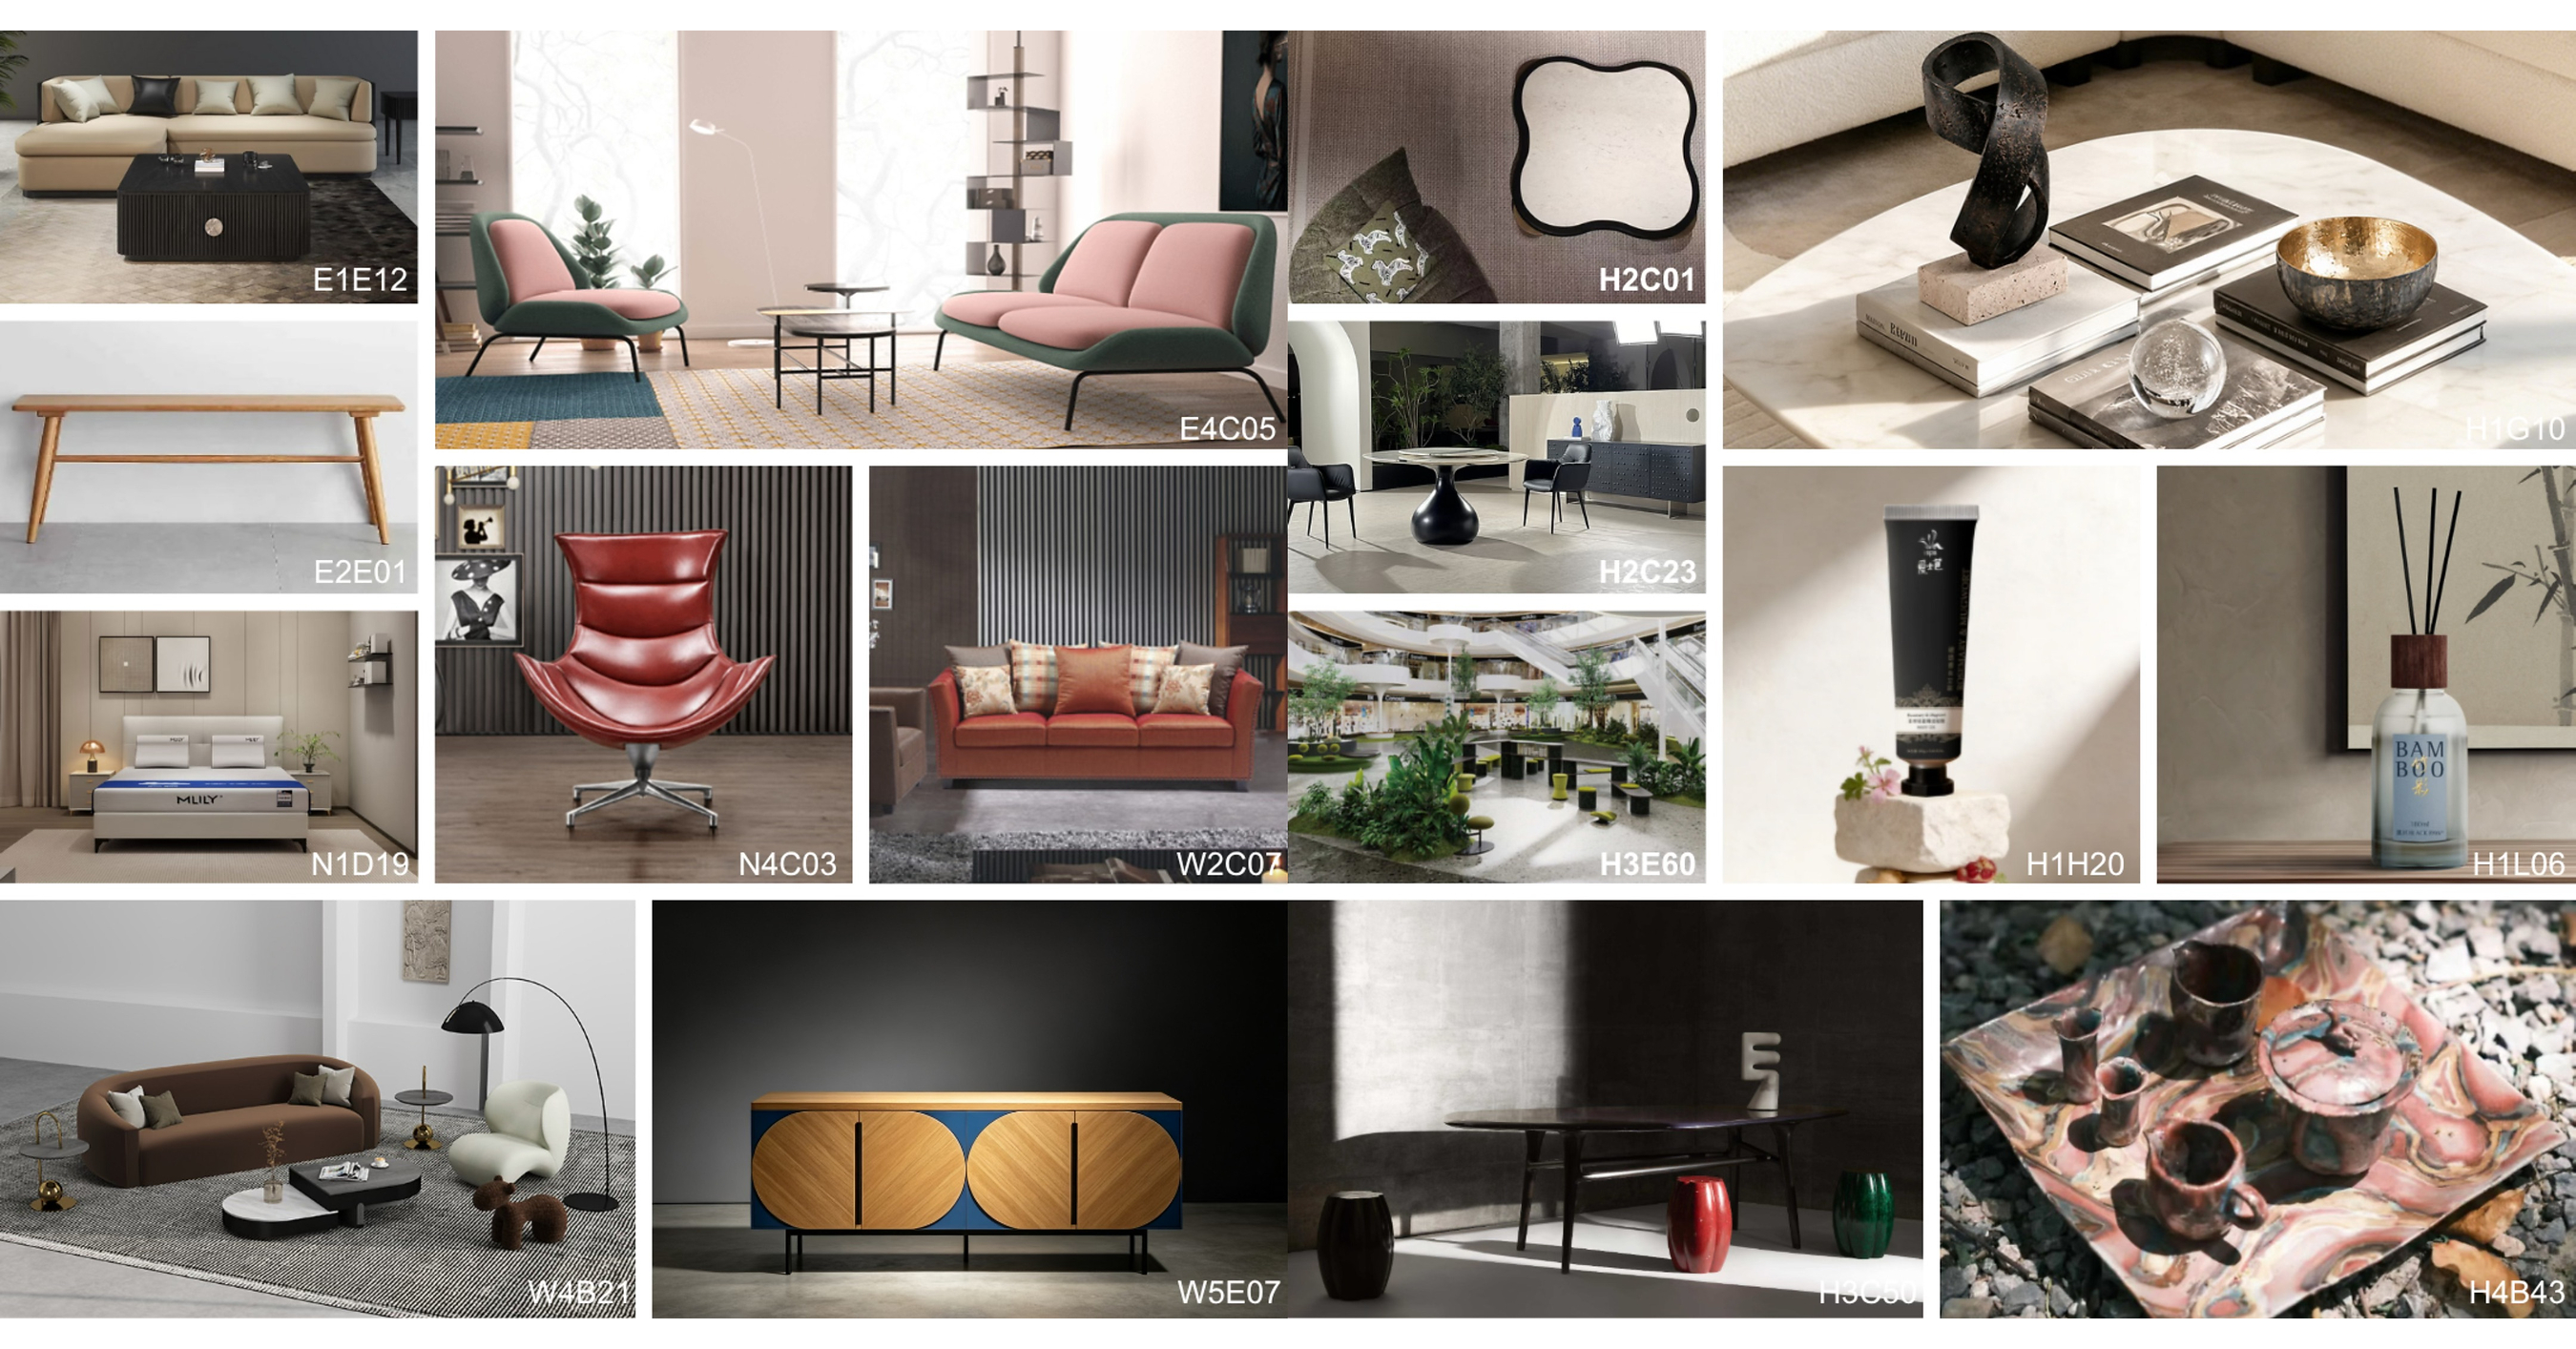
Furniture China (8–11 Sep 2026) and Maison Shanghai (7–10 Sep 2026) run back-to-back in Shanghai, jointly covering 350,000 m² with 3,200+ brands and an estimated 200,000 industry visitors. The events emphasize furniture sourcing and supply-chain offerings (including materials/components) alongside design, lifestyle, and “smart” production approaches. The article provides practical info for overseas buyers (including an Overseas Buyer Lounge and registration through the DTS FurnitureChina App), but does not signal any financial or regulatory market-moving change.
Analysis
This is not a clean macro or single-name catalyst; it is a channel-check on whether global buyers are still willing to source through China despite tariff and geopolitics noise. The near-term market read-through is for companies with the most exposed procurement mix: furniture retailers, import-heavy home-goods sellers, and contract manufacturers that need volume to keep factories utilized. If attendance is real, the bigger second-order effect is not end-demand growth but better pricing power for buyers and faster SKU turnover, which can compress margins for fragmented suppliers.
Over the next 1-3 months, the relevant signal will be whether management teams in home-furnishings, ecommerce furniture, and commercial-fitout mention improved quote activity, shorter sourcing lead times, or lower inbound costs. That would favor names with working-capital discipline and scale procurement over smaller branded manufacturers that cannot flex cost as quickly. Conversely, if the fair becomes a discounting event, it likely reinforces deflation in the supply chain rather than a volume recovery.
Contrarian view: the consensus may overestimate trade-show enthusiasm as a demand indicator. In this segment, large attendance often means competitive intensity is rising and buyers are shopping price, not necessarily that final consumption is improving. The structural winner over 6-18 months is whoever captures margin from supply-chain optionality, not whoever boasts the biggest booth count; the falsifier is a clear improvement in order conversion and 2027 guidance across furniture demand proxies, not just upbeat PR from exhibitors.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.05
Key Decisions for Investors
- No immediate directional trade; use the event as a watchlist catalyst only. Wait for September/October commentary from furniture and home-goods management teams before putting capital to work.
- If post-event checks show stronger buyer traffic and actual order conversion, consider a tactical long WAYFAIR (W) vs. short XRT for 1-3 months: W has the most operating leverage to lower sourcing costs and assortment breadth, while XRT dilutes the furniture signal.
- If the fair mainly drives price competition and discounting, short a basket of weaker furniture manufacturers/brands such as LEG and HNI against XHB for 2-4 months; thesis breaks if Q3 margins hold and inventory turns improve.
- Set an alert on gross margin guidance and inventory days from home-furnishings names in the next earnings cycle. If procurement savings do not show up by then, the sourcing-theme thesis is invalid.
More News
- Is AI the new China Shock?
- Why is T-Mobile stock tumbling today?
- India calls JD Vance's comments about immigrants 'deeply offensive'
- Why is Verizon stock sliding today?
- Wall St futures gain as oil slips; telecoms pressured by SpaceX spectrum deal
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for CFA Charterholders: An Evidence Standard
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data