
SpaceX: The Boldest Bet On Wall Street (Rating Upgrade)
Source: seekingalpha.com
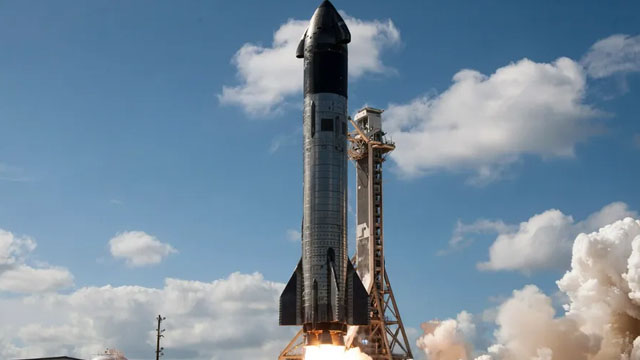
SpaceX was upgraded to Buy following a reported $1.11B-per-month AI hosting contract and reinforcement of its $100B ARR target. Confirmed pricing of $30-$50 per watt supports strong AI-compute demand and the company’s revenue-growth outlook. SpaceX is targeting its first orbital-compute satellite launch in 2027, with anticipated cost parity versus terrestrial data centers.
Analysis
The key valuation transmission is not the headline revenue target but whether contracted compute capacity converts into durable, financeable cash flow. Any orbital-hosting premium would require customers to accept latency, service-continuity, insurance, and launch-replacement risks that terrestrial hyperscale providers largely avoid. Until counterparty names, contract duration, cancellation terms, power-delivery guarantees, and capex funding are independently disclosed, the claimed economics should be treated as a narrative catalyst rather than an earnings-quality catalyst.
Near term, the strongest listed read-through is likely terrestrial AI power and cooling infrastructure rather than orbital compute: VRT, ETN, CEG and VST benefit if incremental AI demand remains supply-constrained regardless of where a longer-dated workload is ultimately hosted. Over 6-18 months, a credible space-based compute roadmap could be strategically negative for marginal data-center developers and merchant power projects whose underwriting assumes uninterrupted growth in hyperscaler load; however, it is unlikely to displace latency-sensitive inference or enterprise workloads on that horizon.
The contrarian view is that investors may capitalize a 2027+ option too early. The first meaningful falsification point is not launch timing alone, but demonstrated delivered compute availability, customer renewal behavior, and unit economics after redundancy, ground-station, depreciation, and satellite replacement costs. A delay, a lower realized revenue-per-watt outcome, or reliance on subsidized/internal demand would justify sharp multiple compression in any SpaceX-linked vehicle because the implied growth duration is doing most of the valuation work.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- Do not initiate a directional position in SPCX until the instrument's legal exposure, liquidity, NAV methodology, and actual ownership of SpaceX are verified; treat it as an event-driven watch item, not a direct operating-company proxy.
- For a 1-3 month AI-demand expression, prefer a basket long VRT and ETN versus a short position in a diversified data-center REIT basket (DLR/EQIX) only after confirming relative valuation and borrow: infrastructure suppliers monetize committed buildouts earlier, while REITs retain power-cost and funding-rate sensitivity.
- Maintain long CEG or VST as the cleaner 6-18 month power-scarcity hedge, with position sizing reduced if forward power curves soften materially or hyperscaler capex guidance is cut; the thesis is falsified by declining contracted load growth rather than orbital-compute headlines.
- Set an alert for independently disclosed customer contracts, satellite replacement assumptions, and delivered cost per usable compute-hour. A verified multi-year external contract with cancellation protection would be a catalyst to revisit SpaceX-linked exposure; launch announcements without these data are insufficient.
More News
- US official says upcoming spectrum auctions could generate more than $100 billion
- Status Of Anthropic IPO As AI Fears Mount
- Anthropic IPO Date: What Investors Need to Know Before It Prices
- X will now let U.S. users trade via cashtags
- AI labs want in-house auditors — but maybe they should shut the front door first
- What the Anthropic IPO Means for Amazon and Alphabet Investors