
APPLETON ESTATE'S HEARTS COLLECTION 1999 RETURNS AFTER FIVE MORE YEARS IN CASK
Source: PR Newswire
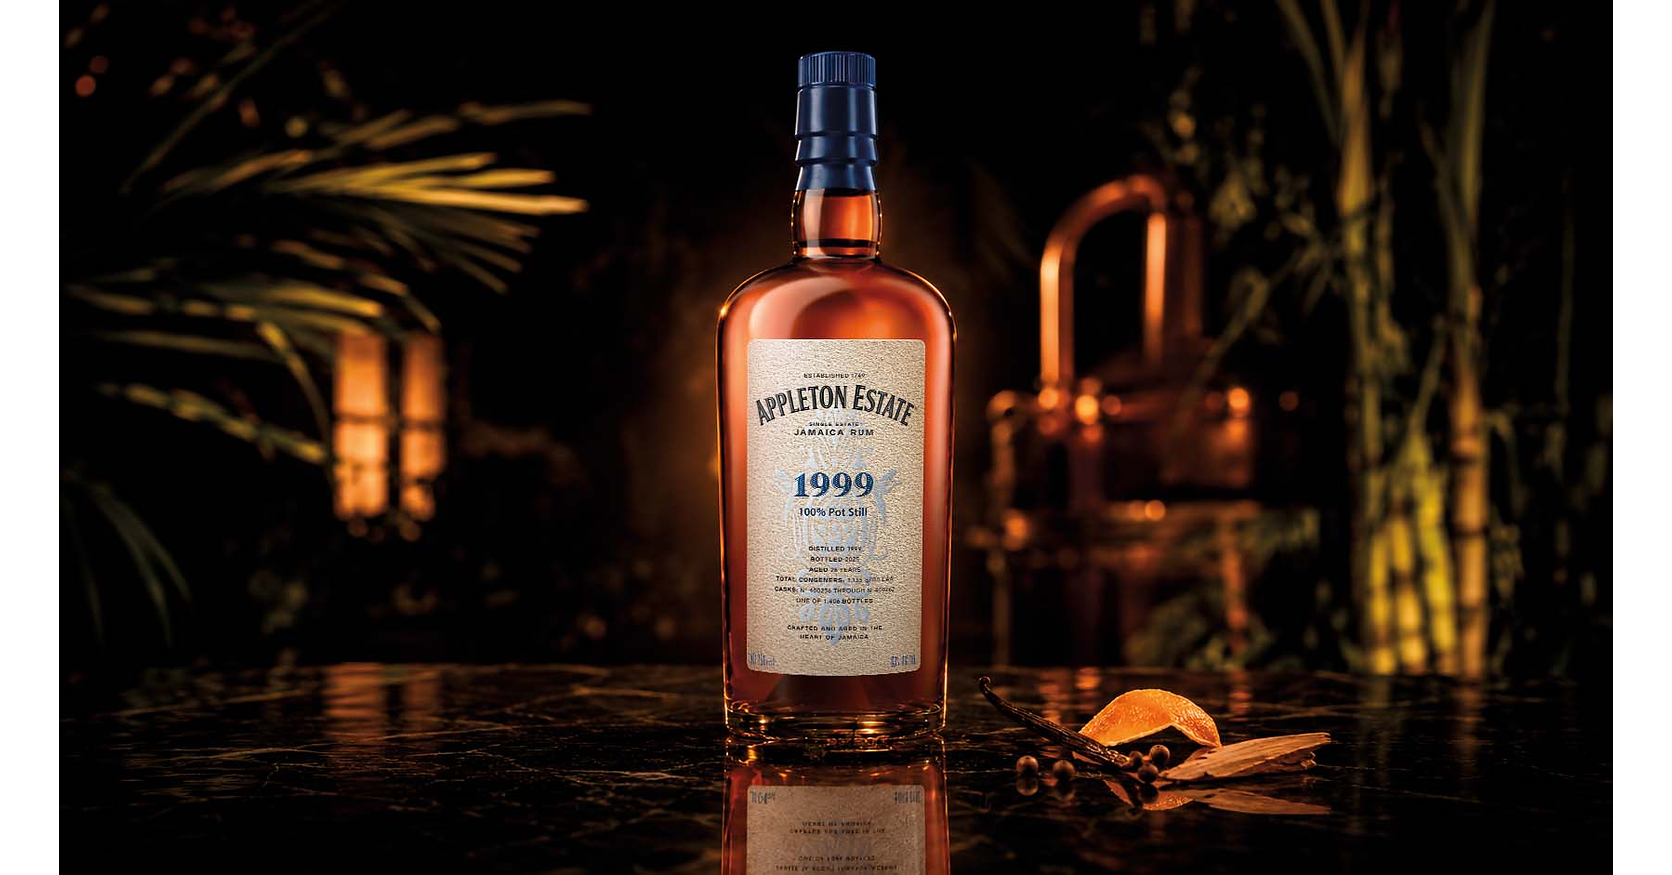
Appleton Estate will launch its 2026 Hearts Collection 1999 in select premium U.S. retailers in October at an approximately $500 SRP. The 26-year-old limited-edition Jamaican rum was drawn from only 10 casks, reinforcing the brand's positioning in collectible ultra-premium spirits. The release is a niche product launch with limited expected financial impact for parent Campari Group.
Analysis
This is strategically useful for CPR's luxury-brand positioning but immaterial to consolidated earnings: a micro-allocation of scarce inventory at a high price point cannot alter group revenue or margins on its own. The more relevant signal is whether Campari can use collectible releases to lift the price architecture and trade consumers into Appleton's broader aged-rum range, where recurring volume and mix—not auction-like scarcity—can affect earnings over the next 6-18 months.
The key second-order benefit is brand halo in an increasingly premiumized brown-spirits shelf, supporting distributor attention and reducing reliance on promotional activity for core Appleton SKUs. However, ultra-premium rum remains a narrow collector category and faces competition for affluent consumers' discretionary spend from Scotch, Japanese whisky and cognac; a sell-through result would be marketing validation, not evidence of broad-based consumer-demand acceleration.
For CPR, the near-term valuation driver remains organic sales growth and margin delivery across larger aperitif and agave franchises. Investors should treat this release as a low-cost test of pricing power and direct-to-consumer demand capture; its relevance rises only if management subsequently cites sustained Appleton premiumization, improving US depletion trends, or measurable mix expansion in results.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this launch: the likely revenue contribution is de minimis relative to CPR, while the press-release framing provides no independently verifiable sell-through or margin data.
- Maintain CPR as a watch-list long for the next 1-3 months; upgrade only if quarterly reporting shows accelerating Americas organic sales alongside gross-margin expansion and management identifies Appleton as a meaningful mix contributor.
- Use a 6-18 month relative-value framework: long CPR versus a broad European staples proxy only if premium-spirit pricing holds without higher promotional spending. Falsify on a material cut to organic-growth guidance, rising inventory/distributor destocking, or margin contraction despite price increases.
- Monitor US premium-rum retail depletion and secondary-market pricing for the release over 30-90 days. Rapid discounting or weak allocation uptake would indicate scarcity-led demand is not transferring to the core franchise and argues against attributing incremental multiple support to Appleton.
More News
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
- Markets slip on dollar pressure, but this IT stock is up 10% today