
Glidewell Announces Unlimited Lab Design Service Exclusively for fastmill.io(TM) Owners
Source: Newswire
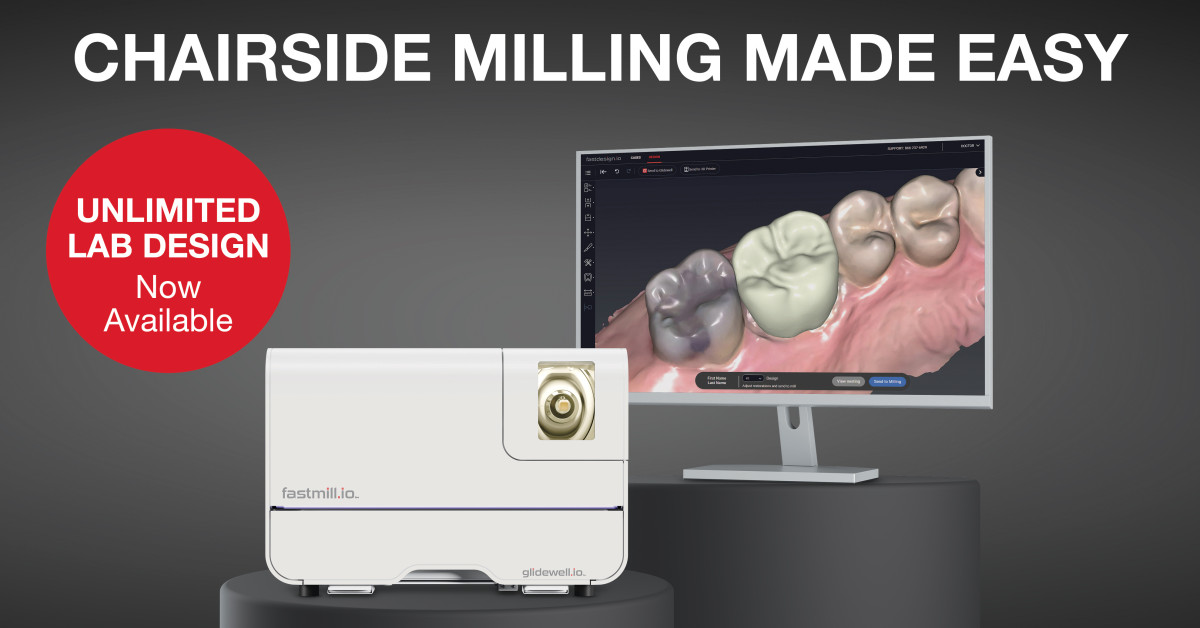
Glidewell launched Unlimited Lab Design for fastmill.io in-office mill owners, bundling unlimited restoration-design support without a per-design fee. The service aims to enable same-appointment dental restorations by having Glidewell technicians return single-unit crown designs in an average of 15 minutes, eliminating practices' need to learn CAD software. The redesigned fastmill.io system also includes software, a design station, one-year warranty, training and unlimited support.
Analysis
The strategic significance is not the milling hardware but Glidewell's attempt to remove the labor and workflow bottleneck that suppresses chairside adoption. A bundled outsourced-design layer can increase utilization of installed systems and lower practice switching costs, potentially shifting the competitive basis from equipment specifications toward recurring workflow support, turnaround reliability, and consumables. This is most relevant to Dentsply Sirona (XRAY), whose CEREC ecosystem carries substantial in-office workflow complexity, and to Envista (NVST) and Straumann (STMN.SW), which compete for digital-treatment budgets through scanners, software, and restoration workflows.
The near-term read-through for listed dental names is limited: Glidewell is private, the incremental service economics, installed-base size, attachment rate, and whether existing users pay a subscription are undisclosed. Over 6-18 months, however, successful adoption could pressure premium CAD/CAM pricing and make scanner interoperability more valuable; this is marginally supportive for scanner-channel participants such as Align (ALGN) and potentially distributors such as Henry Schein (HSIC), if lower workflow friction expands practice capital spending. The key falsifier is evidence that outsourced design creates turnaround delays or remakes that negate chair-time savings; absent disclosed utilization and retention data, this is a competitive watch item rather than a tradable earnings catalyst.
Consensus may overestimate the disruption to incumbents because same-day dentistry already depends on scanning quality, case selection, staff workflow, reimbursement economics, and patient volume—not solely CAD proficiency. The more likely initial outcome is expansion of the addressable market among lower-complexity general-practice users rather than rapid displacement of established premium systems. Any margin impact on public competitors would require broad price matching or rising customer-acquisition costs, neither of which should be assumed from a single vendor announcement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No immediate directional trade: treat this as low-impact private-company product news until Glidewell discloses system placements, design-service attachment rates, turnaround performance, or consumables utilization.
- Add XRAY to a 1-3 quarter competitive-risk watchlist; reassess for a short or underweight only if management cites chairside CAD/CAM discounting, slower CEREC placements, or increased software/service incentives. A clean quarterly maintenance of digital-sales growth and gross margin would falsify the bearish read-through.
- Monitor ALGN scanner volumes and HSIC dental equipment commentary over the next two earnings cycles for evidence that reduced workflow complexity is expanding scanner and in-office restoration adoption. Consider a modest long only on independently confirmed unit-growth acceleration, not on this announcement alone.
- For relative-value positioning, prefer avoiding a broad dental-equipment short: any increase in digital workflow adoption could lift category spending before competitive pricing pressure emerges. The relevant 6-18 month signal is whether incumbents respond with bundled design support or lower recurring software fees.
More News
- Nvidia Faces Questions Over China AI Chip Smuggling Cases
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Markets slip on dollar pressure, but this IT stock is up 10% today
- One of our most recent defensive buys cleared a hurdle and its stock jumped
- AI’s biggest players promise to police themselves at the White House
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Can ChatGPT or Claude Replace a Research Platform?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance