
The 94th CMEF, the World's Leading Medical Device Industry Event, Set to Open in Beijing Oct. 21-24
Source: PR Newswire
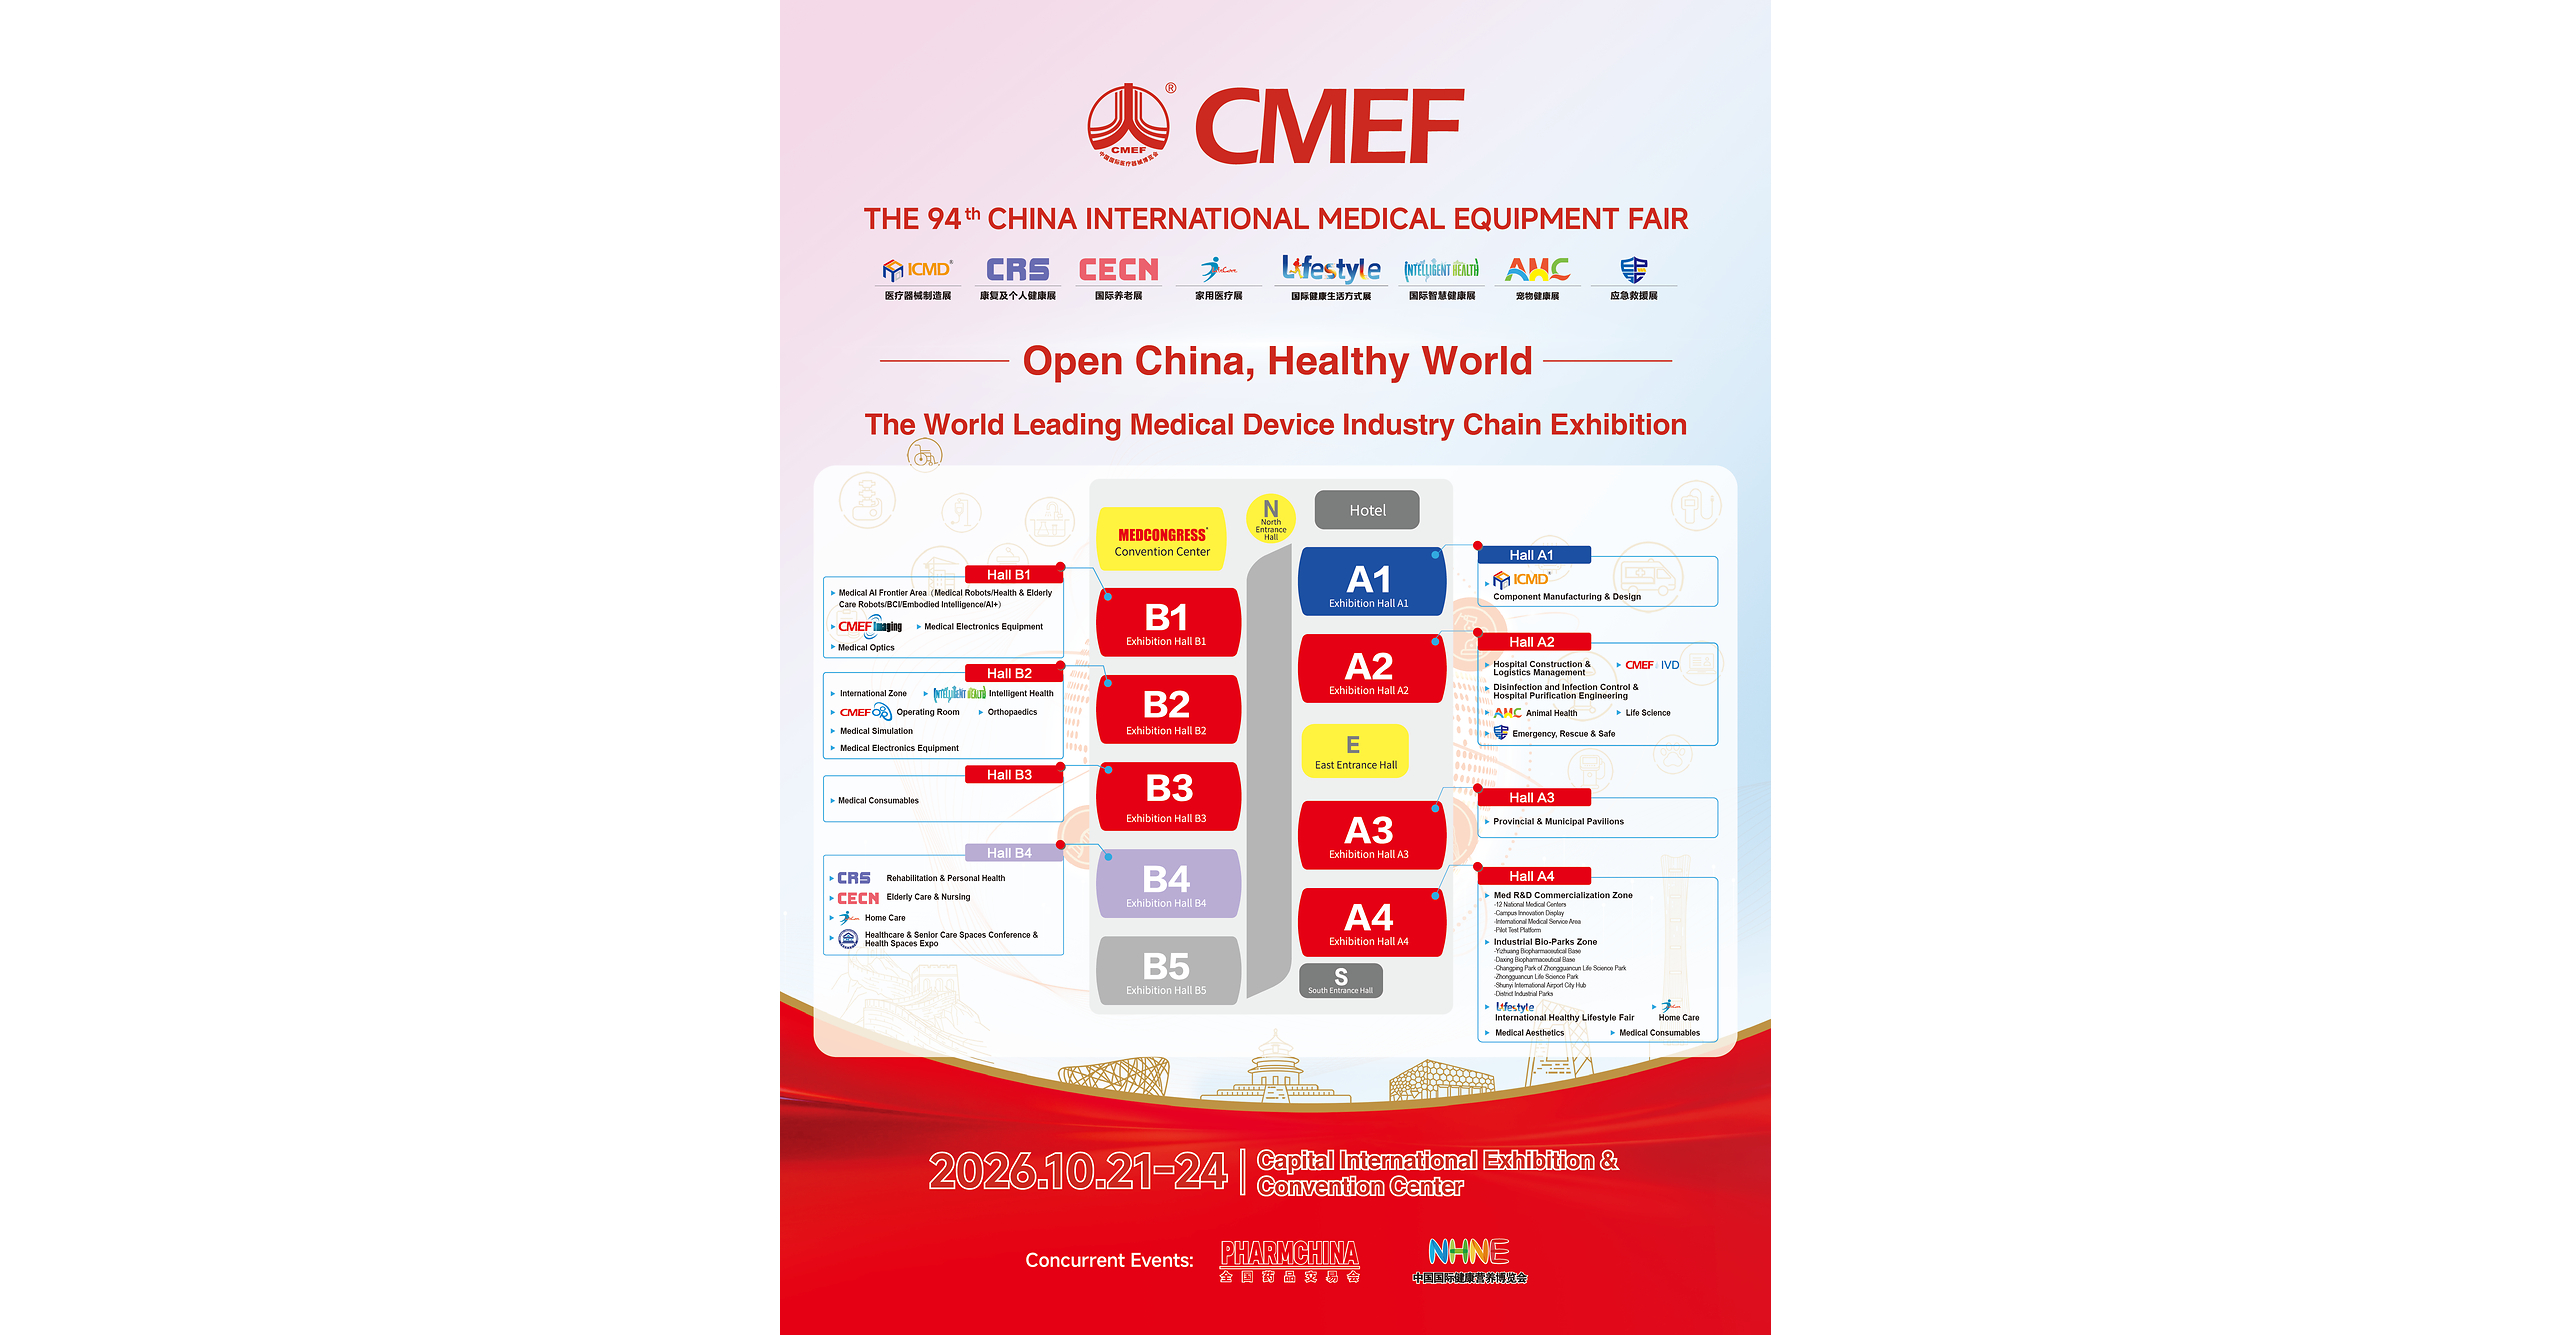
The 94th China International Medical Equipment Fair (CMEF) will be held in Beijing on October 21-24, spanning approximately 170,000 square meters with nearly 3,000 exhibitors, more than 120,000 professional visitors and about 10,000 overseas buyers expected. The event will highlight medical AI, robotics, brain-computer interfaces, diagnostics, rehabilitation and other healthcare technologies, while facilitating supplier sourcing and international commercial partnerships. As a trade-event announcement, the news signals continued activity in China's medical-device innovation ecosystem but has limited direct public-market impact.
Analysis
This is a low-information marketing event rather than a fundamental catalyst; expected attendance and exhibitor counts do not translate into orders, revenue, or margin. There is no investable read-through to "REED" without confirmation of the listed entity, its ownership of the organizer, and whether event economics are consolidated. Treat any near-term volume or social-media interest in AI-medtech names around the event as liquidity-driven, not earnings-relevant.
The useful signal is the buyer-matching emphasis: if overseas procurement activity converts, Chinese domestic device vendors with lower-cost portfolios could gain export share at the expense of premium incumbents in imaging, monitoring, consumables and rehabilitation. Potential beneficiaries include Mindray (300760 SZ), United Imaging (688271 SH) and MicroPort (0853 HK), while GE HealthCare (GEHC), Siemens Healthineers (SHL GR) and Philips (PHIA NA) face only incremental risk because hospital purchasing cycles, regulatory clearances and local service networks remain the binding constraints. The more immediate structural beneficiary is China’s medical-device localization ecosystem, but a trade requires evidence of tender wins and pricing discipline rather than exhibition exposure.
Over the next 1-3 months, watch post-event disclosed distributor agreements, export order backlog, and provincial procurement tender results; these would validate commercial conversion. Over 6-18 months, the key risk is that centralized procurement compresses domestic ASPs faster than export volumes scale, leaving revenue growth intact but impairing gross margins and multiples. The consensus risk in medical AI is that demonstration activity is being mistaken for monetization: hospital integration, reimbursement and clinical validation can extend sales cycles well beyond product launches.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No directional position in REED on this item; first verify the security’s issuer, organizer ownership and event-revenue consolidation. Absent those data, the expected risk/reward is indeterminate.
- Create a 1-3 month watch basket of 300760 SZ, 688271 SH and 0853 HK; upgrade only if post-event contracts include disclosed value, delivery timing and export backlog growth, rather than nonbinding MOUs.
- For a defensively expressed localization thesis, consider a small long 300760 SZ / short GEHC pair only after Chinese tender data show domestic share gains without greater than 200bp gross-margin deterioration at Mindray. Use a 6-12 month horizon; cover the short if GEHC’s China organic growth accelerates or domestic pricing deteriorates.
- Avoid paying up for China medical-AI exposure solely on event visibility. A falsification trigger for the cautious view would be reimbursed deployments or recurring software revenue disclosures that shorten implementation cycles and demonstrate measurable hospital ROI.
More News
- South Korea’s exports hit record high on AI boom
- Asian stocks dip, bonds in focus after torrid September
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- Asia stocks rise on chipmaker gains, soft U.S. inflation; Nikkei outperforms
- We're raising our Micron price target after an incredible quarter and robust guidance