
CHIPOTLE EXPANDS RESTAURANT LEADERSHIP PIPELINE, AIMS TO PLACE AN APPRENTICE IN EVERY RESTAURANT BY THE END OF 2027
Source: PR Newswire
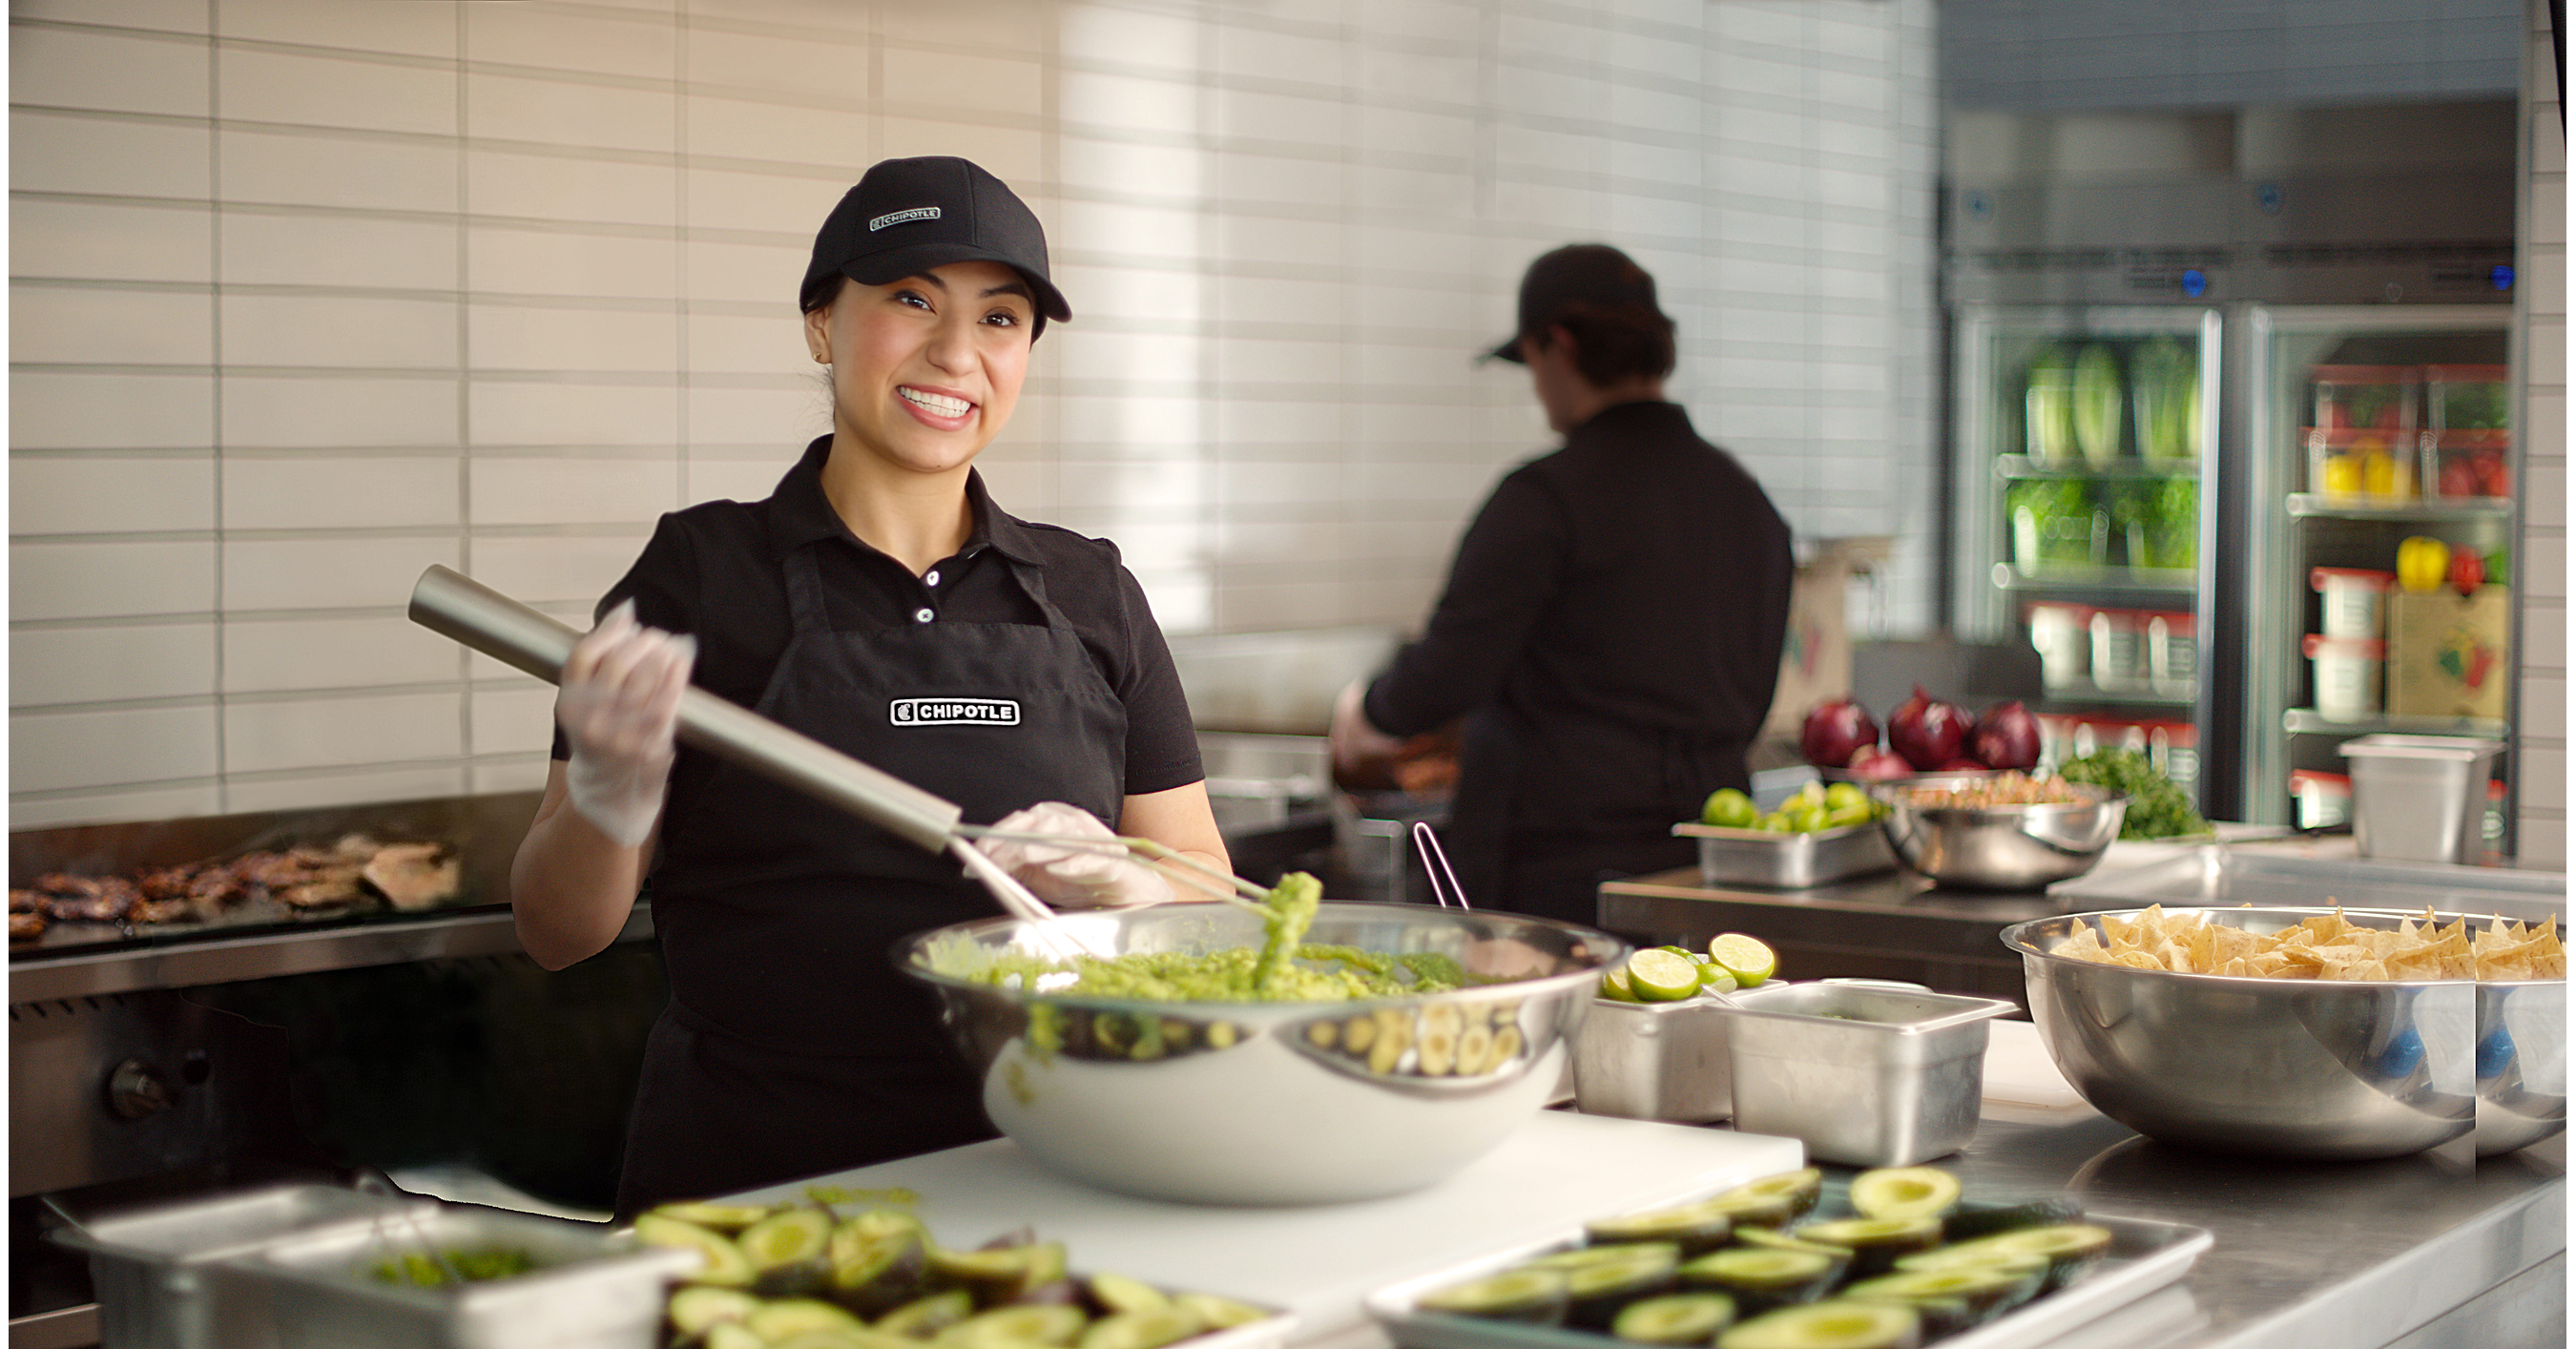
Chipotle plans to open 350-370 restaurants in 2026 and aims to operate 7,000 locations across the U.S. and Canada over the long term, supported by a plan to place an Apprentice in each of its 4,200-plus company-owned restaurants by end-2027. Apprentices currently support roughly 75% of restaurants, while more than 85% of restaurant managers began as Crew Members. Its Guild education partnership has enrolled nearly 25,000 employees over 10 years; participants show 66% lower annual turnover and are promoted about 1.4x as often as non-participants, supporting management capacity and operational consistency during expansion.
Analysis
This is strategically supportive but not an incremental earnings catalyst absent proof that the added management layer improves throughput, digital accuracy, or new-store ramp. CMG’s company-operated model makes leadership bench depth a genuine unit-growth constraint: reducing manager vacancies and early-tenure GM failures could lower pre-opening/training drag and protect restaurant-level margins as development accelerates. The offset is fixed labor expense; an Apprentice in every unit only creates value if sales leverage or avoided turnover exceeds incremental supervisory payroll.
The company’s retention statistics are selection-biased and should not be capitalized into estimates without cohort-level data on wage cost, GM tenure, turnover, and restaurant contribution margins. The key 1-3 month catalyst is whether the next earnings call quantifies new-unit opening productivity, staffing stability, and digital make-line execution rather than merely reiterating workforce initiatives. For the 6-18 month view, successful internal promotion supports a premium multiple by extending the credible runway toward the long-term unit target; weak new-store AUVs or labor deleverage would instead expose the market to a lower terminal unit-economics assumption.
Competitive read-through is modestly negative for franchised QSR peers with weaker labor brands—YUM, QSR and WEN—because internal pipelines raise the cost of competing for experienced hourly and shift-management labor. However, CMG may be paying more to solve an industry-wide operational bottleneck, so the near-term consensus risk is margin dilution rather than immediate share gains. This release alone is not a reason to add risk after a positive reaction.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Maintain CMG rather than chase the release; add only if the next earnings report shows new-unit sales productivity and restaurant-level margin stable-to-up while openings remain on plan. Falsifier: labor-cost deleverage or a reduction in development/opening guidance.
- Set an earnings-call watch item for Apprentice payroll per restaurant, GM vacancy/turnover, digital order accuracy, and new-unit ramp curves. Without these metrics, treat claimed operating benefits as unverified and do not revise estimates.
- For a 6-12 month relative-value expression, consider long CMG / short WEN only after evidence that CMG is sustaining unit growth without labor-margin erosion; the thesis is superior company-operated execution versus a more labor-sensitive value-QSR customer base. Exit if CMG restaurant margins compress materially despite positive comps.
- Avoid treating the education partnership as a standalone Guild-related investment signal: Guild is private and the disclosed program economics do not establish a measurable supplier revenue or profitability impact.
More News
- Starbucks stock outlook: premium valuation meets a turnaround still in progress
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid
- Trip.com swings to Q2 loss after $763 million antitrust penalty
- Push for AI regulation mounts as talk of AI’s ‘existential’ risks go mainstream. But Trump resists calls for a slowdown
- Federal Reserve decision, retail sales, and oil inventories due Wednesday