
Heritage Capital Group Welcomes Massimo Messina as Principal on Supply Chain Team
Source: PR Newswire
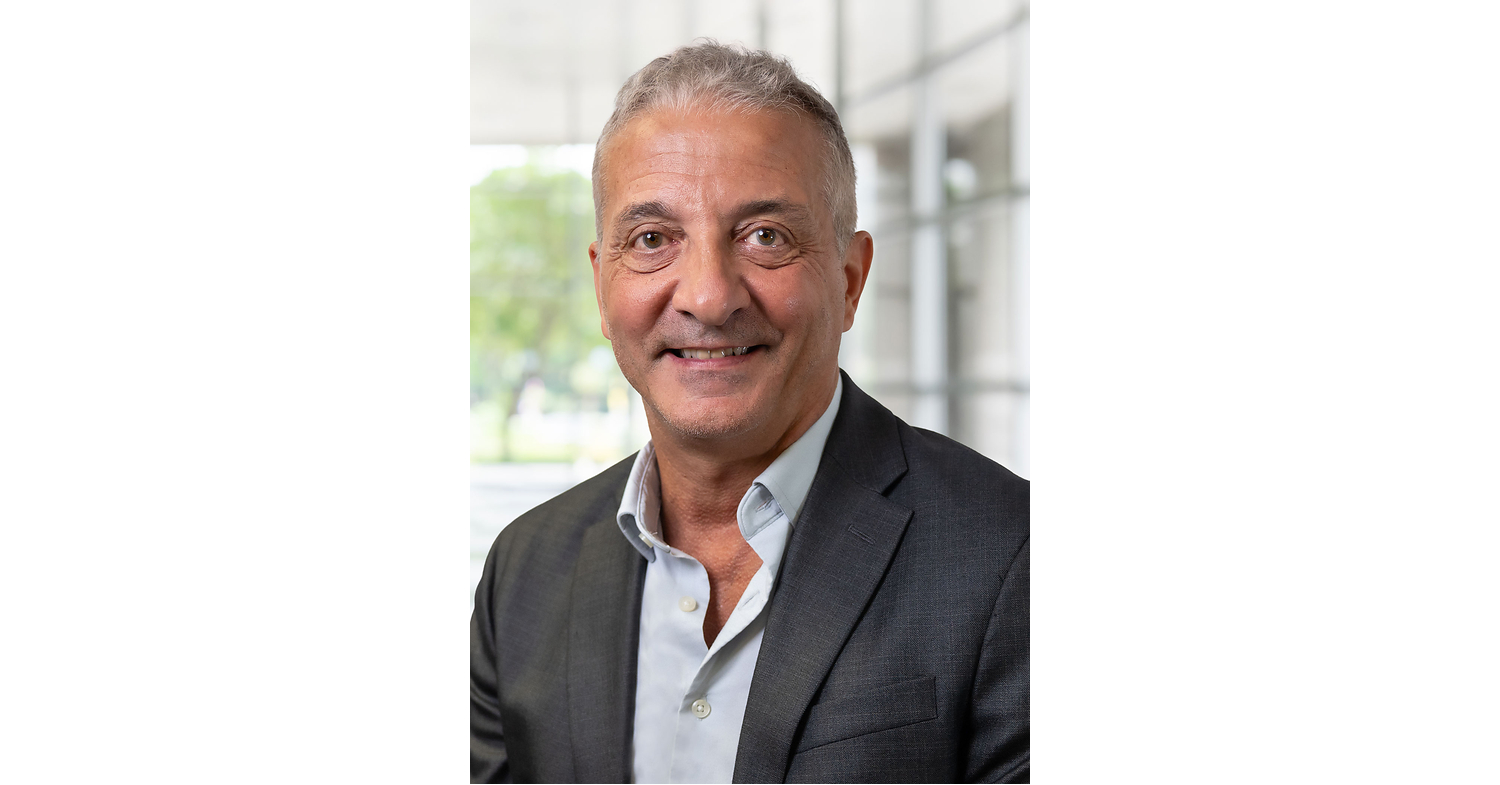
Heritage Capital Group appointed Massimo Messina as Principal on its Supply Chain Team, strengthening its middle-market M&A and capital-raising advisory capabilities across transportation and logistics. Messina brings more than 30 years of M&A and corporate-finance experience, most recently leading M&A and venture investments at Crowley, including work on the $1.2 billion Fairwater merger. The hire expands Heritage's sector expertise in freight, maritime services, warehousing, distribution and transportation technology, but is unlikely to have material public-market impact.
Analysis
This is not a fundamental catalyst for Houlihan Lokey (HLI) despite the ticker mapping: the personnel move is at a private middle-market advisory firm, and the referenced prior employer relationship does not create a disclosed revenue, backlog, or transaction pipeline impact for HLI. The market mechanism is limited to marginally greater advisory capacity in fragmented transportation/logistics M&A, an area where boutique advisors compete primarily on relationships and deal sourcing rather than scalable share gains.
For public transportation assets, the relevant second-order signal is only a weak one: dedicated senior coverage may improve sell-side process quality for private 3PL, warehouse, maritime-services, and freight-tech assets. That could modestly support private-market valuation discovery over 6-18 months, but it is insufficient to alter earnings expectations or multiples for public proxies such as GXO, XPO, CHRW, KNX, or ZIM. No independently verifiable mandate, transaction announcement, or fee economics has been disclosed.
Consensus should treat this as routine firm-building rather than evidence of an imminent logistics consolidation wave. A trade becomes actionable only if subsequent announced transactions establish a pattern of sponsor-backed carve-outs or strategic acquisitions at premiums that reset public comparable valuations; until then, liquidity and freight-cycle fundamentals will dominate. The thesis is falsified—or upgraded—by disclosed mandates, completed deals with valuation data, or a measurable acceleration in transportation M&A volume over the next two quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Key Decisions for Investors
- No directional position in HLI based on this item; maintain existing exposure only on broader advisory-cycle underwriting. Reassess if HLI reports transportation/industrial fee growth or a material shift in its announced-deal backlog.
- Place a 1-3 month watch alert on GXO, XPO, CHRW and RXO for sponsor/strategic transaction announcements at greater than 20% premiums to unaffected prices; multiple private-asset premiums would be a more credible catalyst for a logistics rerating than this hiring.
- For M&A-cycle exposure, prefer a diversified advisory basket rather than single-name reaction trading: monitor HLI versus PJT and LAZ after quarterly fee/backlog disclosures. Enter only if transaction-fee guidance and completed-deal conversion improve, with downside defined by a renewed decline in middle-market deal volumes.
- Avoid extrapolating this announcement into maritime or freight-rate longs such as ZIM or container-shipping proxies; freight pricing, capacity additions, and trade volumes—not advisory staffing—remain the earnings drivers.
More News
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
- What next for France as riots rattle markets? Three questions facing investors ahead of more protests
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Advanced Search Filters, Redesigned Ticker Dashboard, and Improved Search Experience
- How to Build an Automated Research Process for a Fund