
ICIMS Named a Talent Acquisition Leader by Nucleus Research for Seventh Consecutive Year
Source: PR Newswire
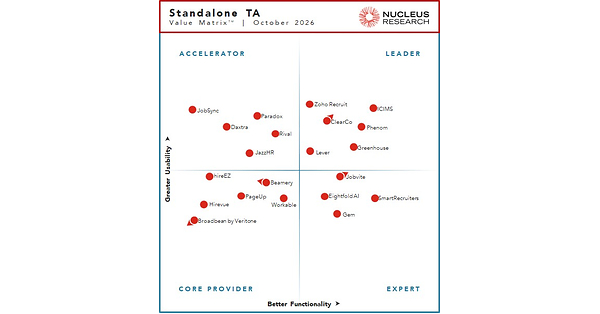
ICIMS was named a Leader in Nucleus Research’s 2026 Standalone Talent Acquisition Technology Value Matrix for the seventh consecutive year and ranked highest in functionality. The report cites its enterprise capabilities and investment in AI-powered recruiting, configurable workflows and fraud detection; ICIMS also highlighted 19 Marketplace categories, more than 25 certified advisory partners and over 10K active HCM integrations. The recognition is positive company validation, but the article reports no financial results or share-price reaction.
Analysis
This is product-validation evidence, not evidence of incremental bookings, pricing power or customer ROI. iCIMS is privately held, so the more relevant read-through is competitive: in a weak hiring environment, AI features may defend renewals and platform consolidation, but buyers can still defer upgrades unless vendors quantify recruiter-hour savings, faster time-to-fill or fraud losses avoided. If agents become table stakes, differentiation shifts toward proprietary candidate data, workflow integration and measurable outcomes; that could pressure standalone recruiting tools and raise the bar for Workday, SAP and Oracle as well as iCIMS.
The Microsoft Teams workflow is a modest ecosystem positive for Microsoft’s role in enterprise collaboration, not a material MSFT revenue catalyst on this evidence. Gartner’s and The Hackett Group’s cited assessments may support their research credibility, but one vendor recognition is not a meaningful near-term financial signal for either. The release is vendor-sponsored; validate adoption, customer retention and monetization independently.
Near term (days), expect little fundamental price discovery from the announcement. Over 1–3 months, watch enterprise HR software commentary for hiring-budget recovery, AI attach rates and customer evidence. Over 6–18 months, successful automation could support platform consolidation, while weak hiring or low realized ROI would expose AI features as defensive marketing. Contrarian angle: repeated awards may be less informative than whether customers expand spend; headline AI momentum risks overstating near-term monetization.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No trade based on this release alone; iCIMS has no listed equity exposure in the supplied company mapping, and the evidence does not establish a revenue catalyst for HCKT, MSFT or Gartner (IT).
- Treat MSFT as a watch item only: Teams-based workflow integration could reinforce collaboration-layer stickiness, but verify broader customer usage or commercial impact before assigning earnings significance.
- Monitor Workday, SAP and Oracle commentary for recruiting-suite attach rates, customer expansions and measurable AI productivity outcomes; stronger evidence would support a relative long in vendors demonstrating monetization, while weak adoption would favor avoiding the AI-premium narrative.
- Falsification/watch triggers: credible customer-level ROI and paid AI adoption would strengthen the platform-differentiation thesis; continued hiring-budget cuts, delayed HR software renewals or no evidence of AI monetization over coming quarters would weaken it.
More News
- Tech's relief rally extends as attention turns to tough decisions for the Fed
- AI debt fears ease ahead of Oracle, Alphabet and Amazon updates. Here's what to watch.
- The big takeaways and big questions from Anthropic’s S-1
- Anthropic’s S-1, by the numbers: A thriving business—with a $441 billion asterisk
- What's behind the AI trade comeback — plus, our take on Intel's latest deal
- U.S. stock futures flat with Fed rate decision, megacap tech earnings on tap