
Hisense stellt die neue C3-Projektorreihe für ein intensives Home-Entertainment-Erlebnis vor
Source: PR Newswire
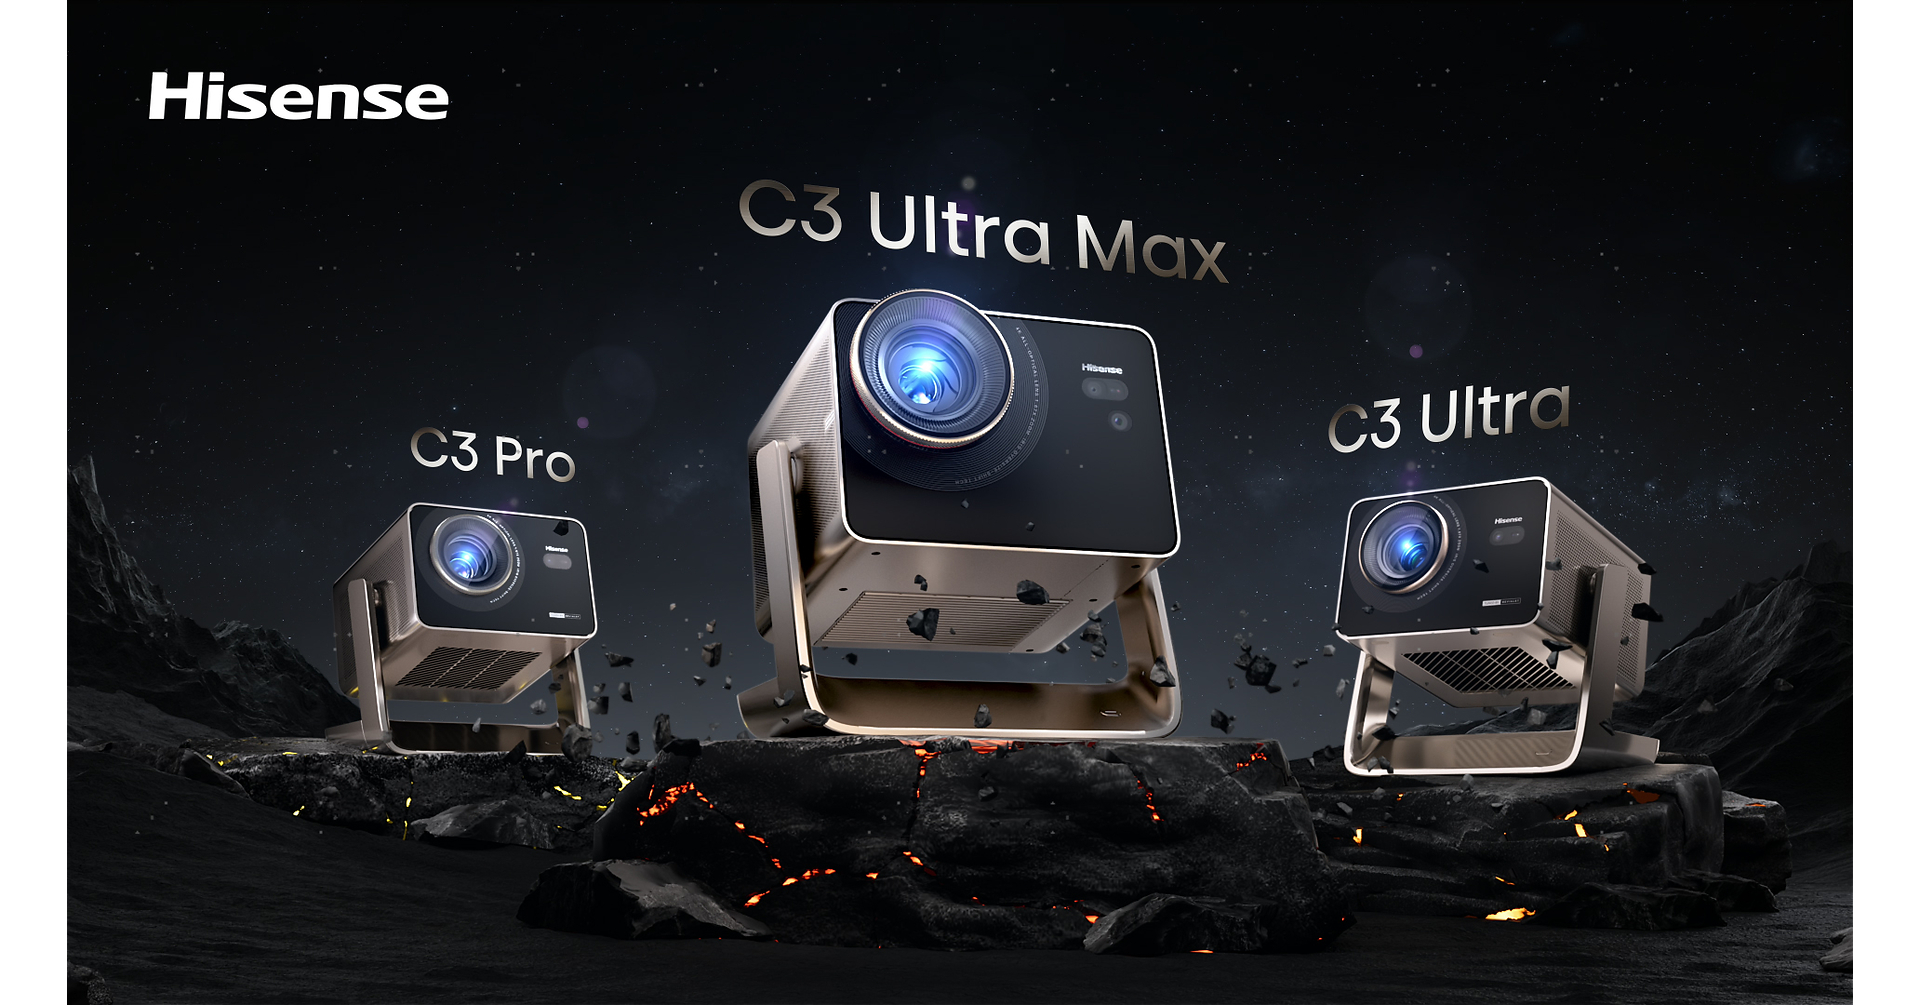
Hisense introduced its C3 projector family, with the C3 Ultra and C3 Ultra Max scheduled for global launch in September 2026 and the C3 Pro to follow. The lineup offers up to 300-inch projection sizes, 3,000-5,000 ANSI lumens, 5,000:1 contrast ratios, Devialet-tuned audio and, for the Ultra Max, 1 ms latency for gaming. Hisense also cited SGS lifecycle and product-carbon-footprint assessments, though the announcement provides no pricing, sales outlook or financial guidance.
Analysis
This is not directly monetizable through SGSN: its role is third-party verification, and a single product-level lifecycle assessment is unlikely to alter revenue or margin expectations. The relevant read-through is competitive rather than financial—Hisense is pressing further into premium large-format home entertainment, where projectors can substitute for 85–100-inch TVs and pressure incumbent display vendors’ mix aspirations.
Near-term sell-through will depend far more on retail pricing, channel inventory and the credibility of brightness/latency claims than on launch specifications. Projectors remain a discretionary category with meaningful installation and ambient-light constraints; absent independently tracked retail rankings or pricing data, this is insufficient to infer a demand inflection for the broader consumer-electronics complex over the next 1–3 months.
Over 6–18 months, if lower-priced high-brightness projectors gain share, the marginal risk falls on premium TV vendors exposed to large-screen ASPs, including Sony (6758 JP) and LG Electronics (066570 KS), while streaming, gaming and live-sports consumption provide a modest demand tailwind. The environmental certification angle could become commercially relevant only if EU retailer procurement standards or product-passport rules begin to favor verified product-footprint disclosures; currently it is a branding differentiator, not a valuation catalyst.
Contrarian view: the market may overstate the substitution threat. Large-screen TV buyers value daylight performance, ease of use and reliability, where MiniLED/OLED sets retain advantages. A projector-category share gain would need to be accompanied by sustained price compression without warranty-cost escalation—an outcome that can damage manufacturers even as unit volumes rise.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- No standalone SGSN trade: require evidence that product-carbon verification is converting into recurring consumer-electronics certification wins or disclosed segment growth before assigning financial relevance.
- Set a 1–3 month channel-data watch on projector sell-through and C3 pricing versus 98-inch MiniLED TVs in Europe and North America. A sustained >15% price discount per effective screen inch, coupled with top-tier retailer ranking, would justify reassessing large-screen TV ASP risk.
- For Asia consumer-electronics exposure, monitor a relative-value short watch in 6758 JP or 066570 KS versus broader hardware indices only if management flags premium large-screen mix, ASP, or inventory-guide pressure. Falsify the concern if premium TV ASPs and inventory turns remain stable through the next earnings cycle.
- Track EU digital-product-passport and retailer sustainability-procurement developments over 6–18 months. A mandate or preferred-vendor framework requiring verified lifecycle data would be a more meaningful positive catalyst for SGSN than this individual engagement.
More News
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Karin Rådström is steering Daimler Truck in a new direction as the world’s biggest truckmaker faces a growing challenge from China
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
- Factbox-How AI leaders and world governments react to ’AI doom’ fears
- Chinese investors rush into US stocks as Beijing opens wider path overseas
- ‘The end of the keyboard is near’: Christian Klein predicts voice translation will be the next workplace advantage
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Evaluate AI Report Writers for Financial Analysis
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements