
Pylontech Starts Mass Production of 588Ah and 601Ah LFP Cells for ESS
Source: PR Newswire
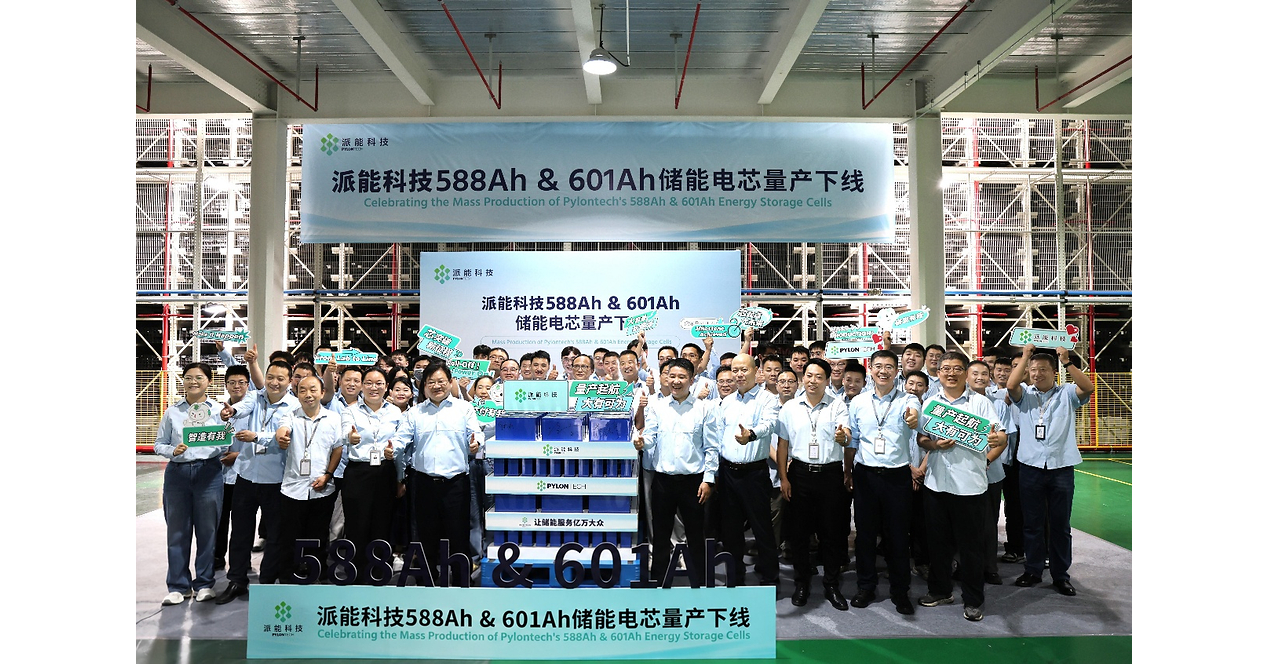
Pylontech began mass production of 588Ah and 601Ah prismatic LFP cells for utility-scale energy storage, with more than 100MWh already produced at its Hefei facility. The 601Ah cell delivers 425.8Wh/L energy density, over 12,000 cycles and 96.5% energy efficiency, and will be integrated into PyOcean 6.25MWh and 8MWh storage systems entering project delivery. The launch strengthens Pylontech's utility-scale ESS offering and manufacturing scale, supported by fully automated core processes and end-to-end cell traceability.
Analysis
The investable implication is less about incremental cell capacity and more about whether Pylontech (688063.SS) can close the bankability gap separating residential-storage incumbents from utility-scale suppliers. Larger-format LFP designs can lower container-level balance-of-system, wiring and commissioning costs, but the economic benefit accrues only if field failure rates, thermal performance and warranty reserves hold through initial project deployments. Until third-party project acceptance and gross-margin disclosure validate those assumptions, this is a capability signal rather than an earnings catalyst.
Competitive pressure is most acute for Chinese ESS cell vendors whose differentiation rests on scale rather than system integration, including EVE Energy (300014.SZ), REPT BATTERO (666.SH) and Hithium privately. CATL (300750.SZ) retains procurement and financing advantages, while Sungrow (300274.SZ) is better insulated because inverter, PCS and project-delivery content can offset cell-price deflation. The second-order risk is that a broader shift to 600Ah-class cells accelerates qualification cycles and inventory obsolescence for integrators holding older-format modules, worsening sector pricing before lower system costs translate into higher demand.
Over the next 1-3 months, watch disclosed backlog conversion, named external utility customers, independently verified cycle-life data and gross-margin trajectory; these matter more than production announcements. A successful delivery cycle could improve Pylontech's valuation narrative over 6-18 months, but utility storage remains exposed to Chinese tender-price compression, project financing conditions and tariff/local-content rules in Europe and the US. The contrarian view is that higher energy density may intensify, not relieve, competition: standardized large cells reduce differentiation and could push savings to EPC customers rather than suppliers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No immediate directional position in Pylontech (688063.SS): wait for the next results release or project-delivery disclosures to confirm external orders, utilization and segment gross margin. Upgrade only if utility-scale revenue/backlog is separately disclosed and margin dilution is contained; absent this, the announcement alone is insufficient for a long.
- Monitor a relative-value setup: long Sungrow (300274.SZ) versus short a broad China battery-cell proxy led by EVE Energy (300014.SZ) if large-cell tender pricing falls while ESS shipment volume holds. Sungrow's higher-value PCS/system content should be relatively more resilient; invalidate if inverter pricing declines in parallel or storage project bookings weaken.
- Set an alert on CATL (300750.SZ), EVE Energy (300014.SZ) and Pylontech for 600Ah-class product qualification announcements and utility-storage tender results over the next quarter. Multiple suppliers qualifying comparable cells without a corresponding rise in tender prices would support a sector-margin-compression thesis rather than a technology-driven rerating.
- For 6-12 month renewable-storage exposure, prefer diversified system and grid-infrastructure beneficiaries over pure cell suppliers until warranty provisions and realized project economics are visible. Reassess after first meaningful external deployments; elevated warranty charges, delayed acceptance, or negative utility-storage gross margin would falsify the Pylontech upgrade case.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Trump Says US Team Met With Iranians at UNGA
- South Korea’s Lee, Trump welcome progress in US strategic investment projects