
Performance Brokerage Services Advises on the Sale of Dale Willey Chevrolet GMC in Lawrence, Kansas, from Greg Maurer to Cable Dahmer Automotive Group
Source: PR Newswire
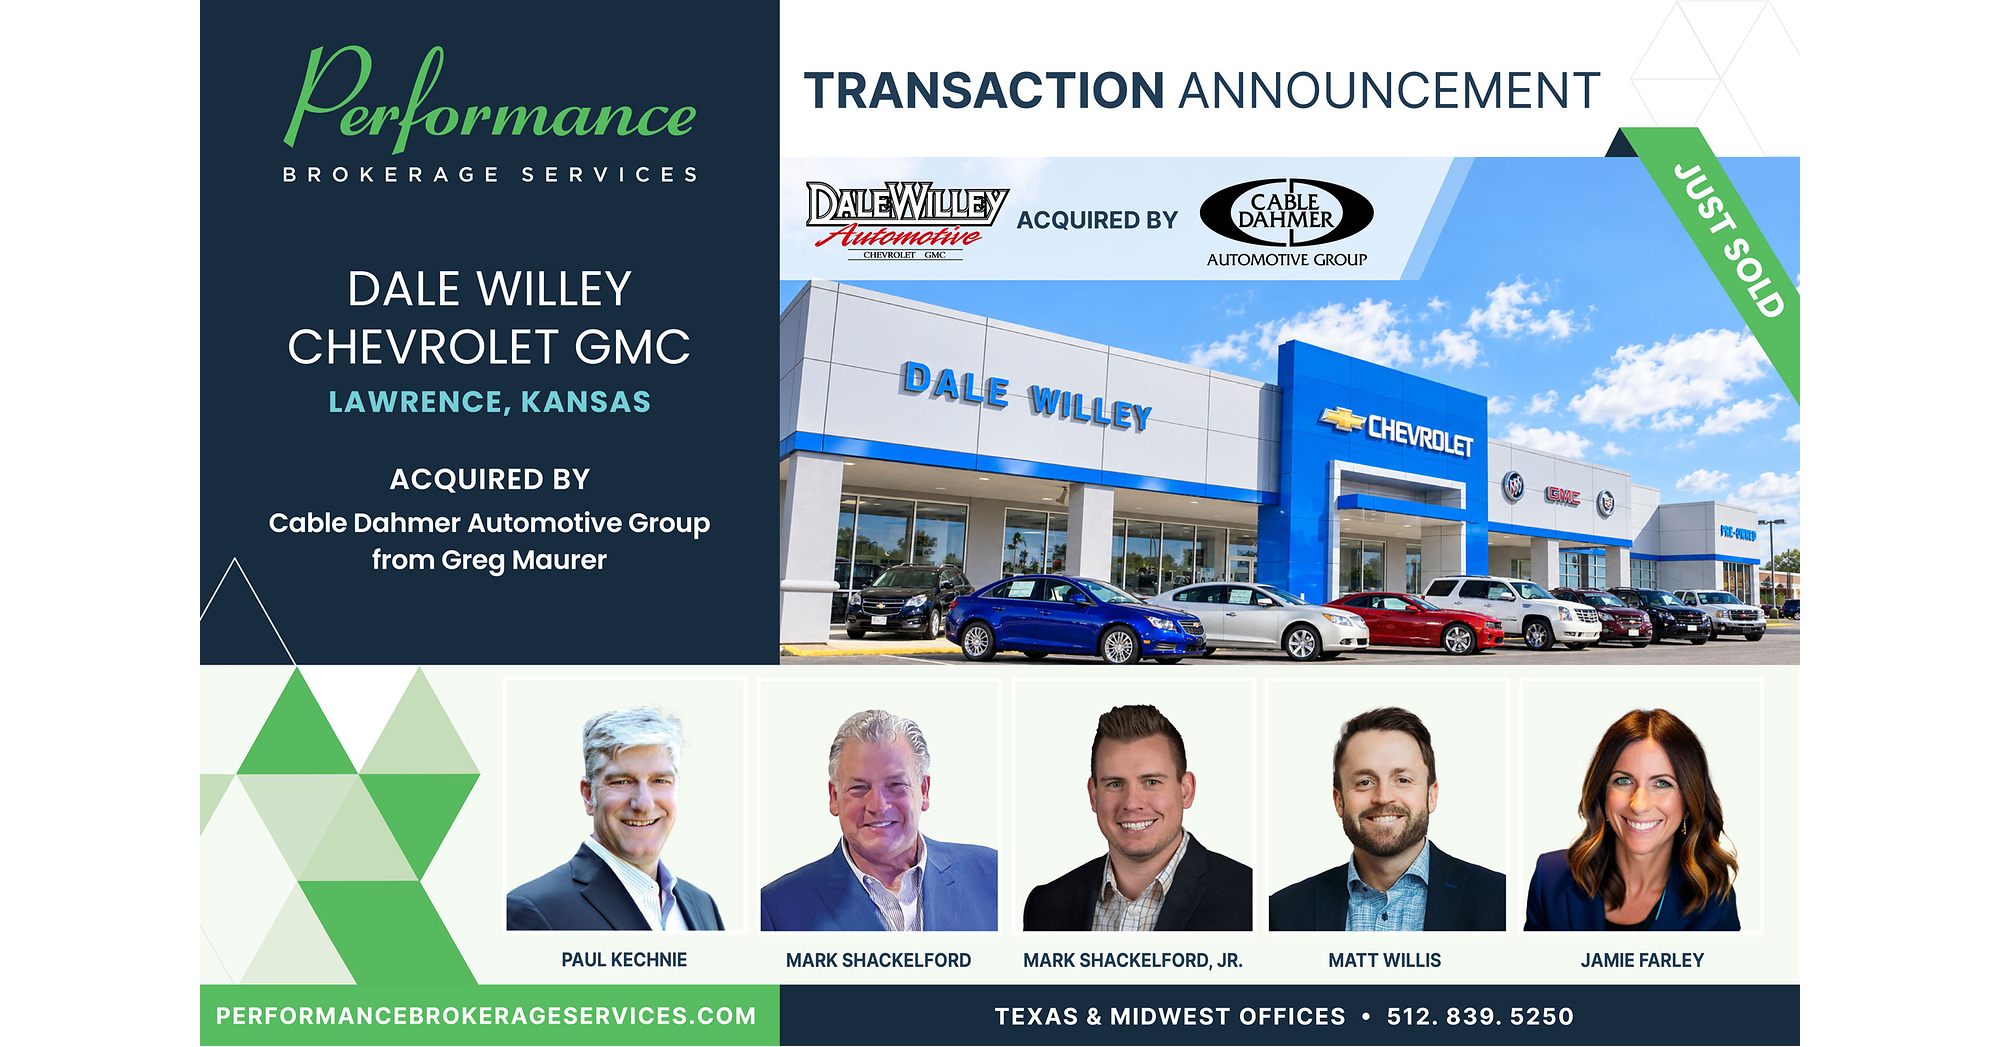
Cable Dahmer Automotive Group acquired Dale Willey Chevrolet GMC in Lawrence, Kansas, from Greg Maurer, adding its third dealership in Kansas and bringing the group to 10 stores. The dealership will be renamed Cable Dahmer Chevrolet GMC and remain at its current location; financial terms were not disclosed.
Analysis
This is a small, privately held dealership transfer with no disclosed consideration, so it does not establish a valuation benchmark or justify a near-term read-through to public auto retailers. The more relevant signal is continued succession-driven consolidation: regional groups can spread management, marketing, inventory, and technology costs across stores, while preserving local operations may reduce customer and employee disruption. Any benefit is likely incremental and dependent on execution, not an immediate step-change in Cable Dahmer’s economics.
For public peers such as Lithia (LAD), AutoNation (AN), Penske Automotive (PAG), Group 1 Automotive (GPI), and Sonic Automotive (SAH), this is a weak directional data point at most. The structural upside is strongest if acquisitions remain available at returns above the cost of capital; the counterweight is that buying stores does not remove exposure to vehicle affordability, OEM allocation, used-car pricing, or fixed-operations demand. A more meaningful read-through would require disclosed purchase prices, store-level earnings, or evidence that acquisition multiples and integration returns are improving.
Near term, likely immaterial to share prices. Over 1–3 months, monitor dealership transaction disclosures and public dealer-group guidance for acquisition pace and return thresholds. Over 6–18 months, sustained consolidation could advantage scaled operators, but OEM approval, local competition, and integration quality can limit synergies. The contrarian point: a single orderly retirement sale is not evidence of an acquisition wave or a change in sector fundamentals.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No trade on this transaction alone; the purchase price and store-level financials are undisclosed, and the buyer is privately held.
- Treat this as a low-confidence consolidation datapoint, not a catalyst for LAD, AN, PAG, GPI, or SAH; avoid adding sector exposure based on the announcement.
- Watch public dealer-group earnings and filings for acquisition spending, acquired-store returns, and used-vehicle/fixed-operations trends; those data would determine whether consolidation is creating value or merely adding scale.
- Falsification of the constructive consolidation thesis: public groups slow acquisitions or report weaker returns on acquired stores, while OEM constraints or deteriorating retail demand prevent operators from realizing scale benefits.
More News
- DoorDash offers $17 billion for Instacart: ‘the largest companies are only eating more and more of the pie’
- The U.S. and EU could break their tariff truce over a record-breaking $3.4 billion Airbus loan and a reignited 17-year dispute between aviation giants
- Alphabet’s stock has worst day in over 20 years, dragging the S&P 500 to first loss in four days
- Google Erases a Record $500 Billion as AI Eats Into Sales
- Google Sales Miss Reignites AI Fears, Microsoft Eyes $25B Debt Offering
- DoorDash to Buy Rival Instacart in $17 Billion Deal