
Kevin Warsh’s Economic Guideposts: Evening Briefing Americas
Source: Bloomberg
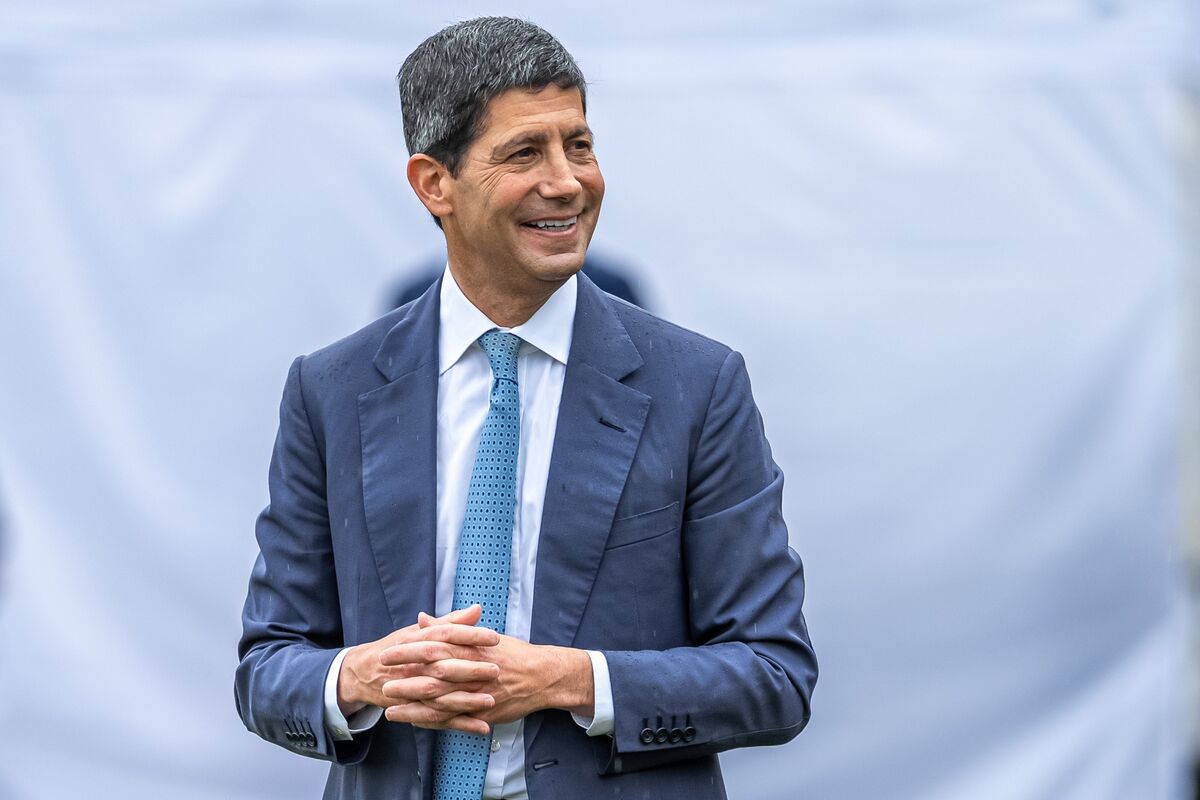
Kevin Warsh, speaking in Jackson Hole, outlined the economic indicators he says guide his view of the U.S. outlook. The article notes that the majority of the indicators he referenced point to encouraging conditions, offering some clarity amid prior concerns about shifting inflation/rate-hike messaging. Overall, the read-through is modestly supportive for the near-term economic trajectory, though no specific policy or rate numbers were provided.
Analysis
The market takeaway is less about a near-term policy pivot and more about reducing tail risk of an inflation-first Fed surprise. If investors had been pricing a more ideological or less data-anchored framework, this kind of signaling compresses the volatility premium in front-end rates and supports rate-sensitive equities over the next 1-3 months. The cleanest second-order effect is in consumer credit: even modest relief in monthly payments can change default behavior at the margin, but only if it shows up in actual refinancing and delinquency data.
Relative winners are the usual duration-sensitivity names: regional banks, homebuilders, and leveraged consumer lenders. CRMT is the most directly levered among the named names because used-car affordability and payment burden are the operating variables that matter; however, if easing is being driven by slower growth rather than cleaner inflation, credit losses can offset the headline benefit. That makes this more of a spread trade than a beta trade: lower rates help, but weaker employment would hurt the same balance sheet you are trying to support.
Contrarian view: consensus may be over-reading the speech as dovish when it may actually be a credibility signal that the bar for cuts remains high. If core inflation stalls or reaccelerates, the bond market can reverse the whole setup quickly, and long-duration growth would outperform again. Falsifiers to watch are a sticky 2Y Treasury yield and no improvement in auto/consumer delinquency metrics over the next two earnings cycles; if those fail to turn, the rate-sensitive rotation is probably premature.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- Tactically buy CRMT on weakness as a 1-3 month expression of lower-payment affordability; keep size small and exit if auto delinquency or charge-off data fails to improve by the next print.
- Pair trade: long IWM / short QQQ for a 1-3 month window if the market continues to price benign Fed policy and modestly lower real rates; stop out if CPI reaccelerates or 10Y yields break above the recent range.
- Add to regional-bank exposure via KRE only on a pullback, not at strength; the thesis is curve relief, but it breaks if deposit beta stays high or loan losses widen.
- Do not chase DJT on this headline alone; use it only as a political-volatility proxy around nomination headlines, and fade strength if the market is already pricing a perfect pro-Trump policy path.
- Set an alert on the 2Y Treasury yield and next core PCE print: if the 2Y stops falling while the speech-driven risk rally continues, rotate out of rate-sensitive longs and back into defensives.
More News
- CNN, Politico, MS NOW to sue Trump administration over White House ban
- Denmark says NATO shares responsibility for Arctic security under Greenland deal
- Philip R. Lane: Interview with Le Temps
- Reserve Bank of Australia Governor Bullock warns of inflation risks as rate decision looms
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- The show must go on: struggling luxury brands seek catwalk boost in Milan and Paris