
CARNIVAL TROPICALE 現已開放預訂,將於 2028 年自加爾維斯敦啟航
Source: PR Newswire
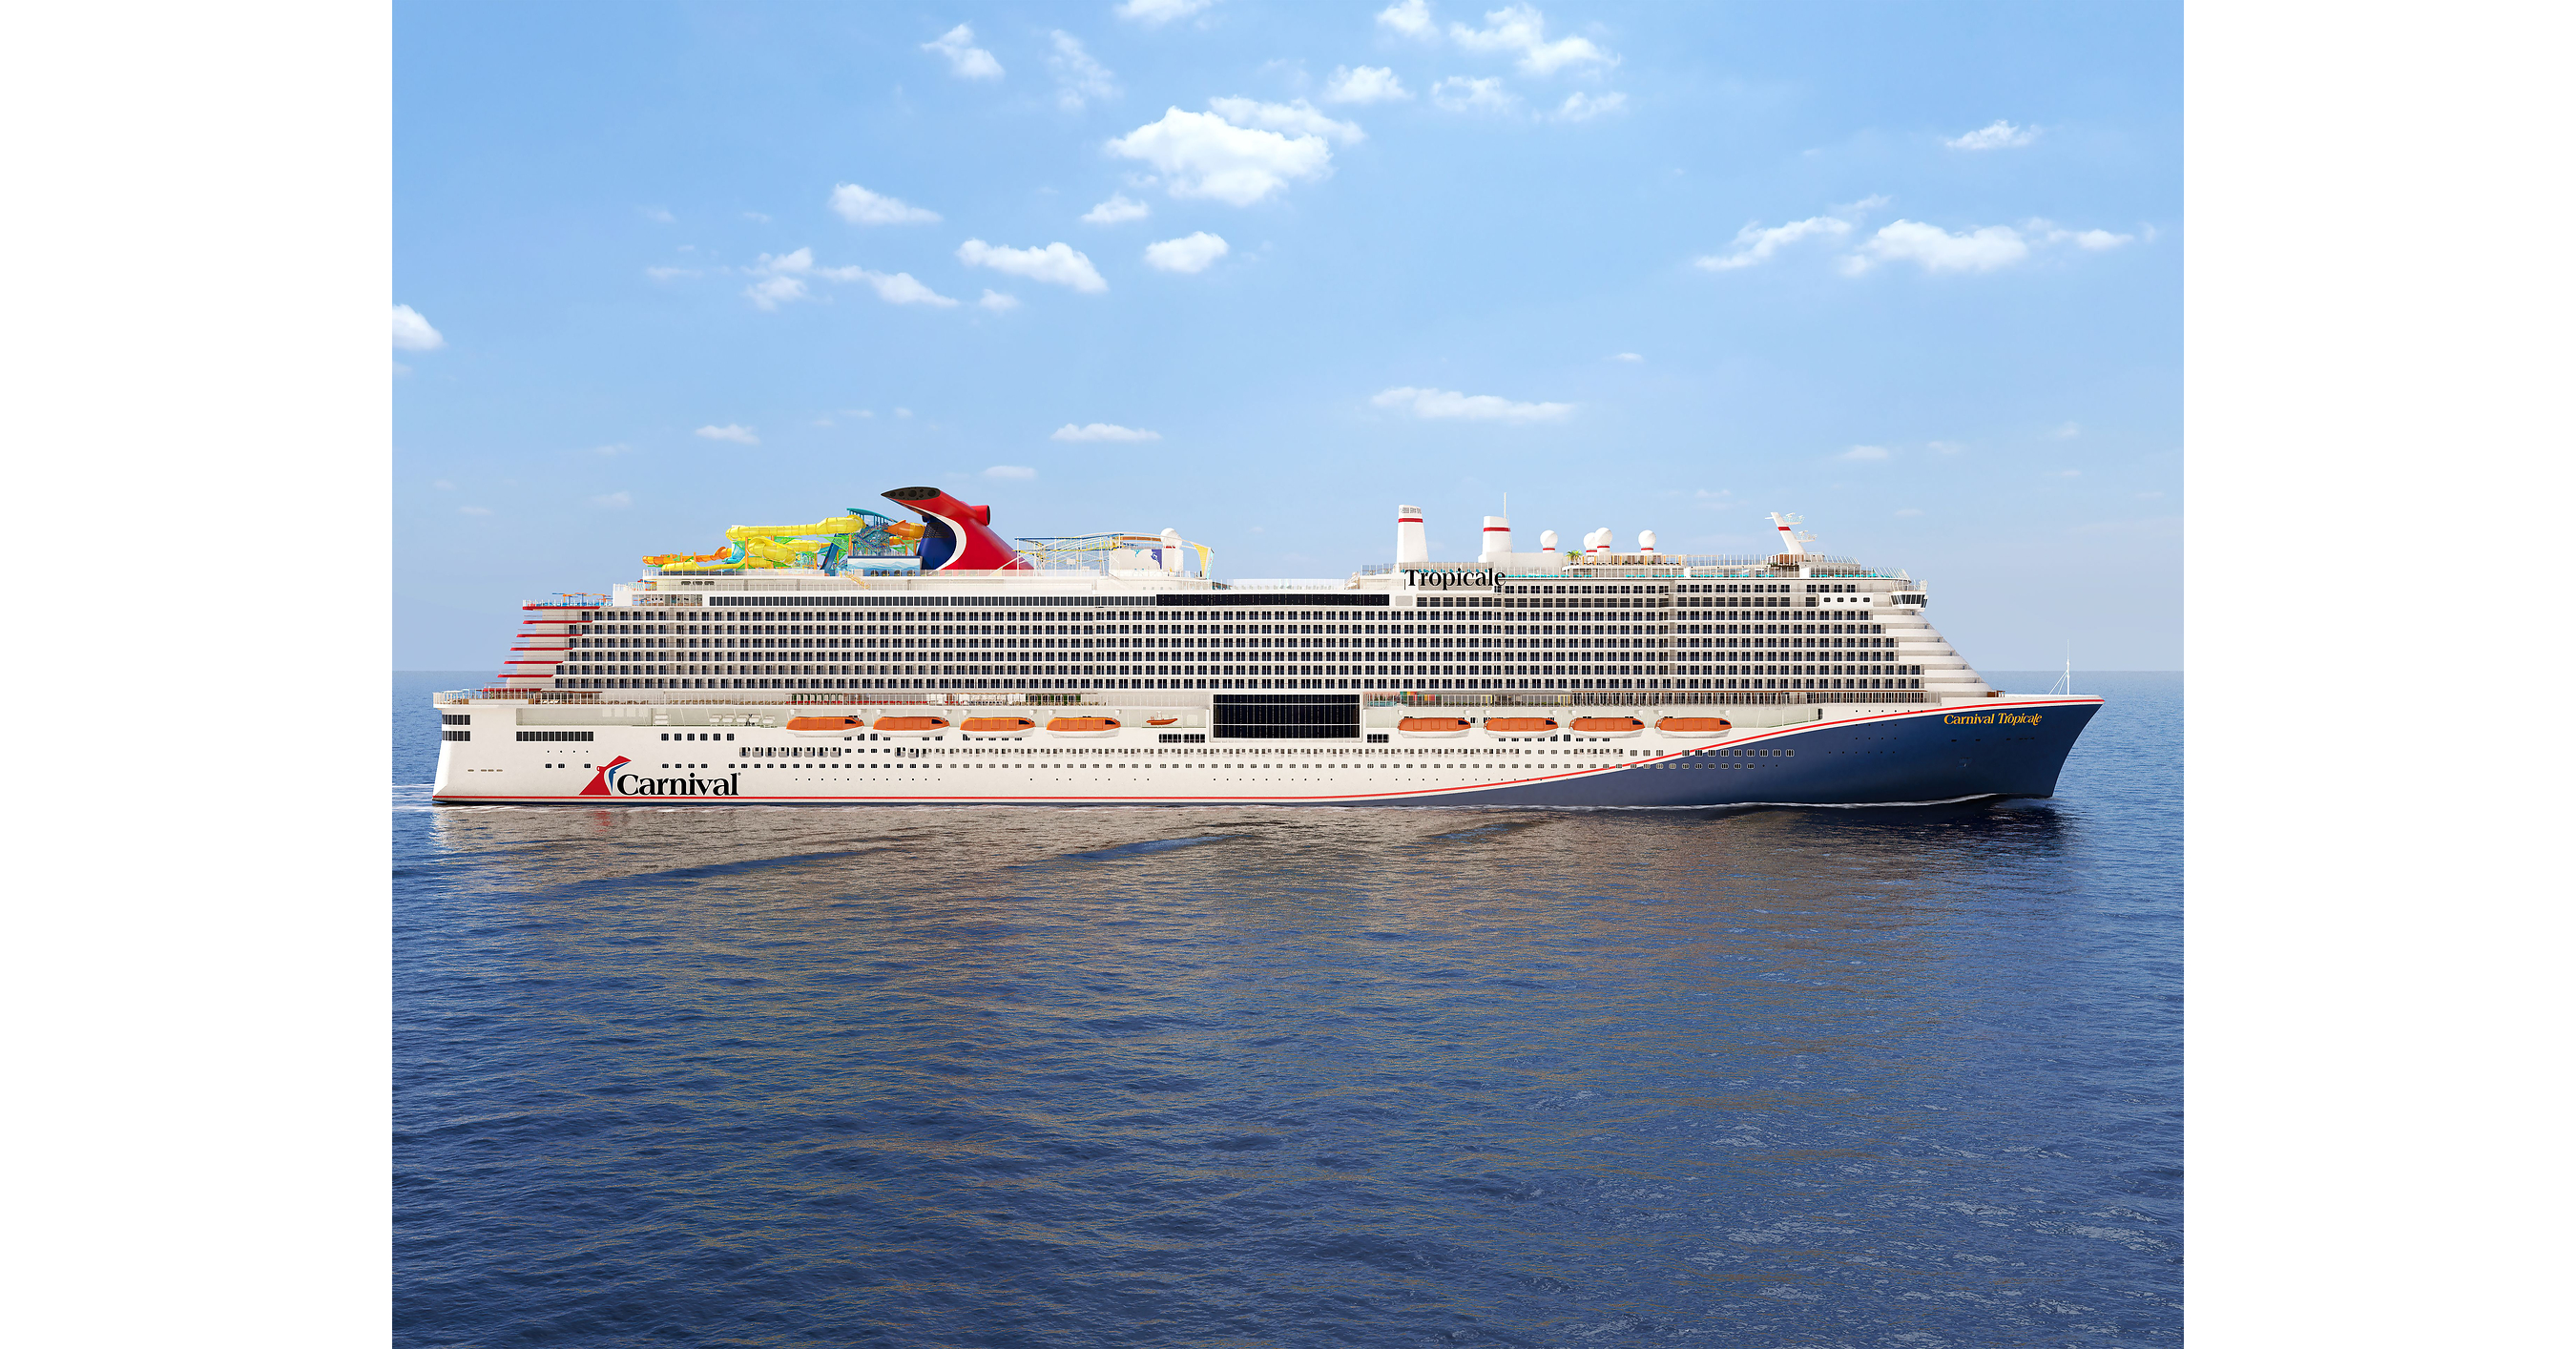
Carnival Cruise Line 開放其第五艘、也是最後一艘 Excel 級郵輪 Carnival Tropicale 的預訂;該船預計於 2028 年 4 月 15 日自德州加爾維斯敦首航。新船將提供 4至8天加勒比海、巴哈馬及墨西哥航程,並配置六條滑水道的 Carnival WaterWorks Ultra、水上及家庭娛樂設施與多項新餐飲概念。此舉支持 Carnival 至2033年前新增5艘郵輪的船隊擴張計畫,但因交付及營運仍在2028年以後,短期財務影響有限。
Analysis
This is strategically more relevant to CCL's yield-management model than to near-term capacity growth. A 2028 deployment into the Texas drive-to market can deepen itinerary density around company-controlled destinations, where shore-side spend and guest retention carry structurally better economics than third-party port calls. The key second-order benefit is the ability to package shorter sailings with proprietary destinations, protecting onboard and excursion revenue even if headline ticket pricing becomes more promotional.
The financial contribution before 2028 is limited: early bookings provide deposits and demand visibility, but will not meaningfully alter consensus EBITDA or free-cash-flow estimates over the next 12-18 months. The more material issue is whether the build program remains disciplined relative to CCL's deleveraging needs; shipyard cost inflation, euro-dollar exposure and delivery slippage could convert an otherwise positive capacity addition into incremental balance-sheet pressure. Monitor net yields for the Galveston/Caribbean portfolio, capex guidance, and net-debt-to-EBITDA rather than treating booking availability as a standalone catalyst.
Competitive pressure should fall more on Caribbean operators with overlapping short-duration, family-oriented itineraries—particularly NCLH—than on premium-oriented RCL brands, but CCL also risks cannibalizing its own existing Gulf Coast sailings if demand is not incremental. Consensus may overvalue the marketing appeal of a new vessel while underweighting the destination-network economics; the thesis only strengthens if booking curves show premium pricing rather than simply high early volume. A downgrade in 2027-28 yield guidance, an upward capex revision, or a material weakening in consumer discretionary travel would falsify the constructive view.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade solely on this announcement; the 2028 revenue recognition horizon is too distant to support a near-term earnings-estimate revision.
- Maintain CCL on a 1-3 month watchlist for evidence that Caribbean net yields and onboard revenue are accelerating; add only if management reaffirms deleveraging while holding new-build capex guidance, as this would support multiple expansion alongside earnings growth.
- Consider a conditional 6-12 month pair trade: long CCL / short NCLH if CCL's Caribbean yield growth outpaces NCLH by at least 200 bps across two reporting periods. The intended payoff is relative margin resilience from destination ownership and itinerary density; exit if CCL raises capex or leverage guidance.
- Set alerts for MEYER WERFT delivery milestones, disclosed contract-cost changes, and CCL net-debt-to-EBITDA guidance. Any cost-overrun disclosure or leverage trajectory above management's stated path should override the product-cycle narrative and argues against owning incremental CCL exposure.
More News
- Royal Caribbean Stock Jumps After Better-Than-Expected Earnings, Raised Outlook
- OneSpaWorld earnings up next as cruise demand hits records
- SK Hynix third-quarter profit sharply beats estimates on AI memory boost
- SK Hynix Posts Record Profit Amid AI Rush
- Anthropic's IPO could be 'speculative fiction' or a 'generational moment' — investors are split
- Anthropic Gives Traders a Pure-Play Bet on Frontier AI