
Khloé Kardashianová oznamuje rozšíření prodeje do sítě Sephora se svým celosvětově oceněným portfoliem parfémů ve spolupráci se společností Luxe Brands
Source: PR Newswire
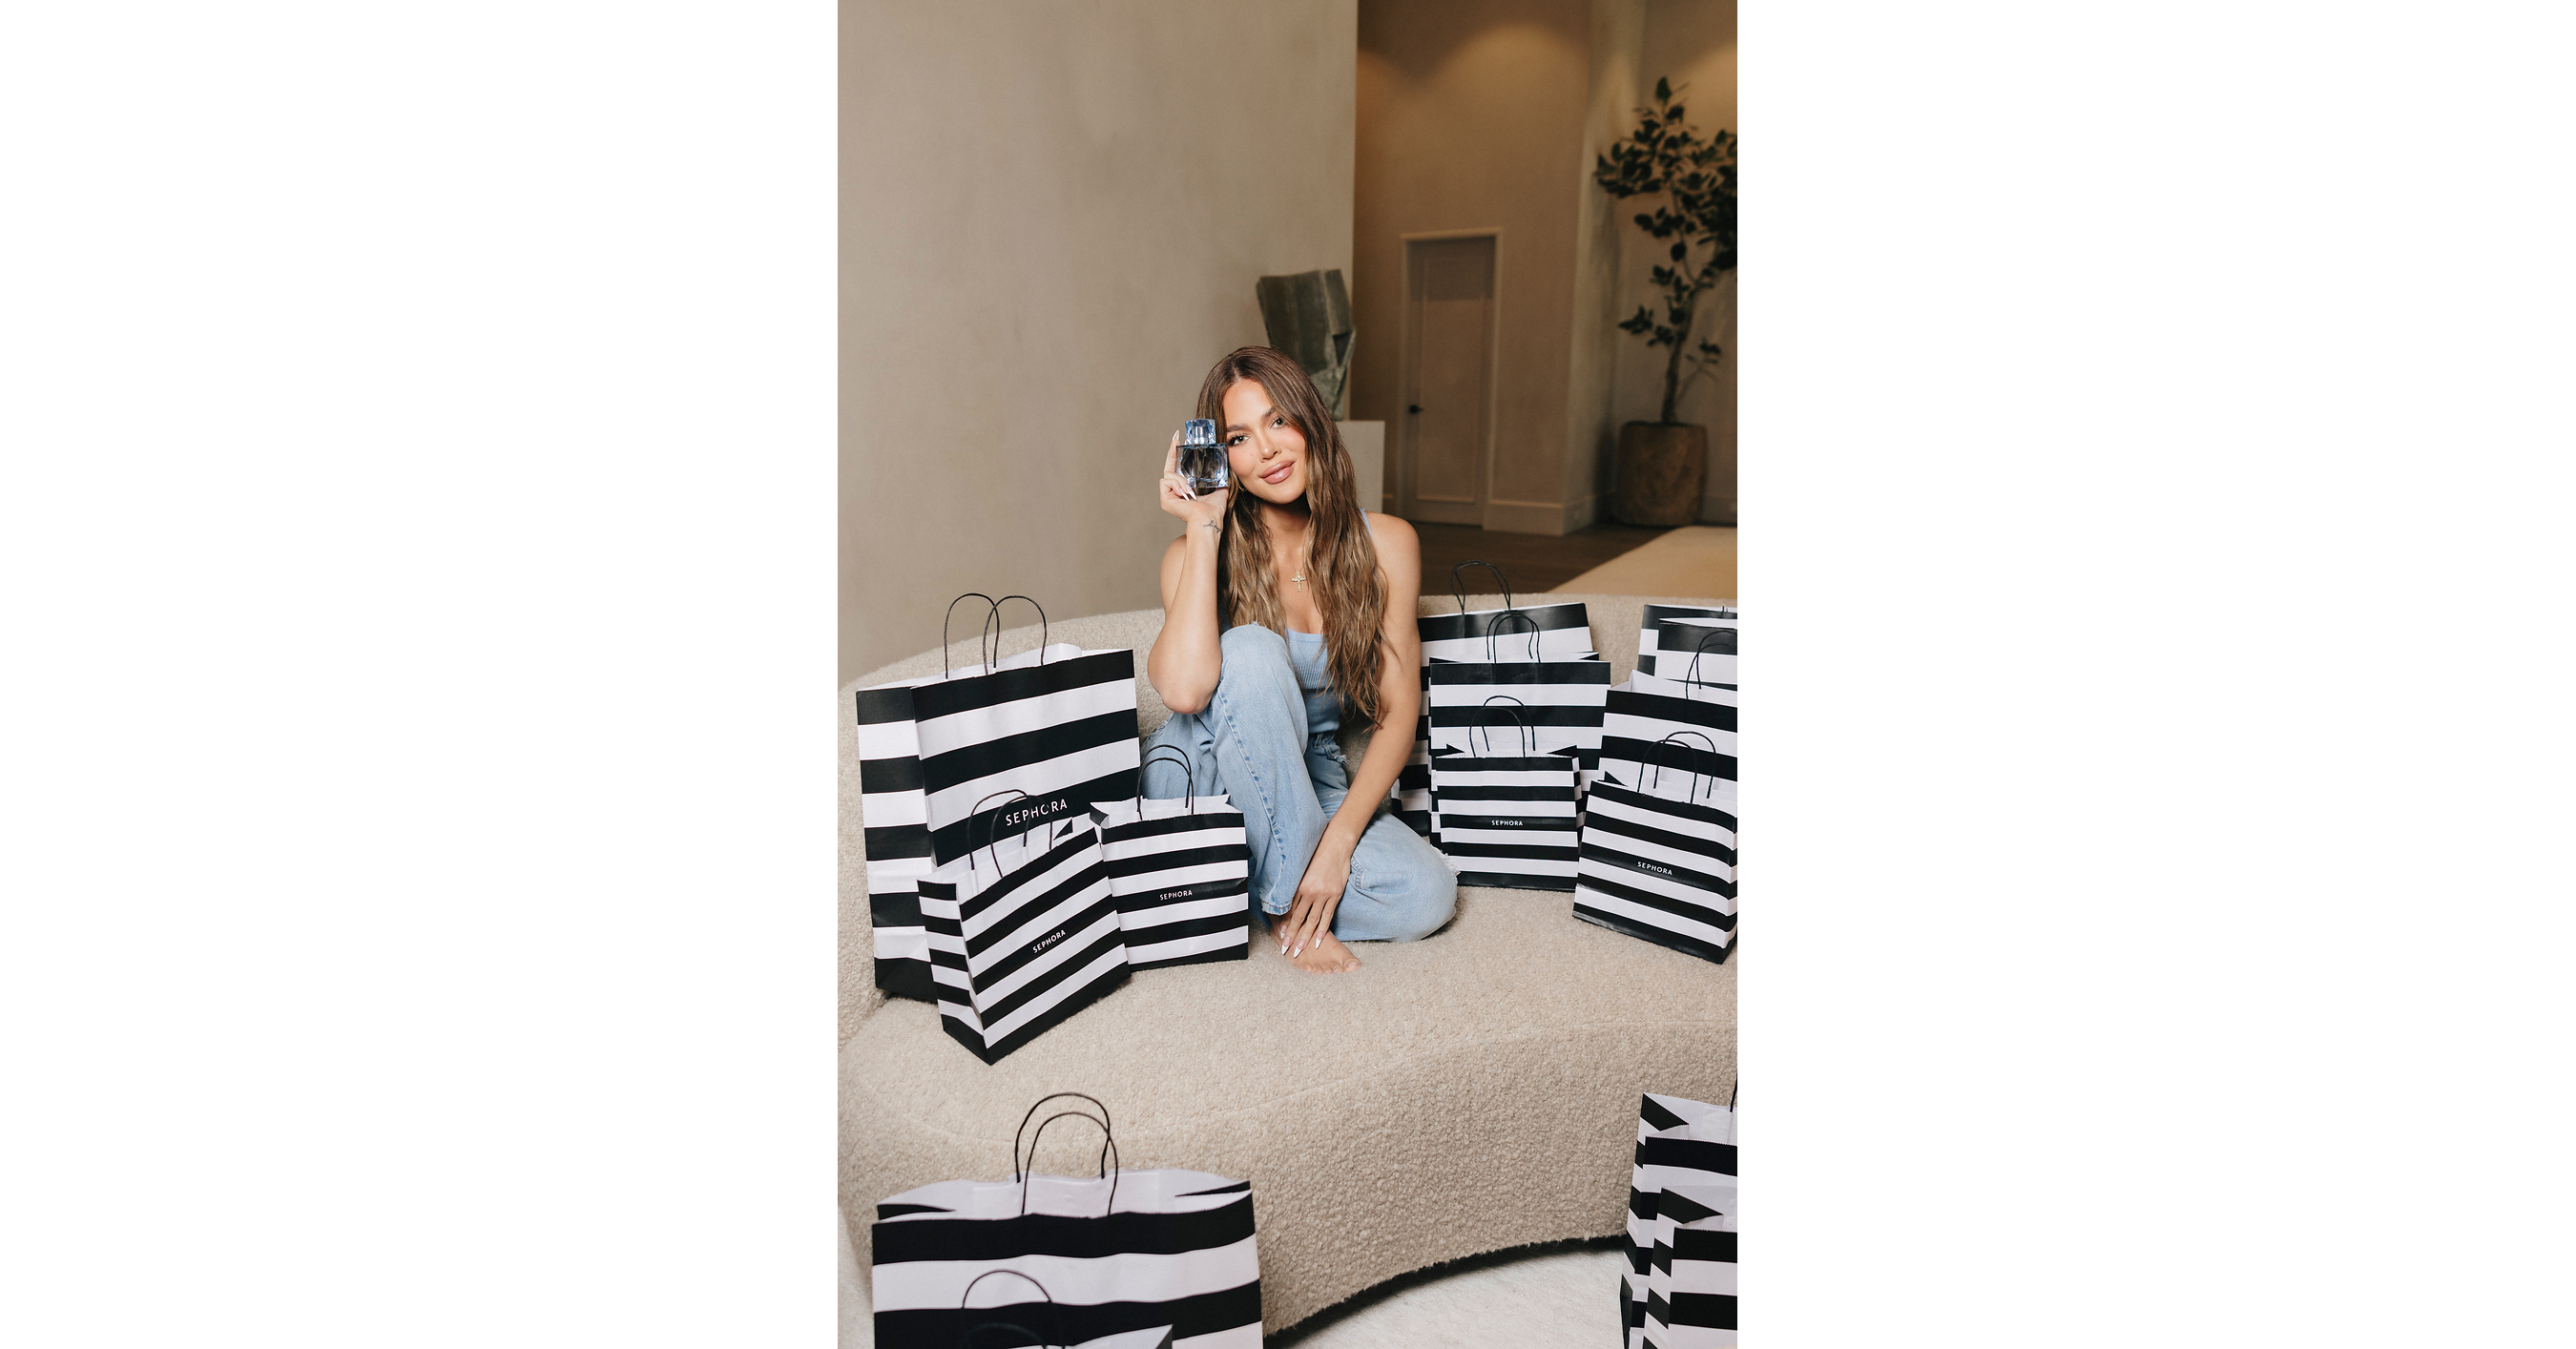
Khloé Kardashian’s fragrance portfolio, including XO Khloé, Almost Always and new XO BLUE, launched at Sephora on September 14, 2026, spanning 1,300 Sephora US and Sephora at Kohl’s locations, as well as Sephora.com. Sephora will be the exclusive Canadian retailer, with Luxe Brands positioning the North American rollout as a platform for expansion into Mexico, Brazil, India and Asian markets. The launch will be supported by a 360-degree media campaign, including advertising tied to Hulu’s "The Kardashians."
Analysis
This is not a meaningful earnings driver for GM or KSS. GM’s exposure is limited to an unrelated fragrance licensing arrangement at private Luxe Brands, while Sephora’s shop-in-shop footprint at Kohl’s provides only indirect traffic potential; neither creates a basis to revise revenue or margin estimates.
The relevant read-through is category-level: prestige fragrance has become a high-repeat, giftable traffic driver, and celebrity-led launches can improve conversion without the discounting that typically erodes specialty-beauty margins. The risk is that the launch merely reallocates wallet share from incumbent fragrance brands rather than expanding category spend; shelf productivity and replenishment data—not launch-day media—will determine whether the concept has durable value over the next 1-3 months.
For KSS, any benefit is likely too diluted across its broader store base to offset its structural apparel traffic and promotional-pressure issues. A stronger-than-expected Sephora fragrance performance could marginally support the strategic value of the Sephora partnership and reduce downside to comparable-sales expectations, but it would not change the core investment debate absent evidence of cross-shopping into higher-margin beauty and improved total-store conversion.
Contrarian view: celebrity marketing may make initial sell-through look strong while creating high return/reorder uncertainty after the paid-media burst ends. Watch November holiday replenishment and Sephora-at-Kohl’s traffic commentary; weak reorders would imply marketing-driven sell-in rather than a sustainable productivity lift.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- No standalone GM trade: the licensed-brand connection is economically immaterial; do not infer an automotive or GM consumer-products earnings catalyst.
- Maintain KSS as a watch item rather than a launch-driven long. Reassess only if management quantifies Sephora-at-Kohl’s beauty comp contribution or raises comparable-sales guidance during the next earnings cycle.
- For a retail read-through, monitor ULTA and ELF as public beauty proxies over the next 1-3 months, but require evidence that prestige-fragrance demand is incremental rather than share transfer before adding exposure.
- Set a post-holiday checkpoint for KSS: sustained improvement in beauty-led traffic, conversion, and gross-margin commentary would support reducing short exposure; continued promotional intensity or no quantified Sephora benefit falsifies any bullish interpretation.
More News
- S&P 500 pulls within 1.2% of its all-time high even as majority of its stocks fell: Broadcom, Nvidia and other AI stocks made up the difference
- Wells Fargo raises Nucor stock price target on market share gains
- Why GM and Hilton are ditching the NYSE for Nasdaq
- PENSKE AUTOMOTIVE GROUP REPORTS QUARTERLY RESULTS
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain