
DJI lanza Osmo 360 II en IFA 2026, que ofrece imágenes insignia 8K 360° para tomas épicas, de día o de noche
Source: PR Newswire
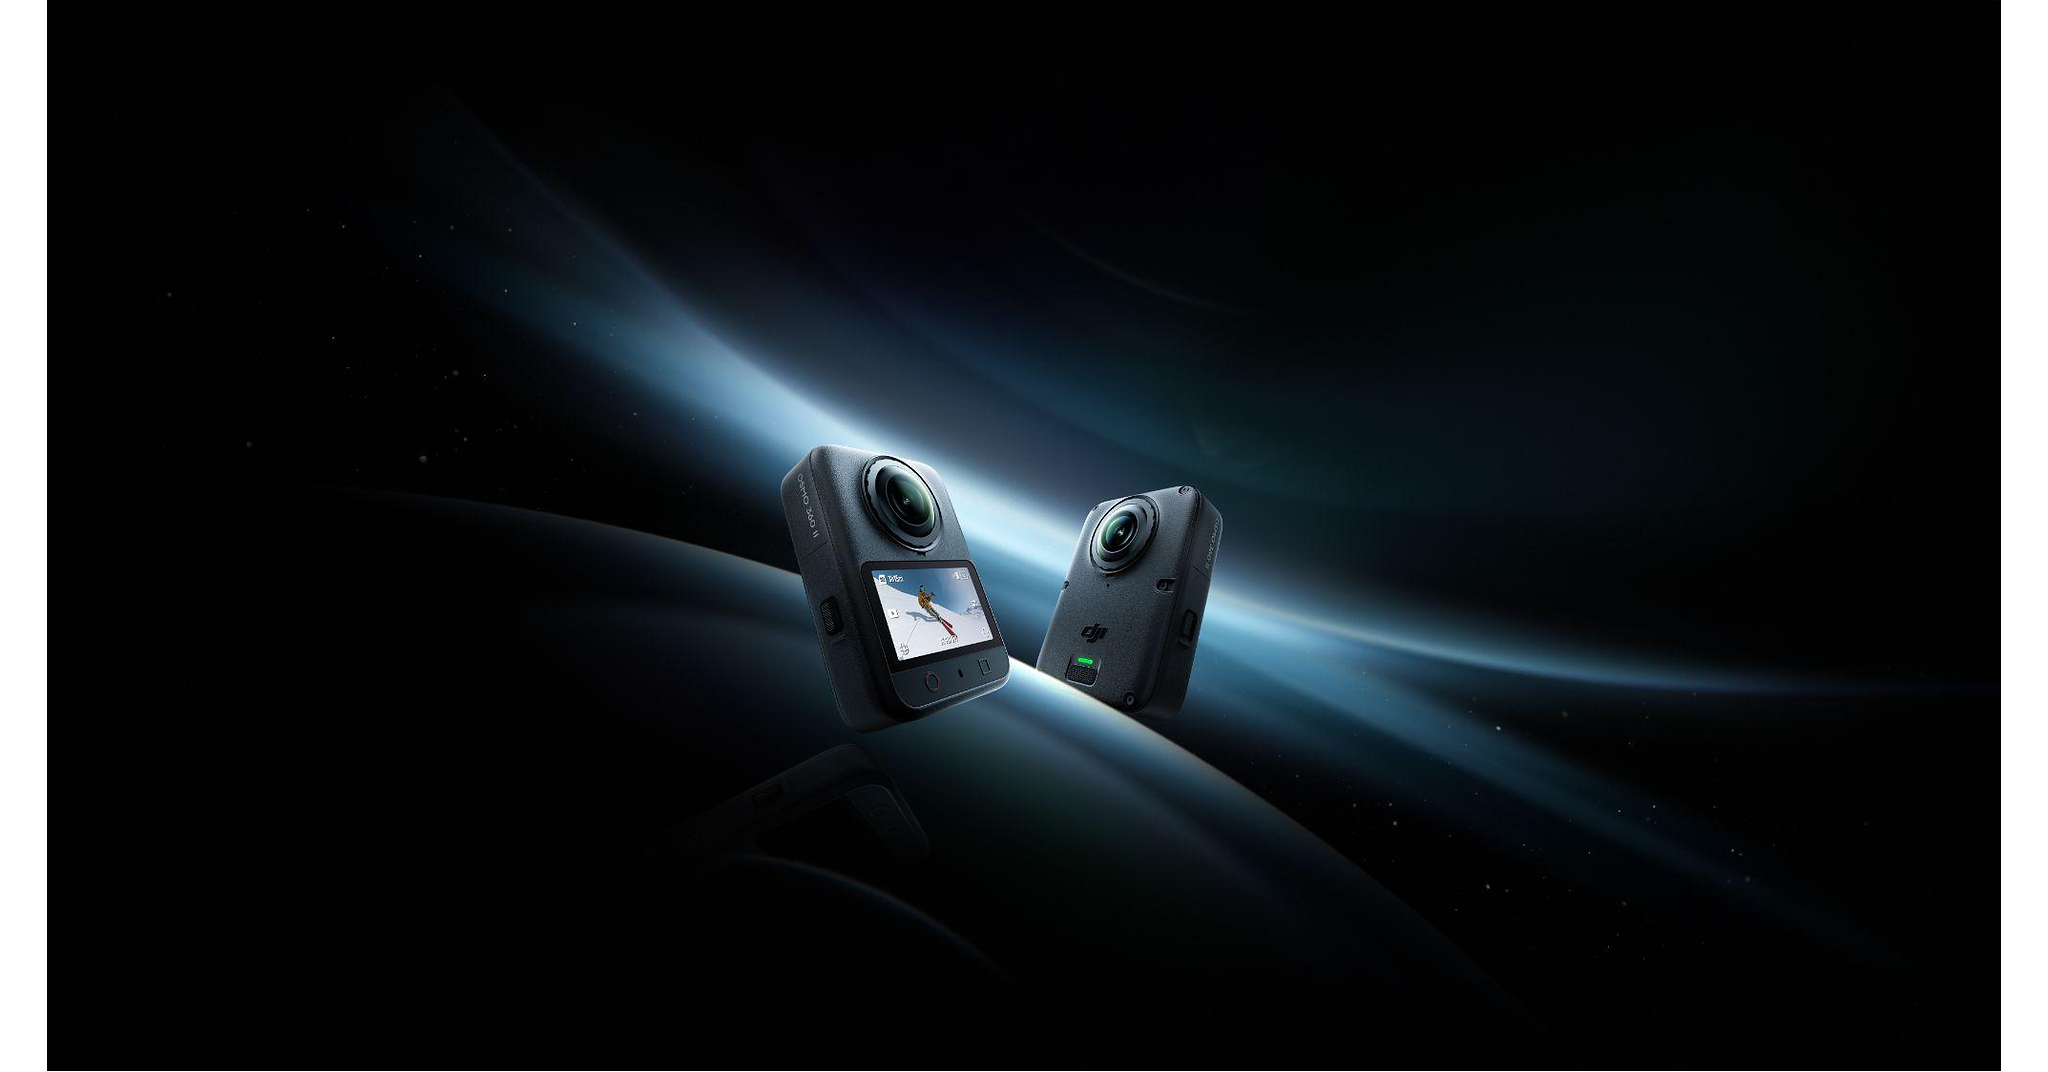
DJI lanzó la Osmo 360 II en preparación para IFA 2026, con sensor HDR de 1" y captura 8K/60 fps 360°. La cámara amplía el rango dinámico a 14.5 pasos (duplica el rango de brillo), incorpora “SuperNoche IA 2.0” y añade 105 GB de almacenamiento integrado, lentes ultraduras reemplazables, y batería con hasta 100 min de grabación continua (carga al 80% en 22 min). En España saldrá desde hoy con precios de 589 EUR (Pack Estándar) y 739 EUR (Pack Aventura), lo que representa un impulso positivo para la línea de creación de contenido 360°.
Analysis
This is less a demand shock than a competitive-barrier check. DJI is using product cadence to defend the premium end of creator hardware, but the market should treat that as margin protection first and TAM expansion second; the incremental revenue pool is likely to show up in accessories, software workflow, and repeat ecosystem purchases rather than a single camera launch. The closest public loser is GPRO: not because it loses units overnight, but because category leadership keeps moving toward vertically integrated hardware-plus-editing ecosystems, which is exactly where a standalone hardware brand is weakest.
The second-order effect is cannibalization inside DJI’s own portfolio and pressure on clone vendors. If the launch is real sell-through, the likely winners over 1-3 months are adjacent attachment points — mounts, batteries, microphones, and editing software adoption — while the base camera market remains promotional and cyclical. If channel checks do not confirm inventory pull, the move becomes mostly a sentiment event and the stock-market impact should fade quickly.
Contrarian view: the consensus may overread feature superiority as durable monetization. 360 cameras are still niche, and a better spec sheet does not automatically translate into share gains if usage remains event-driven and replacement cycles stay long. What would falsify the negative read on incumbents is a visible acceleration in GPRO unit stability or gross margin, or evidence that DJI’s launch is mainly diverting demand from its own action-camera line rather than taking share from others.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- Tactical short GPRO into any post-launch sympathy rally; use a 4-8 week horizon and keep size small because the thesis is competitive pressure, not an immediate earnings break. Cover if next quarter shows sequential stabilization in units or gross margin.
- No direct trade on DJI; treat this as a watch item until sell-through and accessory attach can be verified via channel checks, retailer data, or creator adoption metrics.
- If you want hedged exposure, consider a cautious long SONY vs short GPRO pair only if subsequent sourcing data suggests the new camera uses meaningful third-party image-sensor content; otherwise skip the pair.
More News
- Wall Street’s AI doomsday trade is here: chipmakers sink while hyperscalers gain
- What's next for oil refiners after an unprecedented run to all-time highs
- US Data Centers Set to Burn More Natural Gas Than Most Nations
- Buy this stock that offers discounted exposure to SpaceX, Morgan Stanley says
- Stocks Fall on AI Fears as 10-Year Yield Hits 5%
- Christine Lagarde: A new age of capital: growth, sovereignty and AI