
LaserPecker Set to Unveil U1 at IFA 2026: Live Demos of Intelligent UV Laser Engraving
Source: PR Newswire
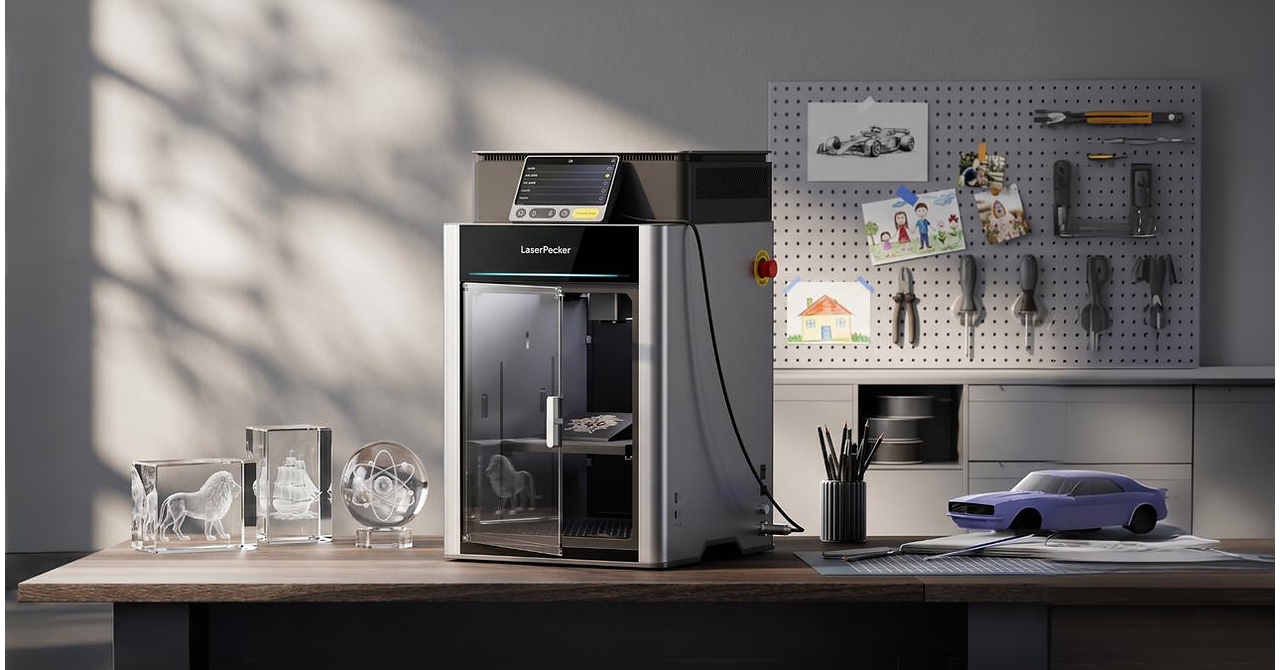
LaserPecker plans to unveil the new UV laser engraver “U1” at IFA 2026 in Berlin, offering 5W and 10W UV laser configurations. The product emphasizes sensor-based autofocus and AI-powered automation for transparent materials (including crystal auto-detection) plus automated 3D engraving on irregular/curved surfaces, with an expected launch via its website in Q4 2026. While there are no financials provided, the launch is a positive product-development signal likely to be of limited near-term market impact.
Analysis
This is more of a feature-release than a market event: the economic value sits in a niche maker/SMB category where revenue pools are fragmented and public-market exposure is thin. The real second-order angle is competitive rather than absolute — automation around transparent-material positioning lowers the skill barrier, which should pressure lower-end rivals on feature parity and shift competition from hardware specs toward software, calibration reliability, and consumables attach.
For listed names, the cleanest read-through is to photonics/laser component suppliers such as COHR and LITE, but only as a sentiment/optionality note unless channel checks show design wins. The bigger implication is for private desktop fabrication players: if this performs as advertised, it could widen the use case from hobbyist personalization into higher-frequency SMB production, which would favor companies with service/software ecosystems over one-off hardware sellers. That said, current scale is too small to matter for broad industrial ETFs in the next 1-3 months.
The contrarian view is that "AI automation" is doing a lot of marketing work here. In hardware categories, demand usually hinges on uptime, throughput, and consumable economics; if the workflow still requires frequent manual intervention, the launch will not translate into meaningful margin expansion or repeat demand. Watch Q4'26 preorder conversion and any evidence of premium pricing retention; absent that, this is likely a product-catalog update rather than a structural inflection.
Tail risk cuts both ways: if the product truly reduces setup time on transparent substrates, competitors may respond quickly, compressing differentiation and forcing promotions within 6-18 months. Conversely, if adoption is weak, the launch can become a reminder that addressable-market expansion claims are easier to announce than monetize.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate listed-equity trade: the event is too small to justify directional risk in industrials or consumer tech before channel data emerges.
- Set a watch on COHR and LITE into the Q4'26 preorder window; only get constructive if there are signs of incremental UV-laser/optics demand or design-win commentary, otherwise treat this as noise.
- If looking for a speculative expression on premiumization in desktop fabrication, prefer a small call-option position in COHR rather than stock; risk/reward improves only if multiple niche OEM launches confirm a broader upgrade cycle.
- Avoid shorting generic industrial ETFs or CRCT/consumer personalization names on this headline alone; the mechanism is too indirect and the timing too uncertain.
- Falsifier to the bullish niche thesis: weak preorder conversion, discounting at launch, or no evidence of higher repeat usage/consumables attach by the first post-launch quarter.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Asian stocks skid, Wall Street and bonds aided by oil slip
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance