
AliExpress Brand+, plataforma de lanzamiento global para la innovación de vanguardia en IFA 2026
Source: PR Newswire
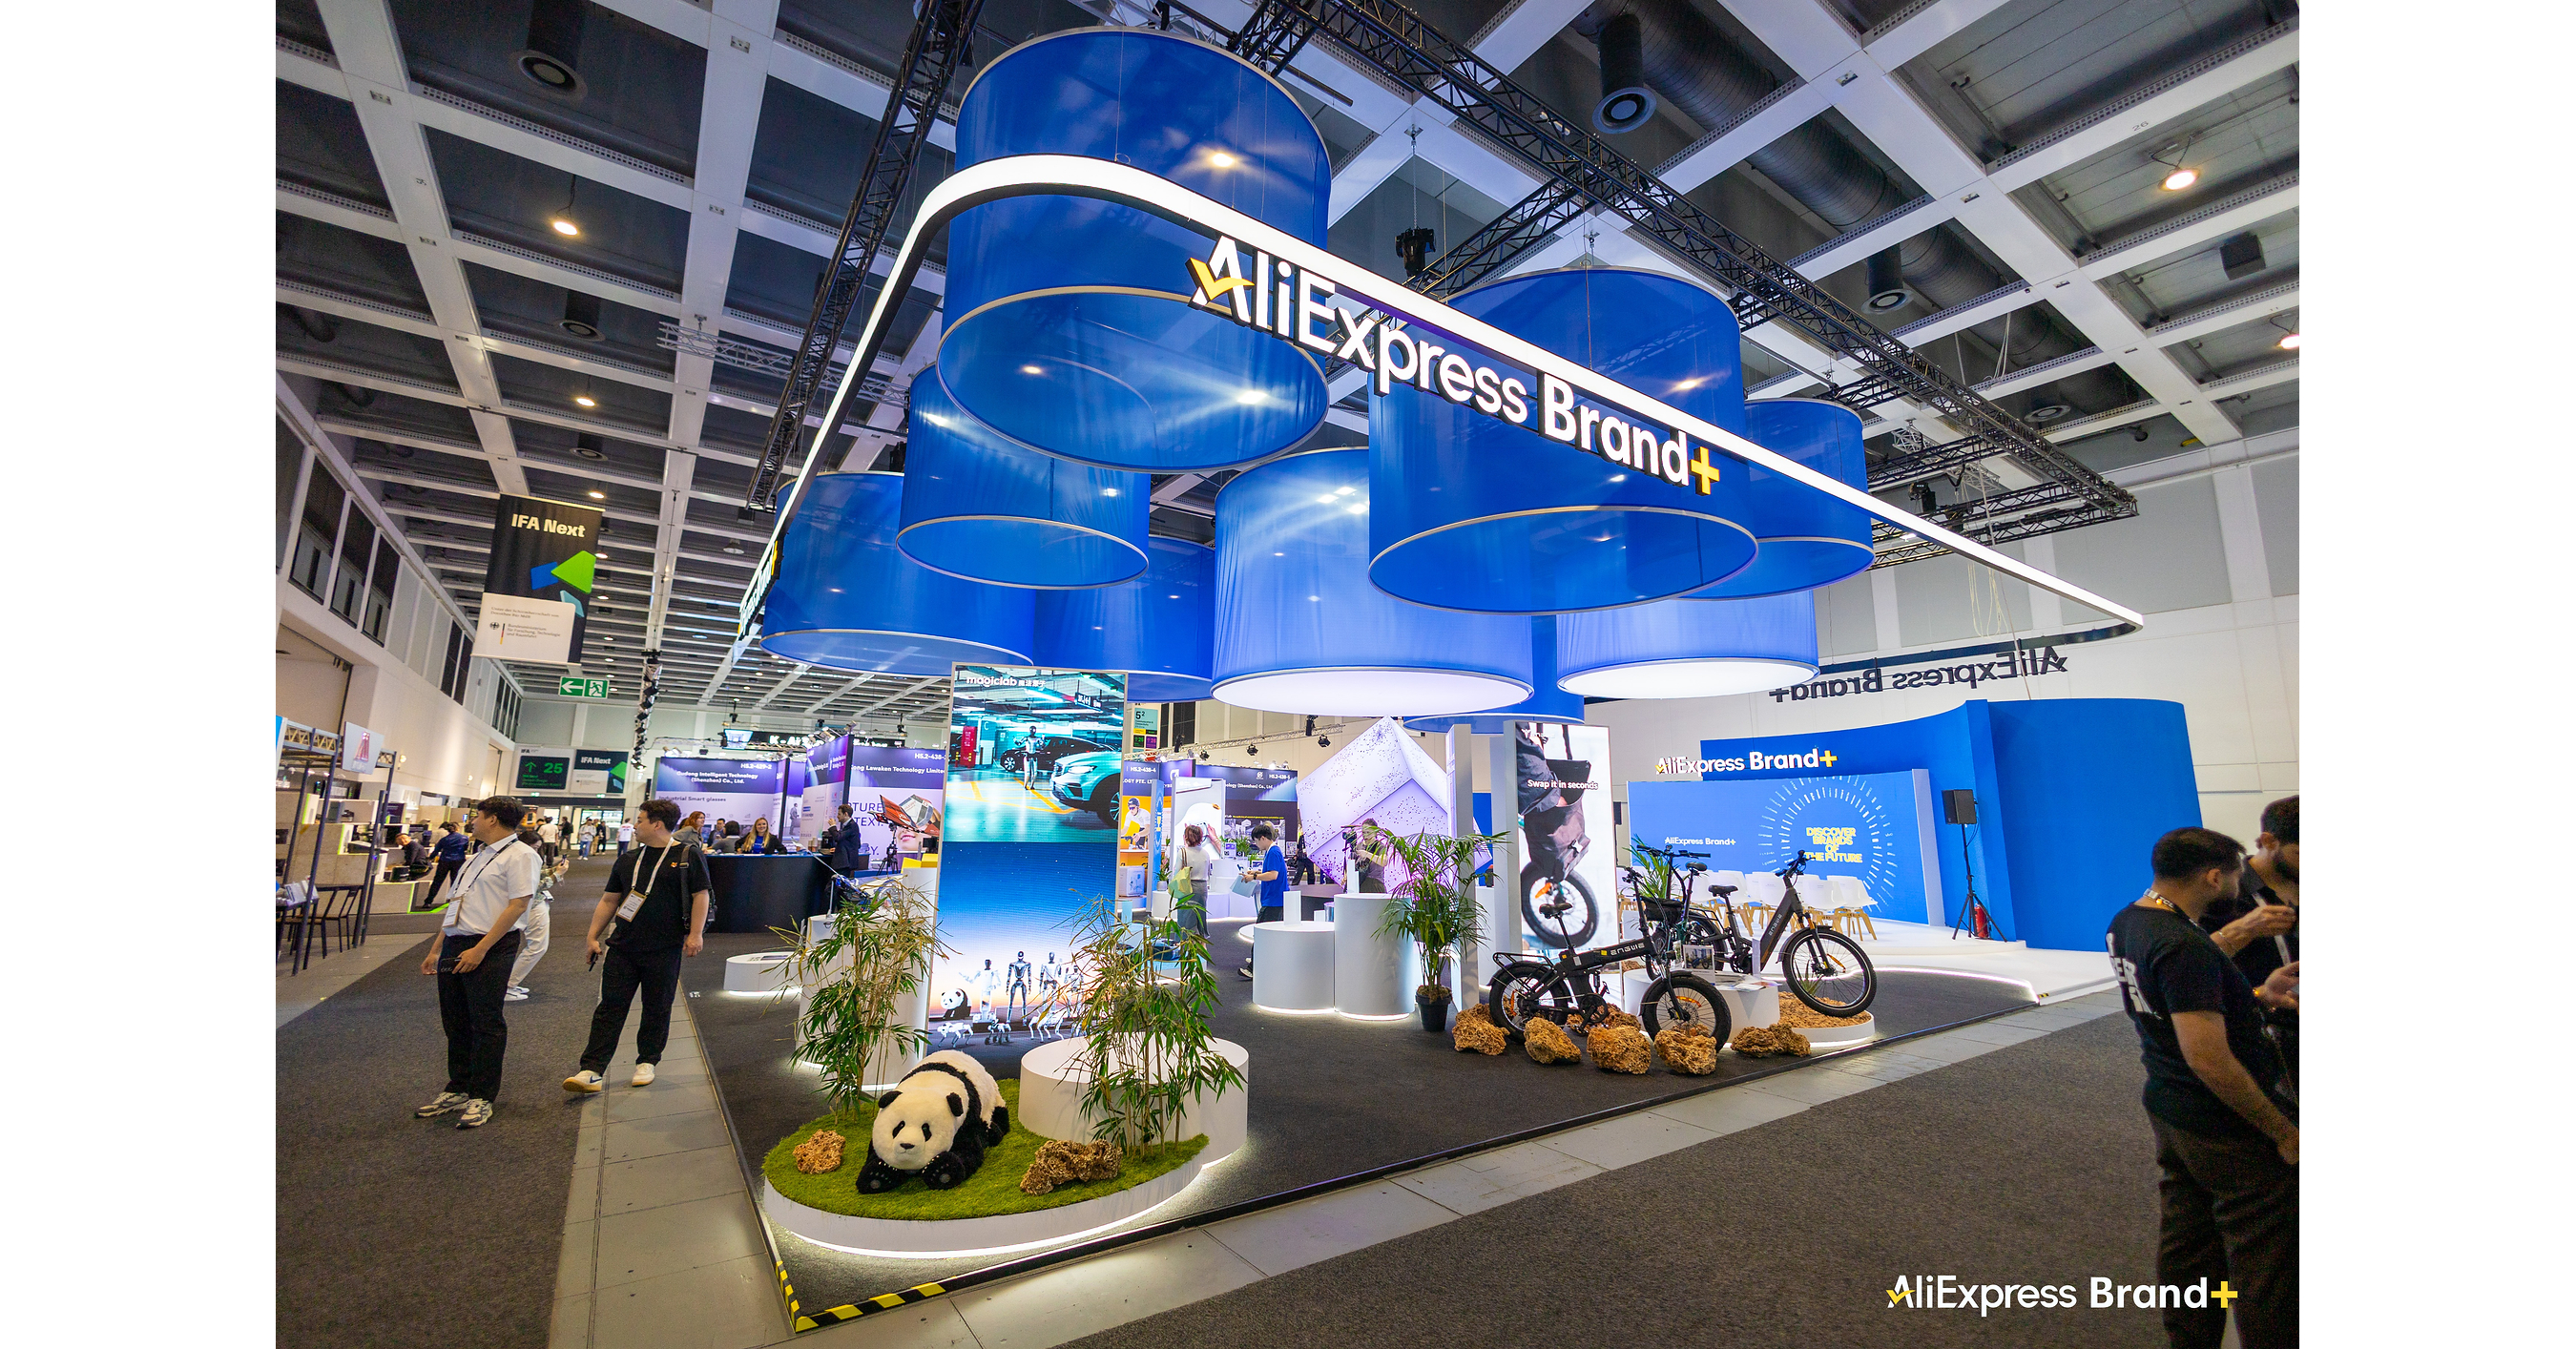
AliExpress anunció su plataforma “Brand+” para lanzar innovación en IFA 2026, incorporando con éxito a más de 1.500 marcas y alcanzando una penetración de GMV cercana al 40% durante la megaventa de mitad de año. En paralelo, los pedidos desde almacenes locales en mercados europeos clave (España, Francia y Polonia) superaron el 50% de las ventas totales, apoyados por una expansión de redes de almacenamiento/logística (incluyendo un almacén oficial en Alemania en construcción). El mensaje apunta a una adopción activa de tecnología premium por consumidores europeos, con impacto principalmente de posicionamiento/ejecución comercial más que de movimiento inmediato de mercado.
Analysis
This is more a distribution-and-mix signal than a near-term earnings catalyst. For BABA, the important mechanism is that AliExpress is trying to move the business from discount-led cross-border commerce toward a higher-trust, higher-repeat local fulfillment model; if that sticks, it can support take rates and reduce churn, which is the real driver of any multiple re-rating in International Digital Commerce. The catch is that the logistics build-out and service guarantees likely pressure contribution margins before they help reported earnings, so the market should treat this as a 6-18 month narrative, not a same-quarter P&L win.
The second-order winners are the ecosystem suppliers and brands that can use AliExpress as a demand-generation channel in Europe without relying on Amazon shelf space. The losers are price-comparison and import-friction peers like Temu and some DTC electronics brands, because local warehouses and smoother returns narrow the convenience gap more than the price gap. For AMD, the direct impact is modest: if mini-PC and edge-AI devices gain traction, it supports incremental client/embedded share, but this is not large enough to move company-wide growth unless it becomes a broader AI PC refresh cycle.
The contrarian view is that the market may be overrating the PR value of a trade-show launch. Consumer electronics discovery does not equal durable GMV, and any real adoption will depend on European regulatory tolerance, delivery reliability, and return costs over the next 1-3 quarters; if local-warehouse penetration stalls or gross margins disappoint, the sentiment uplift fades quickly. What would falsify the bullish read is evidence that international commerce growth is still coming from low-margin, cross-border volume rather than repeat local orders, or that incremental logistics spend is outpacing monetization.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- BABA: modest tactical long only on weakness into the next 1-2 earnings windows, targeting a sentiment-driven multiple expansion rather than an earnings beat; risk/reward is acceptable if international commerce margin guidance is stable, but cut if EU logistics costs rise faster than GMV.
- Pair trade: long BABA / short AMZN for 1-3 months if you want to express improving China-to-Europe commerce mix without paying for a fully valued global marketplace; thesis breaks if Amazon shows stronger EU retail acceleration or BABA signals margin dilution.
- AMD: watchlist rather than immediate trade; use any selloff in AMD to look for confirmation that mini-PC / edge-AI demand is translating into real volume, but do not underwrite a material revenue uplift until client/embedded commentary improves on the next two quarters.
- Competitive alert: monitor TME/TEMU-related spend and European warehouse commentary; if discount platforms respond with heavier subsidies or faster local fulfillment, the BABA margin uplift thesis is likely a false positive.
More News
- Alibaba Backs Chinese Robovan Maker in $400 Million Fundraising
- AI stocks bounce back after bruising selloff, CoreWeave gets Goldman upgrade
- Why this bull market is unlike any we've seen before
- AI chip startup Tenstorrent more than doubles its valuation to $6.2 billion in funding round
- TD Cowen reiterates AMD stock buy rating on AI workload strength
- Cathie Wood’s ARK sells Palantir and Shopify stock, buys CoreWeave