
Toyota Motor North America da a conocer los resultados de ventas en EE. UU. correspondientes a septiembre y al tercer trimestre de 2026
Source: PR Newswire
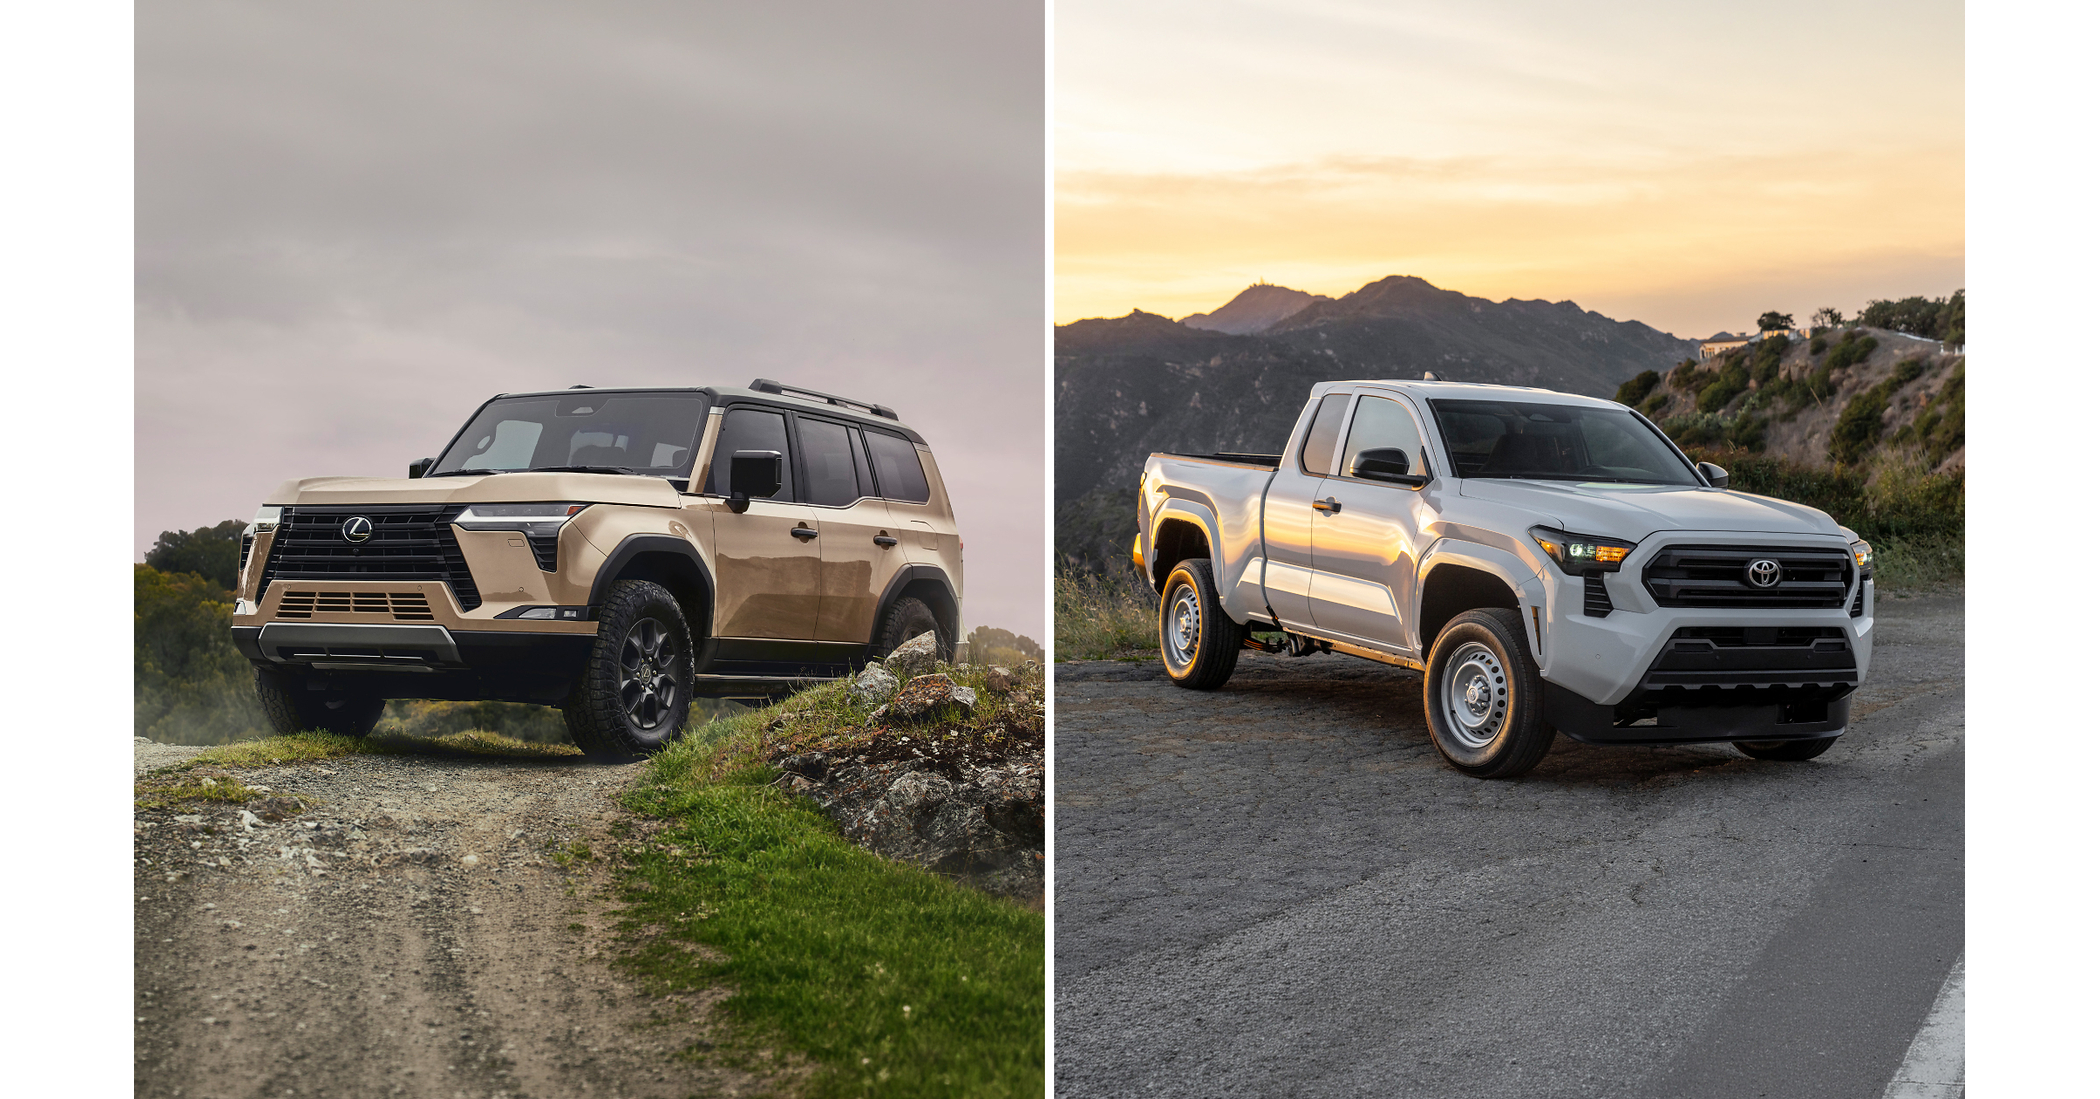
Toyota Motor North America sold 201,306 U.S. vehicles in September, up 8.4% year over year, while electrified-vehicle sales rose 37.8% to 117,215 units and represented 58.2% of total volume. Third-quarter sales were nearly flat at 633,223 units, up 0.6%, but electrified sales increased 28.5% to 363,367 units, or 57.4% of sales. Toyota cited disciplined inventory management and a 32-model electrified lineup as supporting a strong finish to 2026.
Analysis
The investable signal is mix, not unit growth. Toyota’s hybrid-led product architecture is taking share in electrified vehicles without forcing the battery-heavy, incentive-dependent economics that have pressured pure-BEV peers; this should support North American contribution margins and reduce the probability of a near-term guidance miss. The key confirmation at results is whether incentives remain contained while dealer inventory stays below roughly 35-40 days; if so, the market can justify incremental multiple support despite low-single-digit underlying volume growth.
The second-order loser is the pure-play BEV complex—especially TSLA and RIVN—if hybrid/PHEV adoption continues absorbing consumers unwilling to pay for charging infrastructure or range compromises. Toyota’s success also favors hybrid-component suppliers such as DENSO (DNZOY) and Aisin (ASEKY) more than lithium and battery-material exposure; sustained hybrid mix produces materially less battery demand per vehicle than BEV consensus forecasts imply. Conversely, rapidly growing BEV nameplates are still too small to establish a broad Toyota battery-demand inflection.
Near term, the sales release alone is unlikely to move TM materially because US operations are only one piece of consolidated earnings and FX/Japan production remain larger variables. Over the next 1-3 months, the catalyst is FY guidance and disclosure of North American transaction prices, incentive spend, and hybrid mix; a positive read-through requires margin resilience rather than further volume acceleration. The contrarian risk is that electrified penetration reflects availability and model transitions rather than durable pricing power: rising inventory, a material incentive step-up, or weaker RAV4/large-SUV demand would quickly turn the mix narrative into discounting risk.
Structurally, Toyota’s flexible powertrain strategy may earn a valuation premium versus legacy OEMs, but it also creates a 6-18 month regulatory risk if US emissions rules or consumer incentives increasingly favor zero-emission vehicles. The thesis is falsified by a sequential deterioration in North American operating margin, incentives rising faster than retail volume, or a material downward revision to FY production/earnings guidance.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Maintain/accumulate TM on post-release weakness rather than chase the sales print; use a 3-6 month horizon targeting upside from North American margin and guidance durability. Risk/reward is favorable only if management confirms stable incentives and inventory discipline at earnings; exit on a clear North American margin-guide cut.
- Initiate a 3-6 month relative-value basket: long TM and/or DNZOY versus short TSLA, sized modestly. The thesis is hybrid substitution and lower discounting intensity; stop out if Tesla pricing stabilizes while Toyota’s incentive rate rises materially or hybrid mix rolls over.
- Avoid adding long exposure to lithium/battery-material proxies solely on Toyota’s electrification data. Set an alert for Toyota BEV mix reaching a sustained mid-single-digit share of US deliveries or announced battery-capacity utilization increases; absent that evidence, the sales mix is more supportive of hybrid suppliers than upstream battery demand.
- At Toyota earnings, prioritize three watch items before increasing exposure: North American operating-profit outlook, incentive/transaction-price trends, and dealer days’ supply. A combination of flat-to-up pricing, low inventory, and maintained guidance is the actionable confirmation; unit sales alone is not.
More News
- Paramount Debt Drop Spells Trouble for Borrowers: Credit Weekly
- After threatening to ban U.S. exports of diesel fuel, Trump admits ‘we were never going to do it’
- David Ellison just brought in a co-CEO to run his new empire: Meet Ynon Kreiz
- How Nvidia, Micron and a surprising jobs report drove last week's stock action
- Tesla’s Cybercab had a rocky first month in Austin. Now comes the hard part: expanding
- Trump teases more inflationary money for voters ahead of midterm elections, now promising $90 payments after touting $500 and $5,000 checks
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations
- Selecting an AI Research Platform for Institutional Investors