
BS PHARM KOREA Strengthens INHILO+ Market Development Through Distribution and Clinical Collaboration
Source: PRWeb
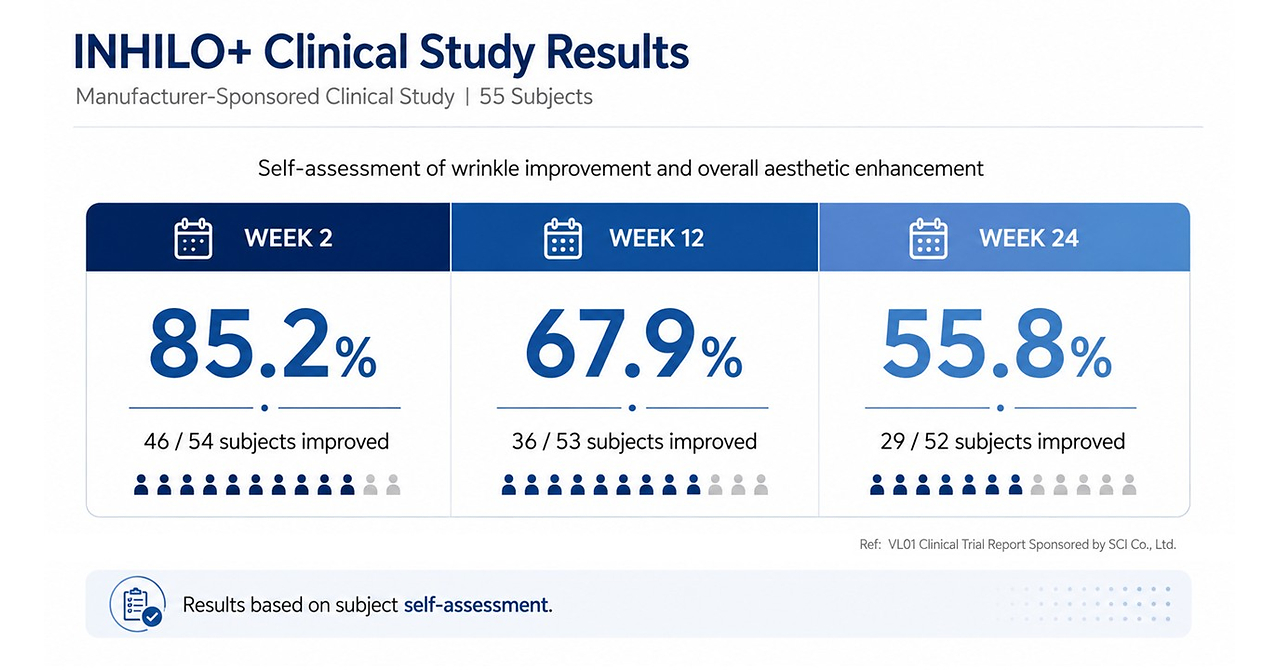
BS PHARM KOREA is advancing INHILO+ (Dual-Molecular HA, 48mg/2mL with 24mg high-MW + 24mg low-MW) via clinical and commercial expansion in South Korea. In a manufacturer-sponsored study of 55 subjects, reported improvement rose to 85.2% at Week 2, then declined to 67.9% at Week 12 and 55.8% at Week 24. The company also partnered with Dongkook Pharmaceutical for domestic distribution (from Feb 2026) and is running an additional ongoing standardized clinical evaluation, while planning international outreach at Dubai Derma 2026 (Sep 8–10).
Analysis
This reads more like a commercialization check-box than a fundamental inflection. In aesthetics, distribution access and physician trust drive sell-through far more than formulation language, so the real question is whether the partner can convert conference visibility into repeat clinic orders; if not, the economic value stays close to zero despite headline visibility. For a small product company, the margin pool is likely to be consumed by education, sampling, and channel incentives before any meaningful operating leverage appears.
The second-order winner, if any, is the domestic distributor and the broader Korean aesthetic ecosystem rather than the issuer itself. Established names with brand recognition and export infrastructure—Hugel, Classys, APR—can benefit from incremental category awareness, while undifferentiated filler/booster products face price compression as physicians compare outcome durability and training support. A broader Middle East push can help, but Dubai congress traffic is usually a lead-gen event, not a revenue event, so the market is likely to overestimate near-term monetization.
Risk is mostly 1-3 months: if follow-up data fail to show durability beyond the initial window, or if any safety/claims scrutiny emerges, the commercial narrative can unwind quickly. Over 6-18 months, the thesis depends on signed distribution economics and repeat ordering, not more slides or self-assessment data. The contrarian view is that the market may be underpricing how hard it is for a single-product aesthetic launch to scale without a strong KOL network and a proven reorder curve; this is more watchlist than trade until hard procurement evidence appears.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in the issuer; treat this as a low-conviction commercialization PR until there is disclosed order volume, repeat-clinic adoption, or ex-Korea partner announcements.
- If you want sector exposure, prefer long Hugel (145020.KQ) or APR (278470.KQ) on weakness versus chasing small-cap aesthetic launch stories; these names have better brand capture if Korean aesthetics sees incremental international interest.
- Set a 30-60 day alert for any Dongkook-led sell-through data or distributor commentary; if there is no evidence of repeat orders after Dubai Derma, fade the story and avoid paying up for growth optionality.
- Watch for any MFDS/claims scrutiny or adverse-event chatter; that would be the fastest thesis breaker and likely compress multiple in the broader Korean aesthetic basket.
- If the stock is liquid enough to trade, the cleaner expression is a short-duration event fade into the congress window rather than a long-term position; risk/reward is skewed by low fundamental visibility.
More News
- Elon Musk says SpaceX and Tesla exploring largest merger in history
- Jio’s Record $3.2 Billion IPO Puts India’s Market Muscle to the Test
- Asia stocks rebound as SpaceX, Super Micro results lift chipmakers
- Australian data center operator NextDC's shares plunge 40% after it slashes earnings forecast
- Neoclouds Lose Silver Lining as Elice, CoreWeave Dive: Evening Briefing Americas
- Anthropic May Spend $750 Billion on Computing Costs, WSJ Reports