
JLL Reports Financial Results for Third-Quarter 2026
Source: PR Newswire
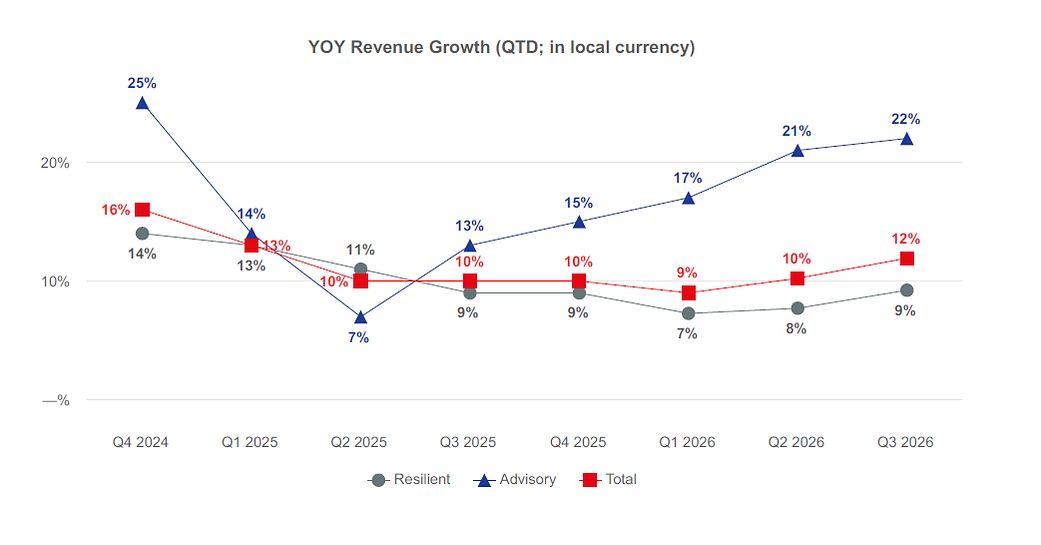
JLL reported record third-quarter 2026 diluted EPS of $6.85, up 49% in USD, on revenue of $7.3 billion, up 12%; Adjusted EBITDA rose 33% to $460.2 million. The company raised its full-year Adjusted EPS target range, with the midpoint implying 37% growth, and announced an imminent $500 million accelerated share repurchase, taking full-year repurchases above $1 billion. Leasing Advisory revenue grew 27% and Capital Markets Services revenue rose 21% in local currency, while Investment Management revenue declined 7% in local currency.
Analysis
The earnings quality is positive, but the key question is whether unusually strong advisory activity is durable. Leasing and capital-markets fees carry more operating leverage than recurring management contracts; that boosts incremental earnings in an upcycle but leaves JLL more exposed if deal sizes or transaction volumes normalize. U.S. outperformance versus reported market volumes suggests share gains or favorable deal mix, not simply a broad volume recovery—verify whether that persists in the next quarter. Higher project-management revenue also supports the recurring base, although pass-through costs inflate reported revenue without equivalent fee economics.
Near term, guidance confidence and the announced repurchase support sentiment. The buyback can lift per-share results, but should not be mistaken for a substitute for durable cash generation: nine-month free cash flow remains modest relative to planned repurchases, and working-capital timing may be material. Low leverage provides capacity, but repeated repurchases ahead of cash conversion would reduce flexibility. CBRE and Cushman & Wakefield may also benefit from improving transaction activity, so sector-wide optimism is not necessarily JLL-specific.
Over 1–3 months, focus on Q4 pipeline conversion, U.S. deal-size trends, and whether margin gains persist after lower loan-related expenses roll off. Over 6–18 months, the structural upside is a larger, steadier fee base from workplace, project-management, and data-center work; the counter-risk is that transaction-led earnings prove cyclical. The contrarian risk is treating peak-like advisory growth as a new baseline. No valuation data is supplied, so avoid assuming the positive operating news is underpriced.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- Maintain or initiate a modest long JLL position on post-earnings weakness rather than chase an opening gap; add only if management commentary confirms pipeline conversion and the raised outlook is supported by core operating trends.
- Use the next report as a thesis check: reduce exposure if U.S. leasing growth and investment-sales activity decelerate materially, or if margin expansion reverses as lower loan-related expenses cease to help.
- Monitor nine-month operating cash flow/free cash flow and repurchases together. Treat continued buybacks as supportive only if cash conversion improves; flag any sustained gap between cash generation and capital returns as a balance-sheet-flexibility risk.
- Prefer JLL over a broad commercial real-estate-services exposure only if subsequent results demonstrate persistent share gains versus market activity; otherwise, the recovery may accrue broadly to competitors such as CBRE and Cushman & Wakefield.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong
- Microsoft's Big Bets on AI Start to Pay Off