
Brennan Investment Group Closes Strategic 22-Building Industrial Portfolio
Source: PR Newswire
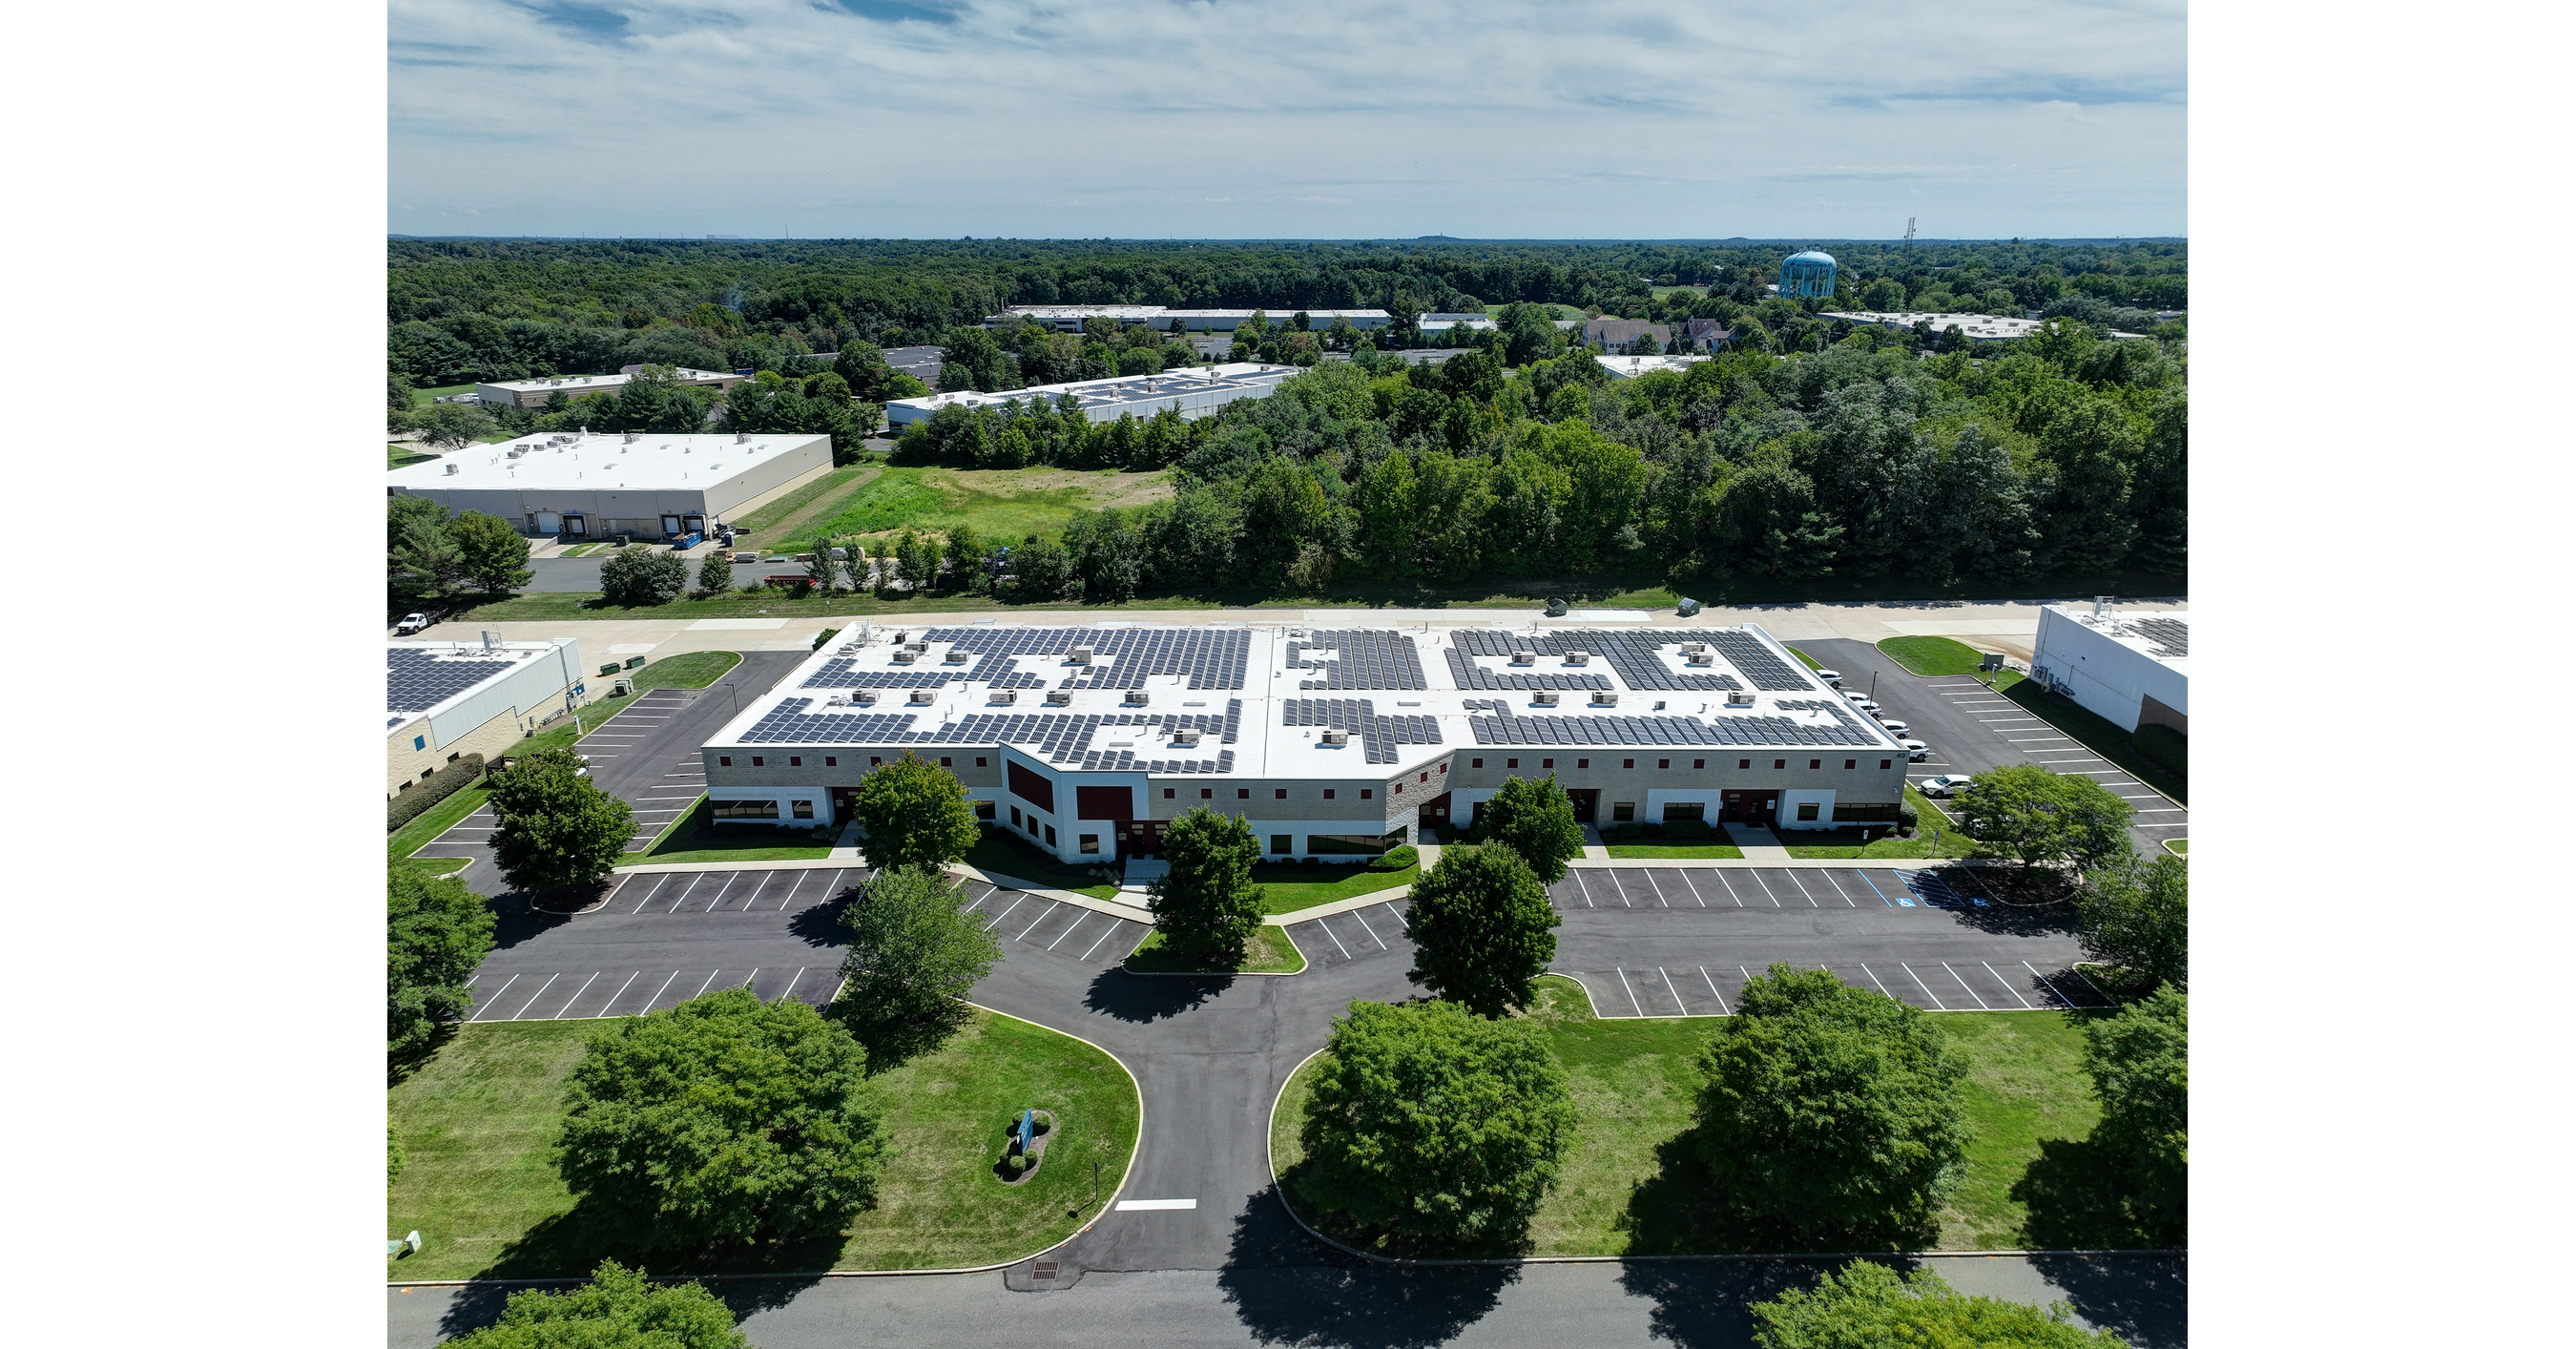
Brennan Investment Group completed the recapitalization of two industrial portfolios totaling 1,176,122 sq. ft. across Moorestown, NJ (20 buildings) and Nashville, TN (2 buildings), which are 94% leased. The deal marks the firm’s third recapitalization of the Moorestown assets (originally acquired in 2017) and is expected to support ongoing value-add via leasing and capital improvements. Overall, the transaction reinforces Brennan’s liquidity/value-creation strategy in supply-constrained infill industrial markets.
Analysis
The important signal is that private capital is still willing to finance shallow-bay, infill industrial with embedded leasing upside. That matters because this segment is valuation-sensitive but not purely duration-sensitive: if investors can still recap assets after multiple hold periods, it implies a functioning bid for cash-flow-plus-repositioning stories and a floor under replacement-cost arbitrage.
The clearest beneficiaries are public industrial landlords with similar portfolios and access to cheap capital, especially PLD, TRNO, STAG and FR. The second-order loser is the owner of functionally obsolete small-bay stock with office-heavy layouts or weak access; those assets need capex just to stay relevant, while the better-located product can keep extracting rent growth and occupancy gains. This also supports local mortgage lenders and non-bank capital providers that can finance bridge/recap structures, but only so long as transaction liquidity remains open.
Contrarian takeaway: this reads more like a liquidity recycling event than a broad-demand breakout. A third recap of the same asset base suggests sponsors are monetizing matured value-add rather than discovering a new growth regime, so the market should not extrapolate this into a clean re-acceleration for all industrial REITs. The key falsifier is a 50-100 bps cap-rate backup or a meaningful slowdown in leasing spreads over the next 1-3 quarters; that would quickly turn the current private-market optimism into stale inventory risk.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Do not trade FCD.UN.TO on this headline; the signal is too indirect and the article is a weak read-through for a Canadian retail REIT.
- If you want a cleaner expression, go long PLD or TRNO versus short VNQ for a 1-3 month relative-value trade. The thesis is that industrial NAV support should outlast broad REIT multiple pressure if rates stay range-bound; target 3-5% relative outperformance, cut if the 10-year yield breaks above 4.5%.
- Keep STAG and FR on a buy-the-dip watchlist rather than chasing. Add only if upcoming prints confirm stable occupancy and mid-single-digit leasing spreads; if same-store NOI decelerates or cap rates widen, the private-market floor thesis is wrong.
- Avoid shorting industrial REITs aggressively here. The crowd is already leaning on higher-for-longer, and recurring recap activity can keep the sector's valuation floor intact for another 1-2 quarters unless transaction volumes roll over sharply.
More News
- Attack on Saudi airport kills 12 people and wounds more than 300—the deadliest strike in any Gulf Arab country since the start of the Iran war
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Trump says he’s evaluating whether the U.S. should join Saudi Arabia’s fight against Iran-backed Houthi rebels in Yemen after fresh attacks on Riyadh
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Fixed Income Compass for October 2025: Navigating Policy Divergence and Political Risk
- AI Equity Research Tools for RIAs and Wealth Managers