
The Wait Is Over: A New Chapter of the Wonderful World of Wonka Arrives
Source: PR Newswire
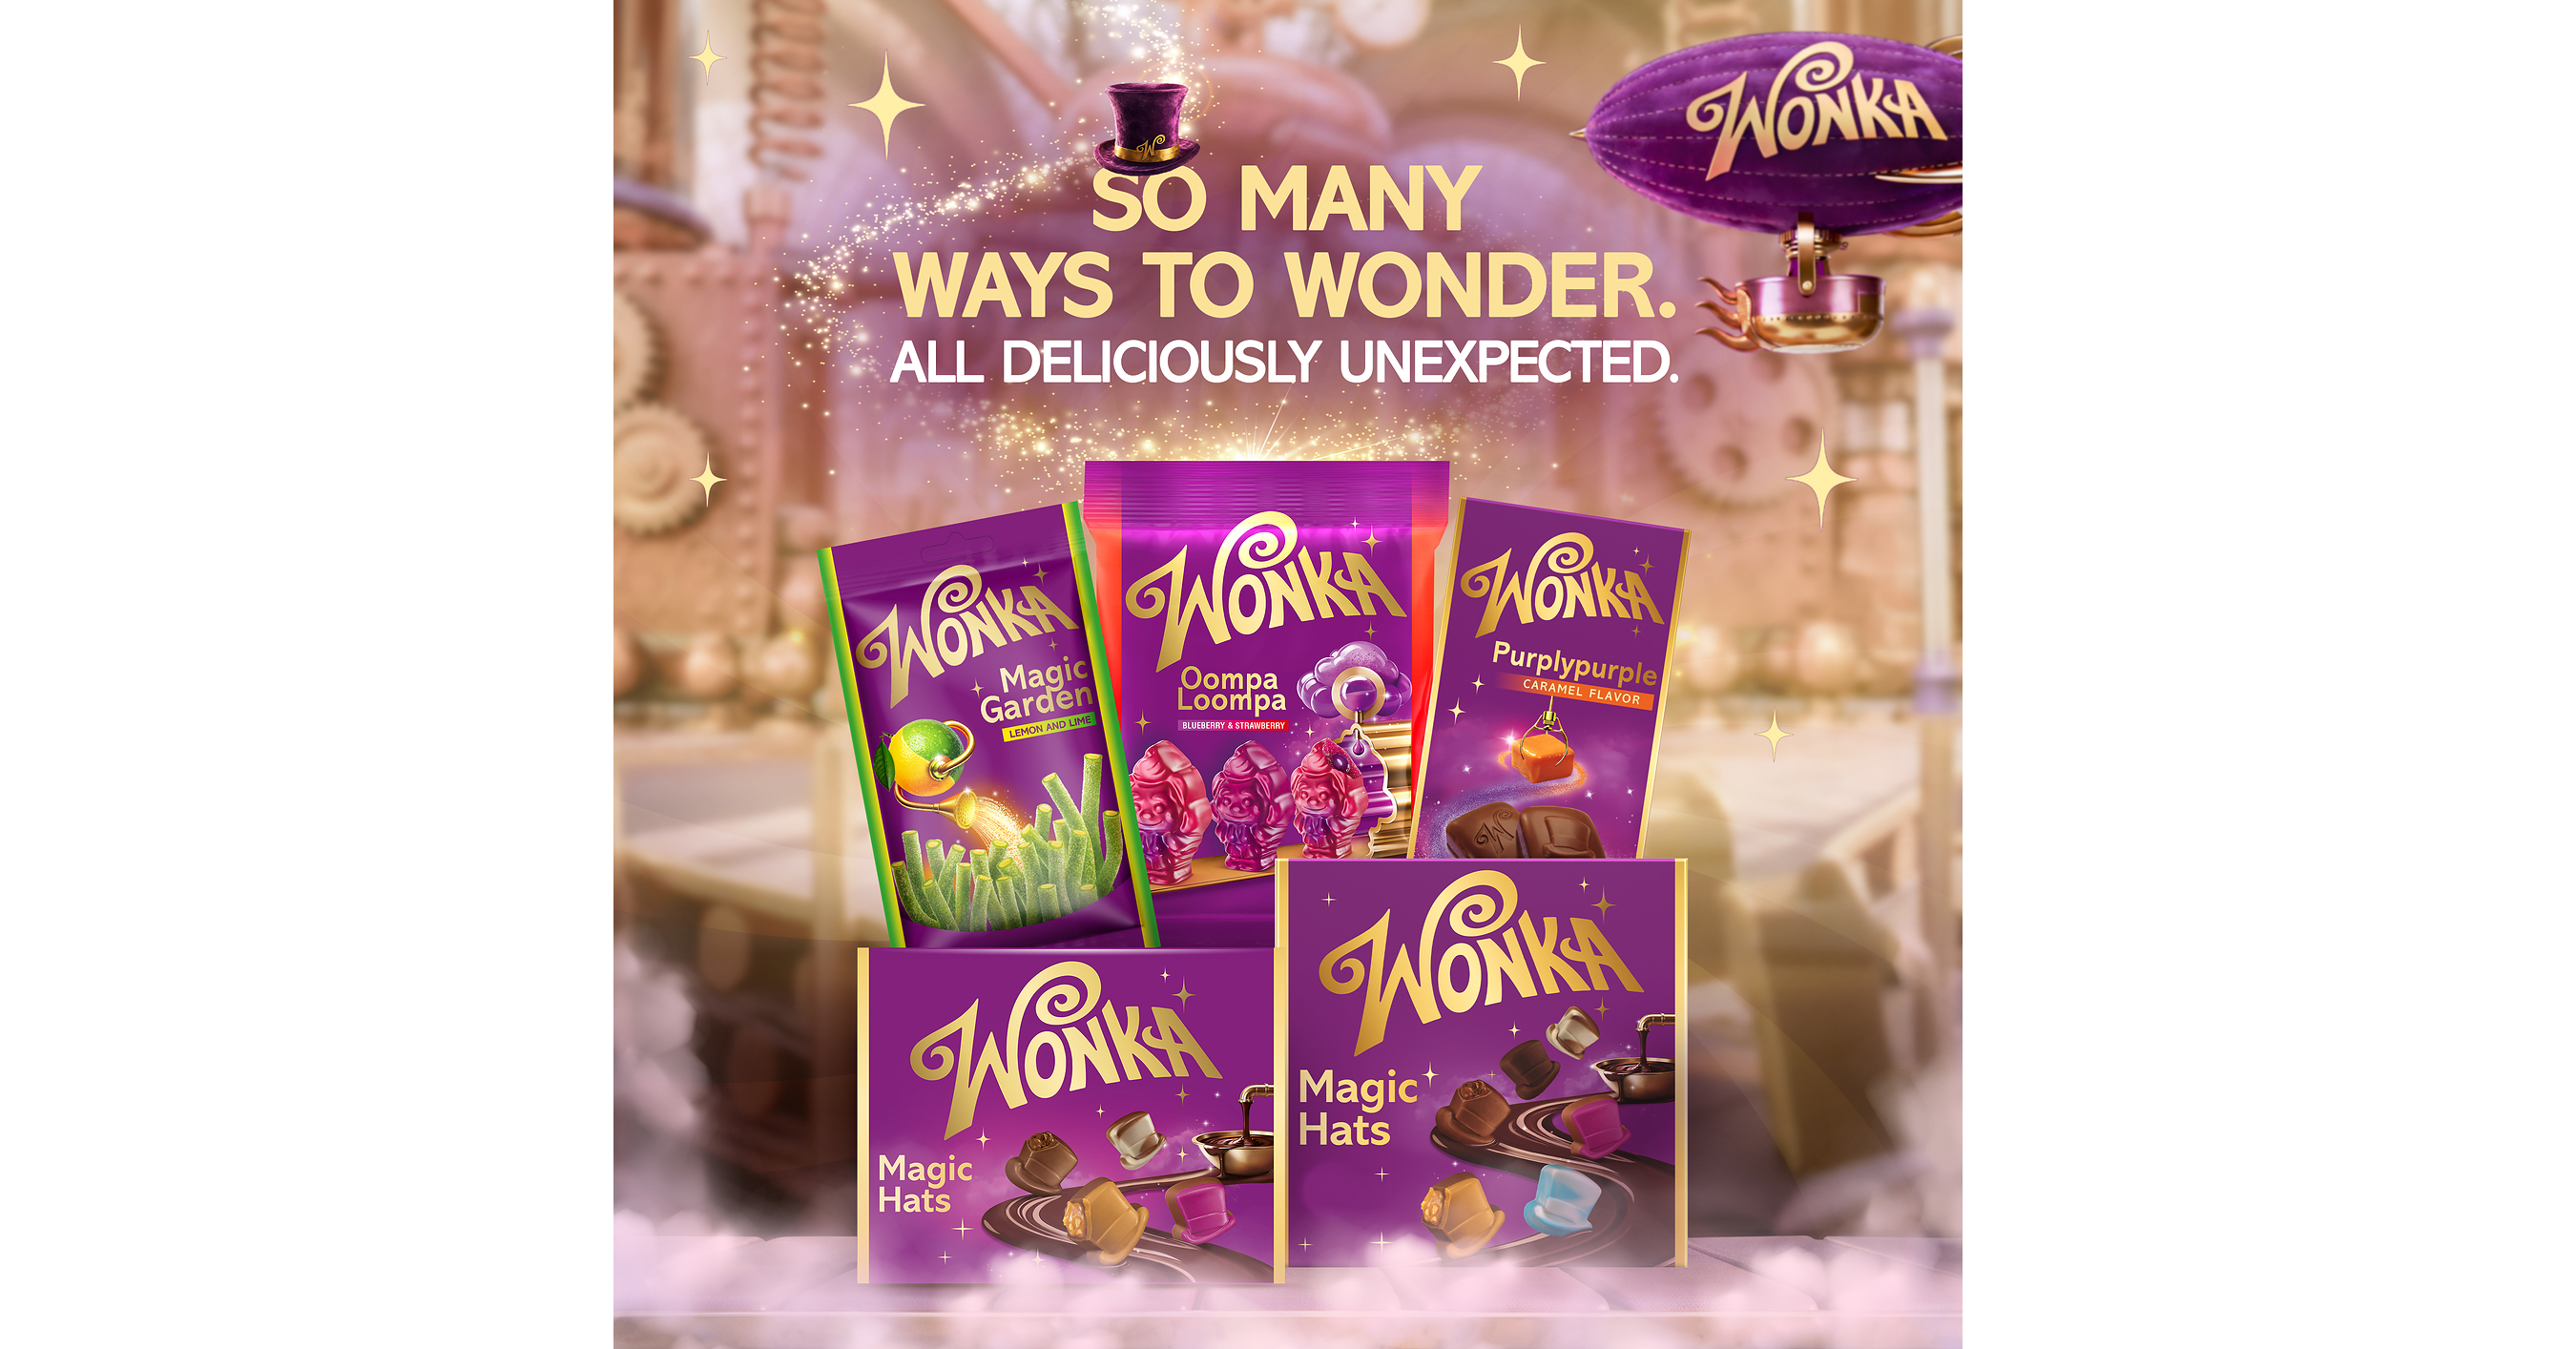
Ferrero North America will launch four limited-edition Wonka confectionery products in November, spanning chocolate pralines, a filled milk-chocolate bar, chewy ropes and gummies. The launch is paired with a global Netflix partnership and a QR-code-based digital Golden Ticket promotion, with winners receiving a trip for four to Netflix House in Las Vegas when it opens in 2027. The initiative aims to drive holiday-season engagement and extend Ferrero's Wonka portfolio through entertainment-linked, interactive retail marketing.
Analysis
This is immaterial to NFLX near-term financials: a branded consumer promotion is unlikely to move subscription, advertising, or content-margin estimates. Its investable relevance is instead as low-cost evidence of Netflix extending IP into physical retail and destination experiences, which can improve franchise monetization and reduce reliance on hit-driven streaming economics over a 6-18 month horizon.
The more relevant read-through is competitive. Netflix's advantage is the ability to coordinate content discovery, consumer products and future location-based experiences without paying a traditional studio an external distribution toll. Disney (DIS) remains structurally better positioned in global licensing and parks, but Netflix can target adult and young-adult franchises with a lighter-capex model; the key question is whether this becomes repeatable beyond a single legacy-property promotion.
Consensus should not capitalize a confectionery tie-in into NFLX valuation. The signal becomes material only if Netflix House demonstrates paid attendance, merchandise conversion and repeatable brand-partnership economics; otherwise, these campaigns are marketing support rather than a new profit pool. Near-term risk is execution: weak consumer engagement would not hurt NFLX earnings, but it would challenge the multiple-expansion narrative around ancillary revenue.
No standalone trade is warranted from this announcement. Monitor NFLX's next earnings commentary for disclosed consumer-products revenue, Netflix House opening cadence, partner economics, or evidence that physical experiences reduce customer-acquisition costs; absent those metrics, the financial impact remains below the threshold for an estimate change.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- Maintain existing NFLX exposure; do not add solely on this launch. Reassess over the next 1-3 quarters if management quantifies licensing, merchandise, or location-based-experience revenue and margin contribution.
- Set an event-driven alert for Netflix House operating details before its 2027 opening: ticket pricing, capacity, tenant/partner rent structure and upfront capex are the missing inputs needed to assess whether ancillary IP monetization merits a valuation premium.
- For relative-value positioning, favor NFLX over DIS only if NFLX can demonstrate incremental high-margin licensing/experience revenue without material capex. Falsify that thesis if disclosures indicate heavy fixed-cost commitments or if subscriber/advertising growth decelerates while ancillary revenue remains undisclosed.
- Avoid shorting confectionery peers or taking a consumer-staples position on this news: Ferrero is private and the limited-edition format provides no observable public-equity earnings sensitivity.
More News
- May Mobility's SPAC Merger: Is This a Road to Nowhere for Investors?
- Paramount Settlement Triggers WBD Breakout. How It Compares To Past Media Mergers.
- Why Marathon Petroleum Stock Slipped Today
- 2 Words From Fed Chair Kevin Warsh Just Changed the Game for Wall Street
- Google Goes Nuclear With Power Upgrade Agreement in Georgia
- On Holding Stock Pops On $1 Billion Buyback News