
Can-Am, Farm Rescue Announce Three-Year Partnership
Source: PR Newswire
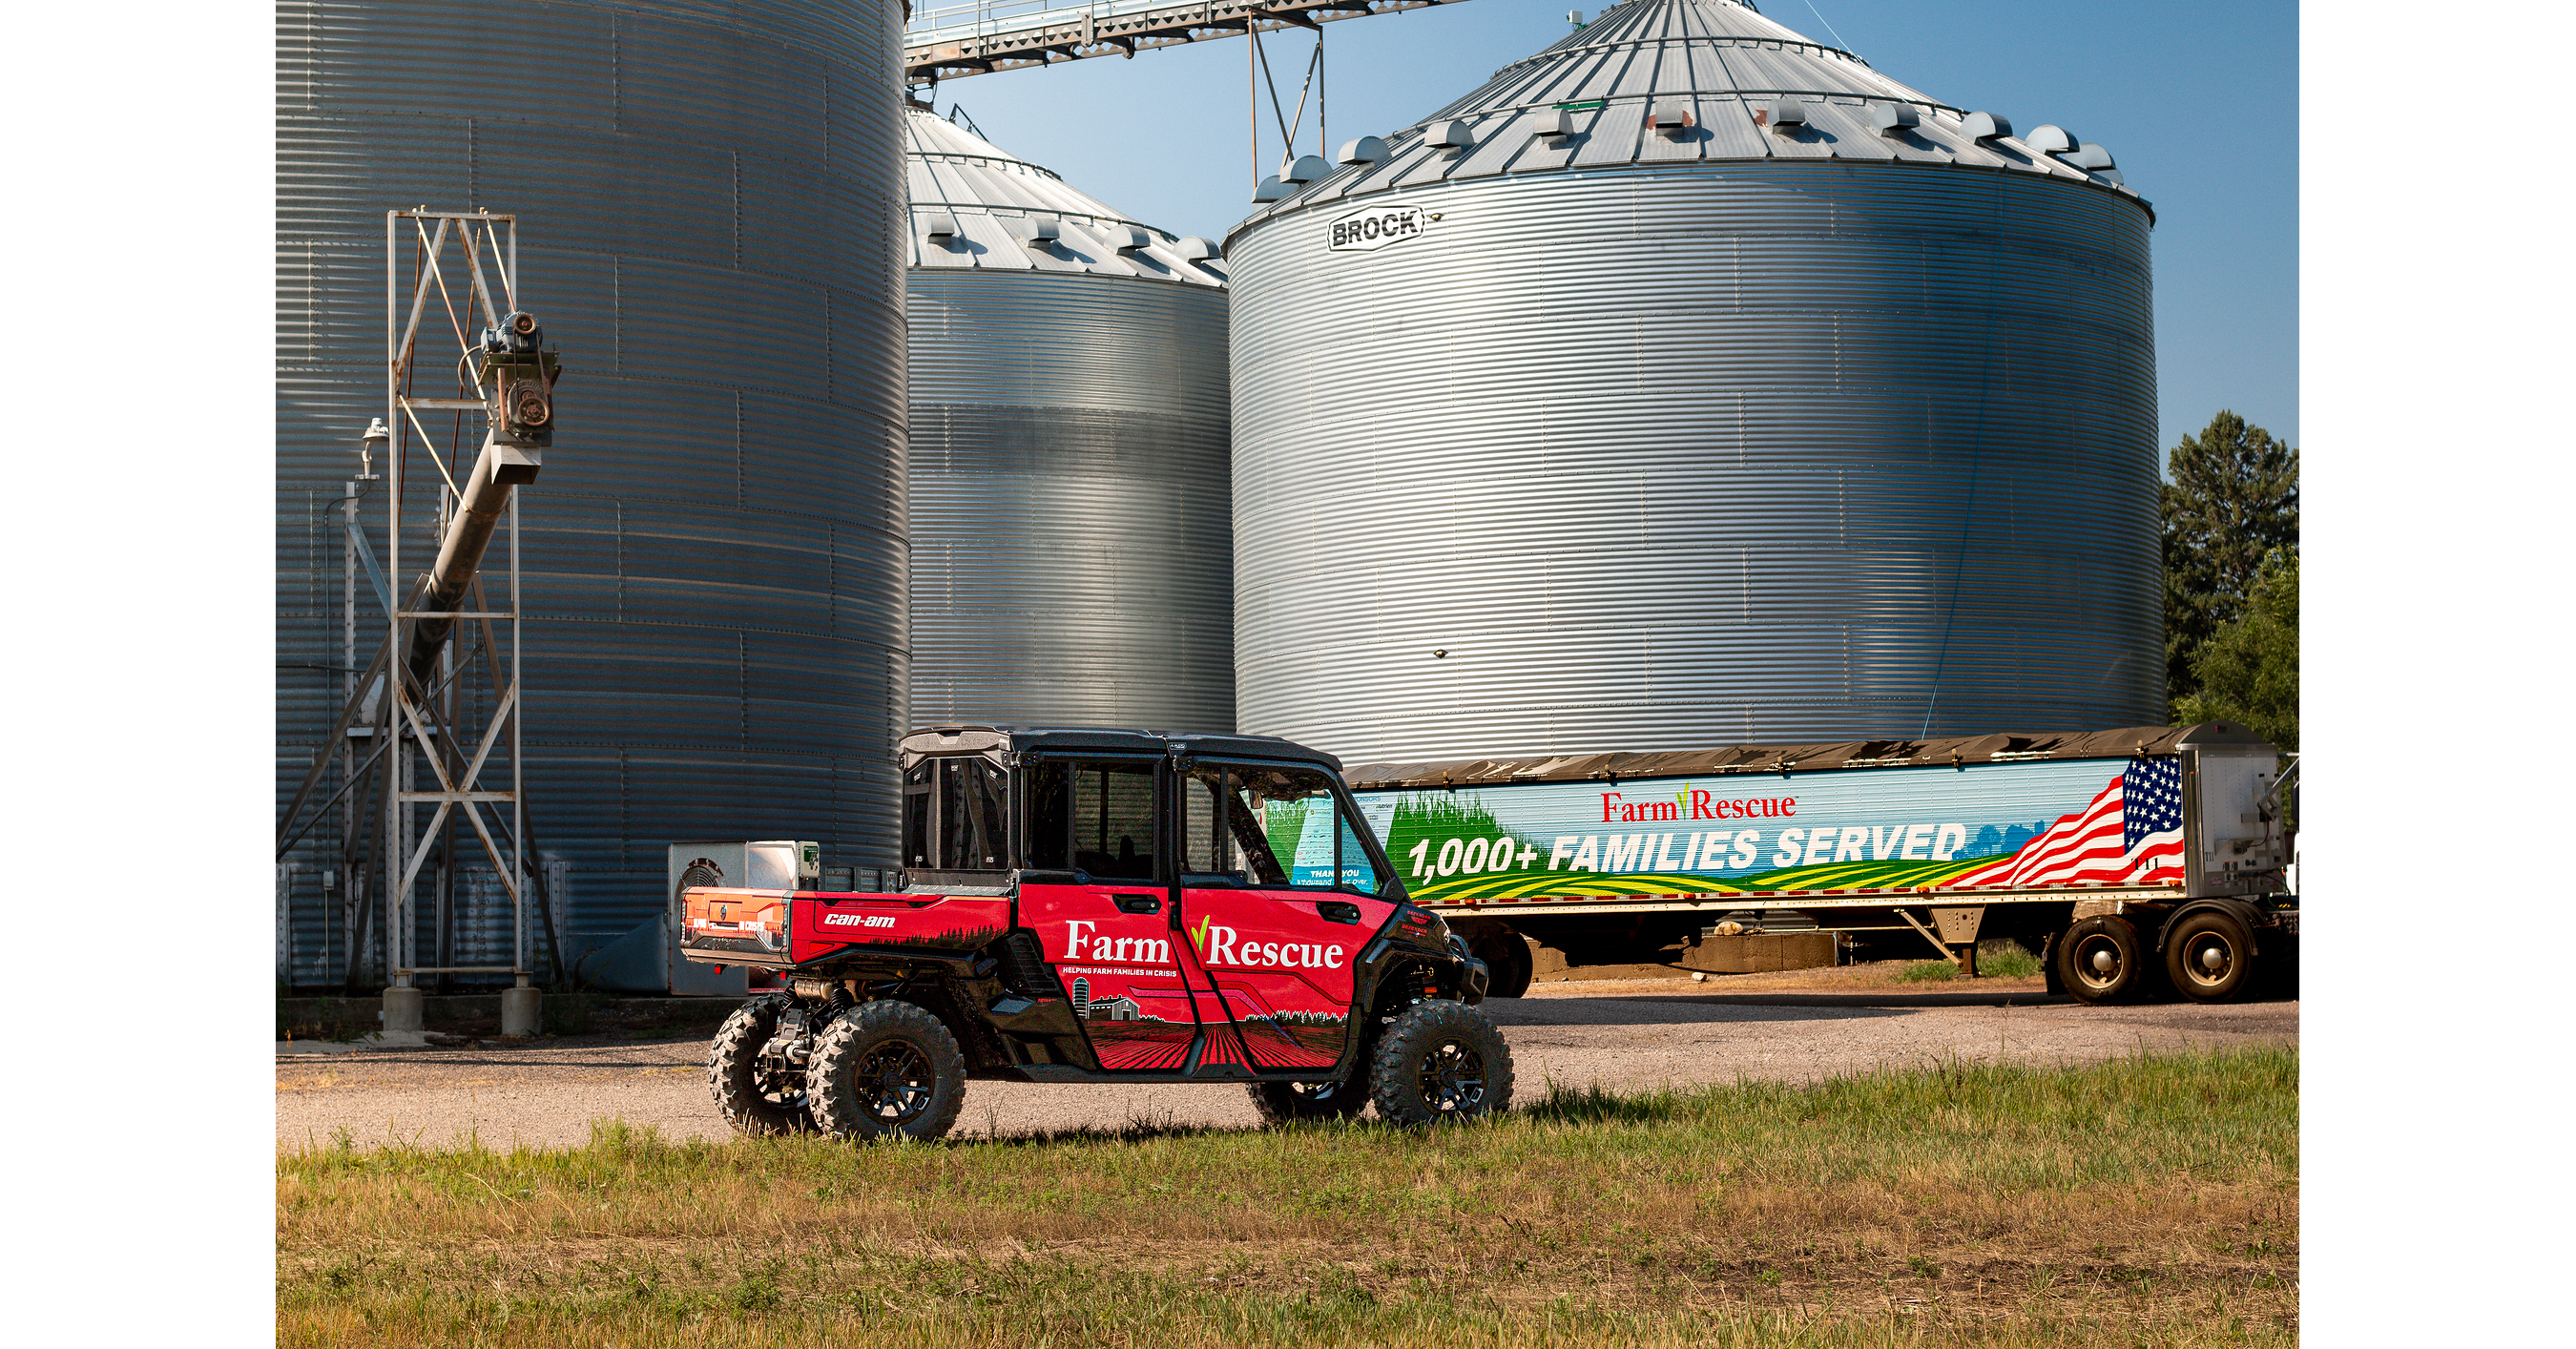
Can-Am (BRP Inc.) announced a three-year partnership with Farm Rescue, including USD$50,000 per year in direct monetary support for three years plus two Can-Am Defender fleet vehicles for field operations. The company will also provide a custom 2026 Can-Am Defender MAX Lone Star Cab HD11 (wrapped for Farm Rescue) to be auctioned in Feb. 2027, with proceeds supporting the nonprofit’s aid to farm and ranch families. The news is supportive from a community/brand perspective but is unlikely to materially move BRP’s financials or broader markets.
Analysis
This is a brand-placement event, not a fundamental earnings catalyst. The only plausible economic benefit is incremental mindshare in a high-LTV customer base where utility vehicles are bought on trust, dealer advocacy, and farm credibility; that can help Can-Am defend share against Polaris in the UTV channel, but it is unlikely to move quarterly revenue or margins on its own.
The second-order read-through is more about channel positioning than demand creation: if BRP can use agricultural utility narratives to strengthen dealer pull-through, it may support accessory attach and replacement cycles over the next 1-3 quarters. That matters most if North American off-road demand is still soft, because small share gains in a weak category can preserve pricing power while less differentiated competitors discount.
The contrarian view is that investors may be overweighting any ESG/community angle here. A three-year commitment of this size is immaterial versus BRP’s sales base, so the stock should only react if this is the first sign of a broader rural marketing push or if it coincides with improving dealer inventory and bookings. Falsifier: if off-road wholesale shipments, dealer inventories, or management commentary on UTV share do not improve over the next 1-2 quarters, the thesis is just PR with no P&L impact.
Risk/catalyst horizon is short for sentiment, longer for share. Near-term, any pop in DOO should fade unless paired with evidence of stronger U.S. agriculture demand or better channel checks; over 6-18 months, the real driver remains product mix, promotional intensity, and consumer credit conditions, not sponsorships.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- No standalone trade: treat DOO as a hold-for-now; do not buy strength off this release alone. Reassess only after next quarter's dealer inventory and off-road wholesale data.
- If entering DOO, wait for a post-news fade and pair it with a stop if UTV/channel commentary does not improve within 1-2 quarters; upside depends on measurable share stabilization, not brand noise.
- Relative-value idea: long DOO / short PII only if channel checks show Can-Am gaining utility share in the Midwest farm segment over the next 1-3 months; otherwise the spread is likely to mean-revert.
- Watch DE and rural retail proxies for corroboration rather than the press release itself; if ag capex weakens, this partnership becomes less relevant and the DOO bull case should be reduced.
- Set an alert for BRP's next earnings call: any mention of stronger off-road bookings, lower promotional spend, or improved dealer orders would be the first tradable confirmation; absent that, avoid chasing.
More News
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- The Tesla Roadster 2 Is Here—and It Flies
- Hybe shares jump 10% as K-pop sensation BTS' tour lifts earnings hopes
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Evaluate AI Report Writers for Financial Analysis
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements