
Middle Market Advisory Firm Growth Operators® Names Molly Hiller, Chief Executive Officer
Source: PR Newswire
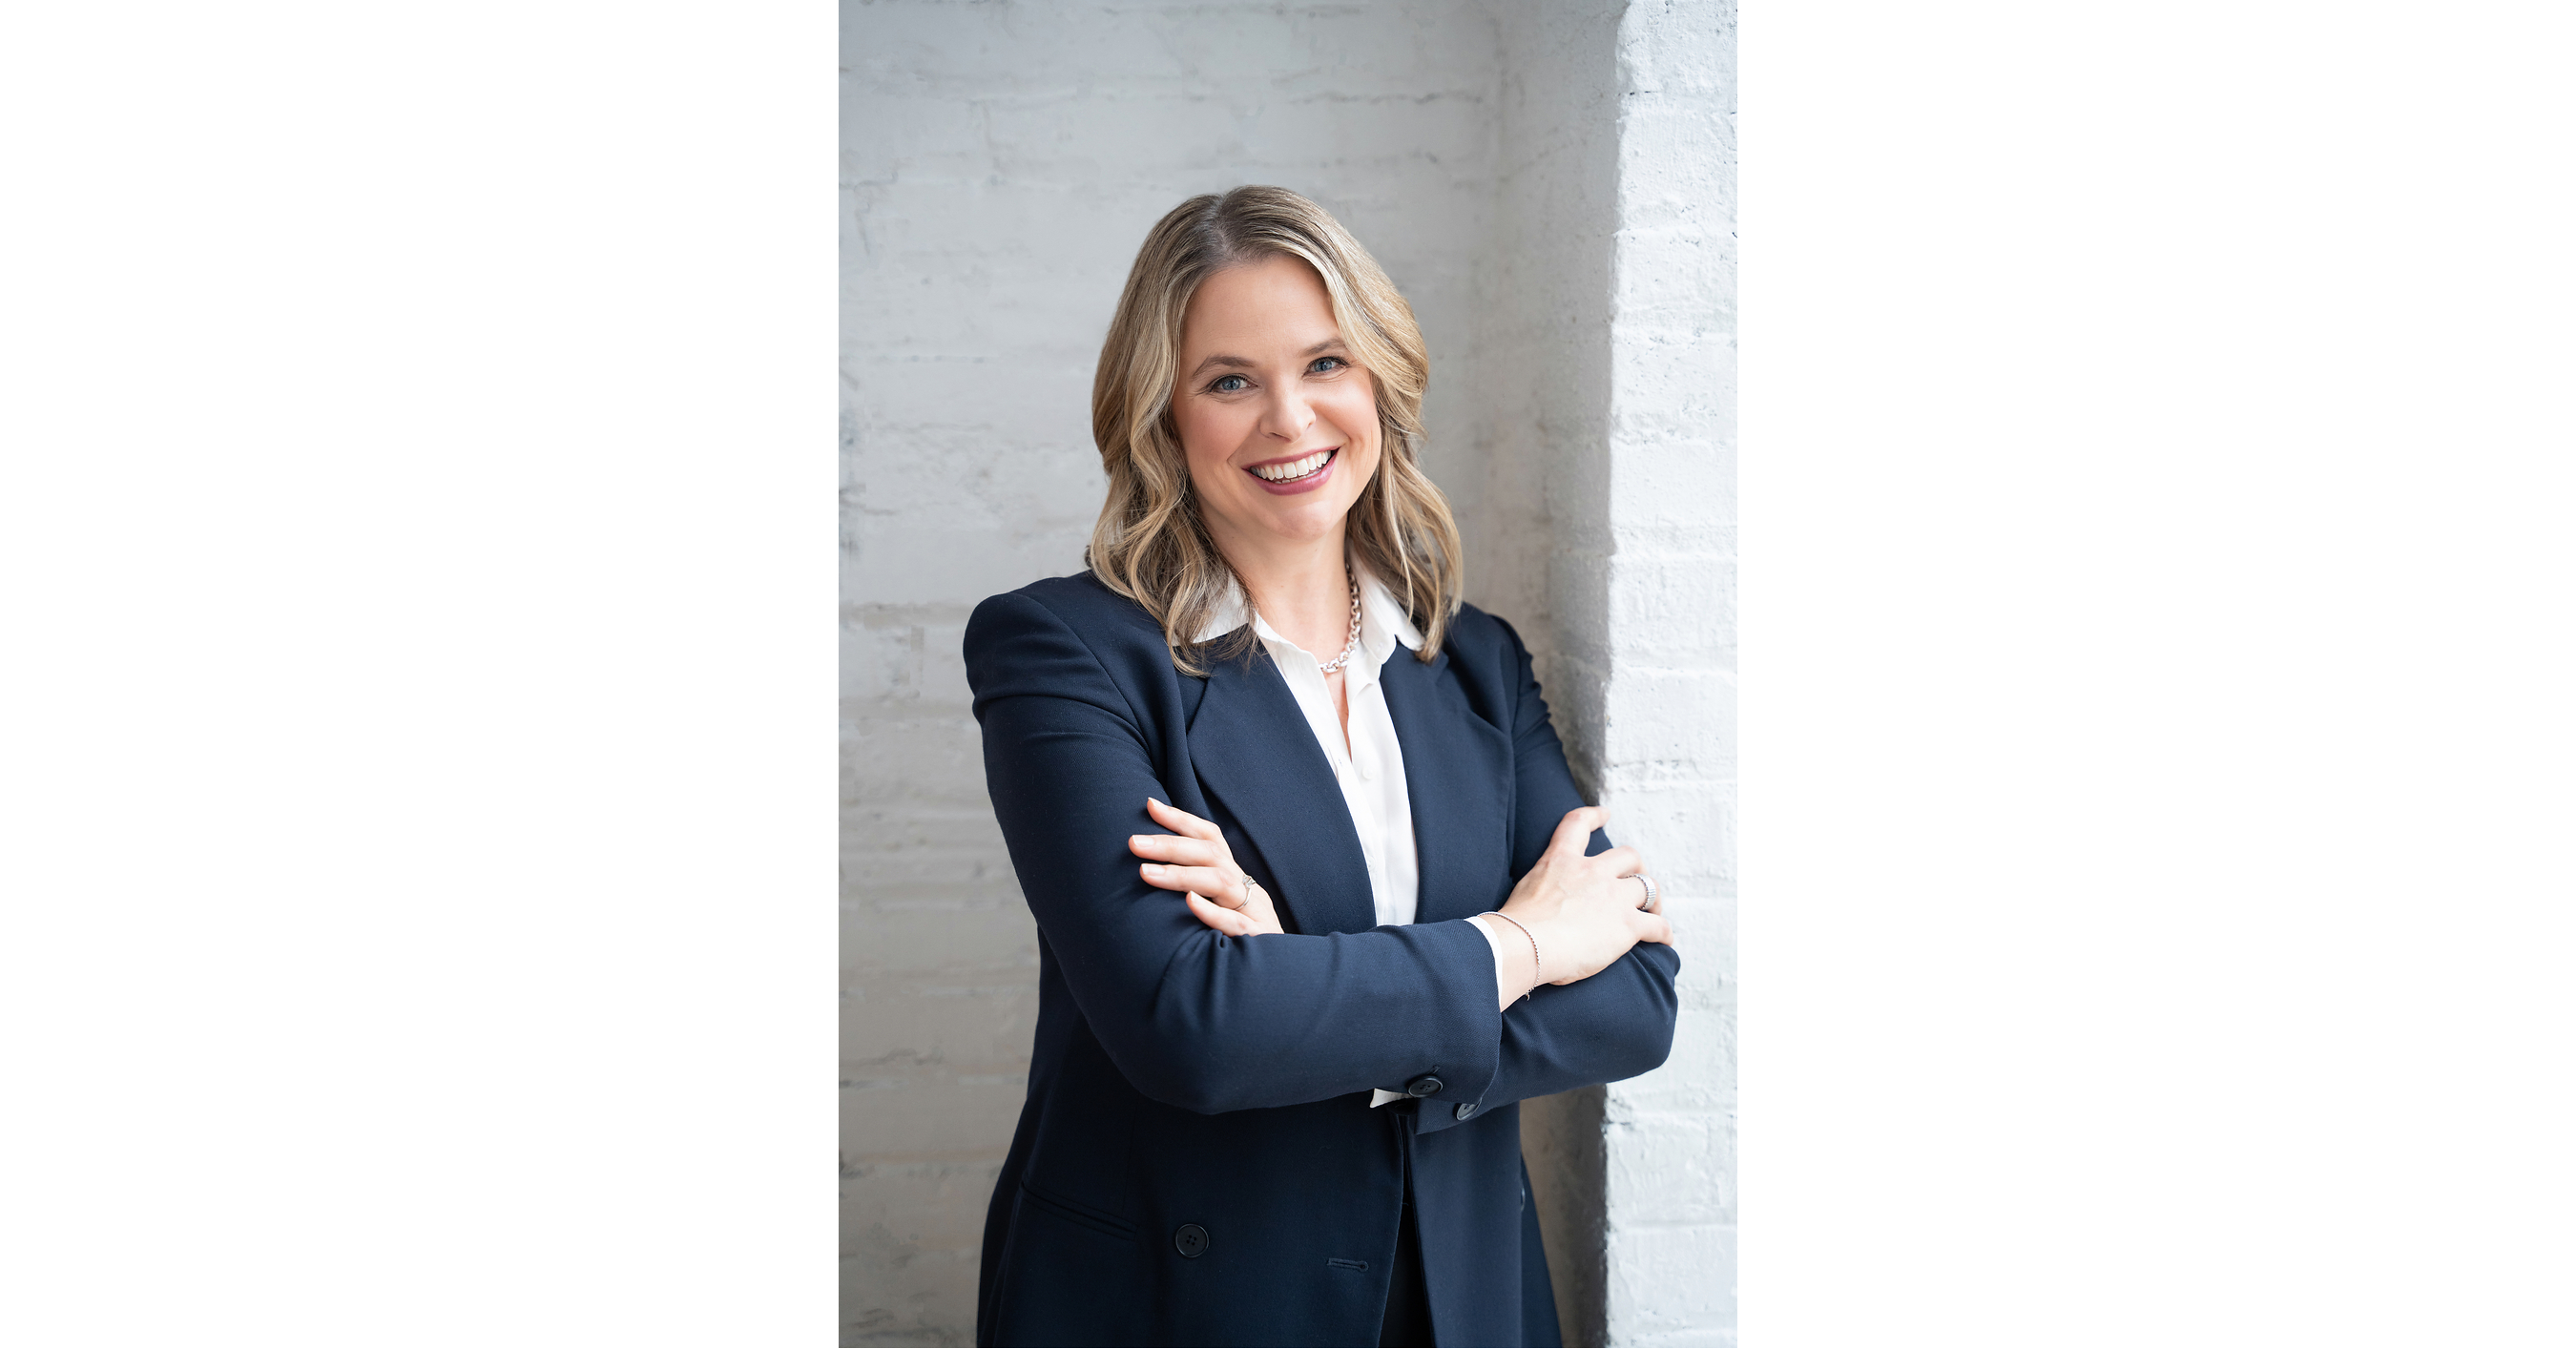
Growth Operators named co-founder Molly Hiller CEO, succeeding Rick Nordvold, who will remain Executive Chairman while leading North Partners, the firm's long-term controlling owner. The middle-market consultancy reported 51% three-year revenue growth and its sixth consecutive Inc. 5000 recognition, while expanding capabilities in strategy, talent, IT and decision intelligence/AI. The leadership transition supports a broader operating platform but is unlikely to have significant public-market implications given the firm's private ownership.
Analysis
This is not a TGT-specific catalyst: the executive’s historical affiliation does not establish a current commercial, governance, or economic linkage. With no disclosed mandate, vendor relationship, ownership connection, or financial exposure, the appropriate base case is zero near-term impact on TGT estimates or valuation.
The more relevant signal is private-equity demand for embedded operating support, particularly around finance, technology modernization, and AI deployment. If this model scales, it modestly intensifies competition for experienced interim executives and operating talent—an indirect cost pressure for middle-market sponsors and portfolio companies rather than a public-equity read-through. Public consultancies with substantial PE-facing practices, including ACN and GIB, are more plausible beneficiaries of sustained sponsor demand, though this announcement alone is not investable.
Over 6-18 months, a controlled-owner structure can support longer-duration capability investment versus a typical founder-led advisory firm, but the claimed growth and AI expansion are privately reported and lack the utilization, backlog, pricing, and margin data needed to underwrite a revenue inflection. The key falsifier for any broader consulting-demand thesis would be deteriorating PE deal volume, lower sponsor deployment activity, or evidence that AI reduces rather than expands demand for fractional operators and implementation support.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No action in TGT: treat the item as non-material unless TGT discloses a supplier, client, board, or strategic relationship with Growth Operators or North Partners.
- Maintain ACN and GIB on a 1-3 month watchlist for corroborating evidence of PE-backed transformation demand; require improving bookings/backlog and management commentary on pricing or utilization before adding exposure.
- For private-markets exposure, monitor quarterly middle-market M&A volumes and PE capital deployment over the next 6-12 months. A sustained acceleration would support operating-consulting demand; a renewed deal slowdown invalidates the proposed spillover.
More News
- Nvidia is approaching a breakout level. Plus, what we want to see from Micron
- Target has been on fire this year. HSBC sees more upside ahead
- Target upgraded at HSBC as footfall points to turnaround gaining momentum
- Gen Z’s 'little treat’ economy is thriving. These financial products help you enjoy responsibly
- South Korea’s exports hit record high on AI boom
- Asian stocks dip, bonds in focus after torrid September